



 Chat with AI
Exam 13: The Costs of Production

Exam 1: Ten Principles of Economics455 Questions
Exam 2: Thinking Like an Economist643 Questions
Exam 3: Interdependence and the Gains From Trade547 Questions
Exam 4: The Market Forces of Supply and Demand693 Questions
Exam 5: Elasticity and Its Application626 Questions
Exam 6: Supply, Demand, and Government Policies668 Questions
Exam 7: Consumers, Producers, and the Efficiency of Markets547 Questions
Exam 8: Applications: the Costs of Taxation509 Questions
Exam 9: Application: International Trade521 Questions
Exam 10: Externalities543 Questions
Exam 11: Public Goods and Common Resources452 Questions
Exam 12: The Design of the Tax System664 Questions
Exam 13: The Costs of Production649 Questions
Exam 14: Firms in Competitive Markets604 Questions
Exam 15: Monopoly662 Questions
Exam 16: Monopolistic Competition649 Questions
Exam 17: Oligopoly522 Questions
Exam 18: The Markets for the Factors of Production592 Questions
Exam 19: Earnings and Discrimination511 Questions
Exam 20: Income Inequality and Poverty478 Questions
Exam 21: The Theory of Consumer Choice570 Questions
Exam 22: Frontiers in Microeconomics461 Questions
Exam 23: Measuring a Nation S Income547 Questions
Exam 24: Measuring the Cost of Living565 Questions
Exam 25: Production and Growth527 Questions
Exam 26: Saving, Investment, and the Financial System637 Questions
Exam 27: Tools of Finance534 Questions
Exam 28: Unemployment and Its Natural Rate701 Questions
Exam 29: The Monetary System540 Questions
Exam 30: Money Growth and Inflation504 Questions
Exam 31: Open-Economy Macroeconomics: Basic Concepts540 Questions
Exam 32: A Macroeconomic Theory of the Open Economy511 Questions
Exam 33: Aggregate Demand and Aggregate Supply572 Questions
Exam 34: The Influence of Monetary and Fiscal Policy on Aggregate Demand523 Questions
Exam 35: The Short-Run Tradeoff Between Inflation and Unemployment536 Questions
Exam 36: Six Debates Over Macroeconomic Policy354 Questions
Select questions type


Suppose that a firm's long-run average total costs of producing hand-crafted chairs is $300 when it produces 10,000 chairs and $325 when it produces 11,000 chairs. For this range of output, the firm is likely experiencing
(Multiple Choice)
4.9/5  (79)
(79) Figure 13-7 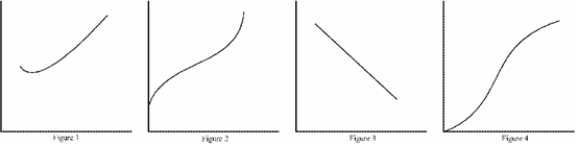 -Refer to Figure 13-7. Which of the figures represents the total cost curve for a typical firm?
 (Multiple Choice)
4.9/5 (71)
(71) Riva crafts and sells hard cider as a part-time job. She can bottle and sell four cases in a week. She is considering hiring her friend Atul to help her. Atul can bottle and sell three cases per week. What is the maximum total output possible if Riva hires Atul?
(Multiple Choice)
4.9/5 (79)
(79) There is general agreement among economists that the long-run time period exceeds one year.
(True/False)
4.9/5 (73)
(73) Suppose that a firm has only one variable input, labor, and firm output is zero when labor is zero. When the firm hires 6 workers the firm produces 90 units of output. Fixed costs of production are $6 and the variable cost per unit of labor is $10. The marginal product of the seventh unit of labor is 4. Given this information, what is the marginal cost of production when the firm hires the 7th worker?
(Multiple Choice)
4.9/5 (82)
(82) Jaxon borrows $10,000 from a bank and withdraws $20,000 from his personal savings to open a tattoo parlor. The interest rate is 3 percent for both the bank loan and his personal savings. Jaxon also quit his job as a waiter, which paid $20,000. According to an economist, Jaxon's opportunity cost of opening the tattoo parlor equals $20,900.
(True/False)
4.8/5 (94)
(94) Scenario 13-8
Wanda owns a lemonade stand. She produces lemonade using five inputs: water, sugar, lemons, paper cups, and labor. Her costs per glass are as follows: $0.01 for water, $0.02 for sugar, $0.03 for lemons, $0.02 for cups, and $0.10 for the opportunity cost of her labor. She can sell 300 glasses for $0.50 each.
-Refer to Scenario 13-8. What are Wanda's total economic costs per glass?
(Multiple Choice)
4.7/5 (85)
(85) If Franco's Pizza Parlor knows that the marginal cost of the 500th pizza is $3.50 and that the average total cost of making 499 pizzas is $3.30, then
(Multiple Choice)
4.8/5 (88)
(88) A second or third worker may have a higher marginal product than the first worker in certain circumstances.
(True/False)
4.9/5 (77)
(77) Ryan sells 200 plastic ball point pens at $0.50 each. His total costs are $25. His profits are
(Multiple Choice)
4.9/5 (73)
(73) Let L represent the number of workers hired by a firm, and let Q represent that firm's quantity of output. Assume two points on the firm's production function are (L=6,Q=147) and (L=7,Q=184). The marginal product of the seventh worker is
(Multiple Choice)
4.9/5 (101)
(101) Jacqui decides to open her own business and earns $50,000 in accounting profit the first year. When deciding to open her own business, she withdrew $20,000 from her savings, which earned 5 percent interest. She also turned down three separate job offers with annual salaries of $30,000, $40,000, and $45,000. What is Jacqui's economic profit from running her own business?
(Multiple Choice)
4.9/5 (67)
(67) If the average-total-cost curve is falling, then the marginal-cost curve must also be falling.
(True/False)
4.7/5 (84)
(84) Scenario 13-2
Chelsea wants to start her own Christmas ornament business. She can purchase a suitable factory that costs $100,000. Chelsea currently has $150,000 in the bank earning 3 percent interest per year.
-Refer to Scenario 13-2. Suppose Chelsea purchases the factory using $50,000 of her own money and $50,000 borrowed from a bank at an interest rate of 6 percent. What is Chelsea's annual opportunity cost of purchasing the factory?
(Multiple Choice)
4.9/5 (75)
(75) If an industry exhibits economies of scale, one larger firm may be able to produce goods at a lower long-run average cost than two smaller firms.
(True/False)
4.9/5 (94)
(94) Randy is a minor-league baseball player. His current cumulative batting average is 0.270. Randy believes that if he can raise his cumulative batting average to 0.300, he will have a chance to play in the major leagues. Which of the following statements is correct?
(Multiple Choice)
4.8/5 (74)
(74) Table 13-17
Consider the following table of long-run total cost for four different firms: 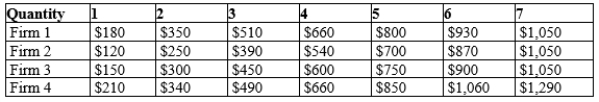 -Refer to Table 13-17. Which firm's long-run marginal cost decreases as output increases?
 (Multiple Choice)
4.9/5 (77)
(77) In the long run, a factory is usually considered a fixed input.
(True/False)
5.0/5 (79)
(79) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)