



 Chat with AI
Exam 14: Firms in Competitive Markets

Exam 1: Ten Principles of Economics455 Questions
Exam 2: Thinking Like an Economist645 Questions
Exam 3: Interdependence and the Gains From Trade550 Questions
Exam 4: The Market Forces of Supply and Demand693 Questions
Exam 5: Elasticity and Its Application625 Questions
Exam 6: Supply, Demand, and Government Policies671 Questions
Exam 7: Consumers, Producers, and the Efficiency of Markets547 Questions
Exam 8: Application: The Costs of Taxation507 Questions
Exam 9: Application: International Trade521 Questions
Exam 10: Externalities543 Questions
Exam 11: Public Goods and Common Resources453 Questions
Exam 12: The Design of the Tax System563 Questions
Exam 13: The Costs of Production649 Questions
Exam 14: Firms in Competitive Markets608 Questions
Exam 15: Monopoly662 Questions
Exam 16: Monopolistic Competition649 Questions
Exam 17: Oligopoly522 Questions
Exam 18: The Markets for the Factors of Production592 Questions
Exam 19: Earnings and Discrimination511 Questions
Exam 20: Income Inequality and Poverty478 Questions
Exam 21: The Theory of Consumer Choice568 Questions
Exam 22: Frontiers in Microeconomics461 Questions
Select questions type


Table 14-8
Suppose that a firm in a competitive market faces the following revenues and costs: 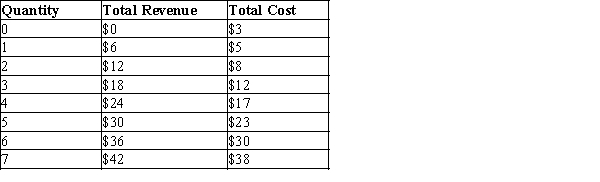 -Refer to Table 14-8. In order to maximize profits, the firm will produce
 (Multiple Choice)
4.8/5  (83)
(83) A competitive market begins in a situation of long-run equilibrium. Then, there is an increase in demand. Describe the process that eventually leads to a new long-run equilibrium.
(Essay)
4.8/5 (94)
(94) Which of the following represents the firm's short-run condition for shutting down?
(Multiple Choice)
4.9/5 (91)
(91) Mr. Rogers sells colored pencils. The colored-pencil industry is competitive. Mr. Rogers hires a business consultant to analyze his company's financial records. The consultant recommends that Mr. Rogers increase his production. The consultant must have concluded that Mr. Roger's
(Multiple Choice)
4.8/5 (79)
(79) Whenever firms in a perfectly competitive market produce the output level where marginal revenue equals marginal cost, we know that the firm is earning an economic profit.
(True/False)
4.9/5 (79)
(79) A firm is currently producing 100 units of output per day. The manager reports to the owner that producing the 100th unit costs the firm $5. The firm can sell the 100th unit for $4.75. The firm should continue to produce 100 units in order to maximize its profits (or minimize its losses).
(True/False)
4.7/5 (81)
(81) Why would a firm in a perfectly competitive market always choose to set its price equal to the current market price? If a firm set its price below the current market price, what effect would this have on the market?
(Essay)
4.7/5 (67)
(67) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)