



 Chat with AI
Exam 14: Firms in Competitive Markets

Exam 1: Ten Principles of Economics455 Questions
Exam 2: Thinking Like an Economist645 Questions
Exam 3: Interdependence and the Gains From Trade550 Questions
Exam 4: The Market Forces of Supply and Demand693 Questions
Exam 5: Elasticity and Its Application625 Questions
Exam 6: Supply, Demand, and Government Policies671 Questions
Exam 7: Consumers, Producers, and the Efficiency of Markets547 Questions
Exam 8: Application: The Costs of Taxation507 Questions
Exam 9: Application: International Trade521 Questions
Exam 10: Externalities543 Questions
Exam 11: Public Goods and Common Resources453 Questions
Exam 12: The Design of the Tax System563 Questions
Exam 13: The Costs of Production649 Questions
Exam 14: Firms in Competitive Markets608 Questions
Exam 15: Monopoly662 Questions
Exam 16: Monopolistic Competition649 Questions
Exam 17: Oligopoly522 Questions
Exam 18: The Markets for the Factors of Production592 Questions
Exam 19: Earnings and Discrimination511 Questions
Exam 20: Income Inequality and Poverty478 Questions
Exam 21: The Theory of Consumer Choice568 Questions
Exam 22: Frontiers in Microeconomics461 Questions
Select questions type


Table 14-16
The table represents the demand information for a firm in a competitive market. 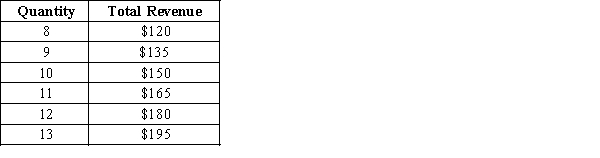
-Refer to Table 14-16. For this firm, the price is
-Refer to Table 14-16. For this firm, the price is (Multiple Choice)
5.0/5  (81)
(81) The competitive firm's short-run supply curve is that portion of the
(Multiple Choice)
4.9/5 (93)
(93) Which of the following is not a characteristic of a perfectly competitive market?
(Multiple Choice)
4.9/5 (84)
(84) A firm will shut down in the short run if the total revenue that it would get from producing and selling its output is less than its
(Multiple Choice)
4.7/5 (86)
(86) Suppose that a firm operating in perfectly competitive market sells 100 units of output. Its total revenues from the sale are $500. Which of the following statements is correct? (i)
Marginal revenue equals $5.
(ii)
Average revenue equals $5.
(iii)
Price equals $5.
(Multiple Choice)
4.9/5 (65)
(65) Figure 14-9
In the figure below, panel (a) depicts the linear marginal cost of a firm in a competitive market, and panel (b) depicts the linear market supply curve for a market with a fixed number of identical firms. 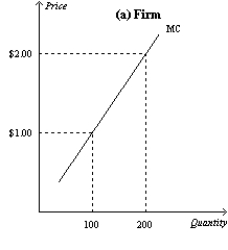
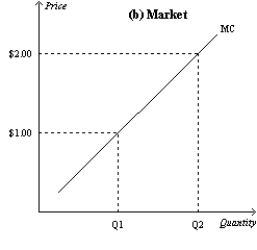 -Refer to Figure 14-9. If there are 300 identical firms in this market, what level of output will be supplied to the market when price is $1.00?
 (Multiple Choice)
4.8/5 (76)
(76) Cold Duck Airlines flies between Tacoma and Portland. The company leases planes on a year-long contract at a cost that averages $600 per flight. Other costs (fuel, flight attendants, etc.) amount to $550 per flight. Currently, Cold Duck's revenues are $1,000 per flight. All prices and costs are expected to continue at their present levels. If it wants to maximize profit, Cold Duck Airlines should
(Multiple Choice)
4.9/5 (82)
(82) When firms are neither entering nor exiting a perfectly competitive market,
(Multiple Choice)
4.9/5 (80)
(80) If a competitive firm is currently producing a level of output at which profit is not maximized, then it must be true that
(Multiple Choice)
4.8/5 (71)
(71) Table 14-11
Suppose that a firm in a competitive market faces the following prices and costs: 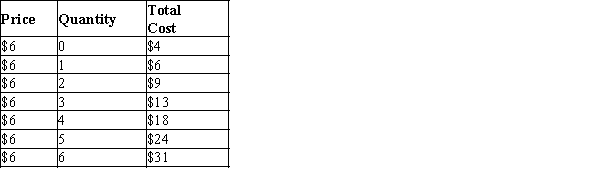 -Refer to Table 14-11. If the firm is producing 3 units of output, it should produce
 (Multiple Choice)
4.7/5 (77)
(77) Willie's Wading Adventures sells hip waders for fishing and duck hunting in a perfectly competitive market. If hip waders sell for $100 each and average total cost per unit is $95 at the profit-maximizing output level, then in the long run
(Multiple Choice)
4.8/5 (83)
(83) The marginal firm in a competitive market will earn zero economic profit in the long run.
(True/False)
4.8/5 (85)
(85) In the short run for a particular market, there are 5,000 firms. Each firm has a marginal cost of $7 when it produces 200 units of output. One point on the market supply curve is
(Multiple Choice)
4.8/5 (68)
(68) A firm in a competitive market has the following cost structure: 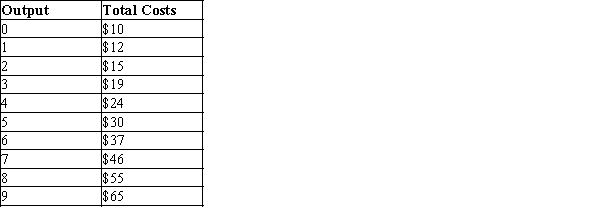 If the market price is $8, how many units of output should the firm produce to maximize profit?
 (Multiple Choice)
4.9/5 (87)
(87) All firms operating in a perfectly competitive market produce unique goods.
(True/False)
4.7/5 (72)
(72) When existing firms in a competitive market are profitable, an incentive exists for
(Multiple Choice)
5.0/5 (80)
(80) In the short run, a market consists of 100 identical firms. The market price is $6, and the total cost to each firm of producing various levels of output is given in the table below. What will total quantity supplied be in the market? 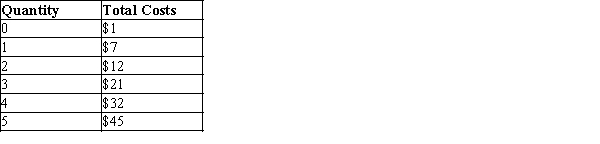
(Multiple Choice)
4.8/5 (87)
(87) Regardless of the cost structure of firms in a competitive market, in the long run
(Multiple Choice)
4.8/5 (75)
(75) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)