



 Chat with AI
Exam 14: Firms in Competitive Markets

Exam 1: Ten Principles of Economics455 Questions
Exam 2: Thinking Like an Economist645 Questions
Exam 3: Interdependence and the Gains From Trade550 Questions
Exam 4: The Market Forces of Supply and Demand693 Questions
Exam 5: Elasticity and Its Application625 Questions
Exam 6: Supply, Demand, and Government Policies671 Questions
Exam 7: Consumers, Producers, and the Efficiency of Markets547 Questions
Exam 8: Application: The Costs of Taxation507 Questions
Exam 9: Application: International Trade521 Questions
Exam 10: Externalities543 Questions
Exam 11: Public Goods and Common Resources453 Questions
Exam 12: The Design of the Tax System563 Questions
Exam 13: The Costs of Production649 Questions
Exam 14: Firms in Competitive Markets608 Questions
Exam 15: Monopoly662 Questions
Exam 16: Monopolistic Competition649 Questions
Exam 17: Oligopoly522 Questions
Exam 18: The Markets for the Factors of Production592 Questions
Exam 19: Earnings and Discrimination511 Questions
Exam 20: Income Inequality and Poverty478 Questions
Exam 21: The Theory of Consumer Choice568 Questions
Exam 22: Frontiers in Microeconomics461 Questions
Select questions type


Table 14-7
Suppose that a firm in a competitive market faces the following revenues and costs: 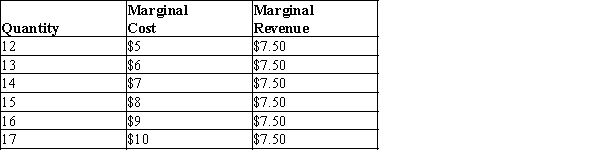 -Refer to Table 14-7. If the firm is currently producing 14 units, what would you advise the owners?
 (Multiple Choice)
4.8/5  (88)
(88) For a particular competitive firm, the minimum value of average variable cost (AVC) is $12 and is reached when 200 units of output are produced. For the same firm, the minimum value of average total cost (ATC) is $15 and is reached when 230 units of output are produced. Which of the following statements is correct?
(Multiple Choice)
4.8/5 (82)
(82) Table 14-14
The following table presents cost and revenue information for Bob's bakery production and sales. 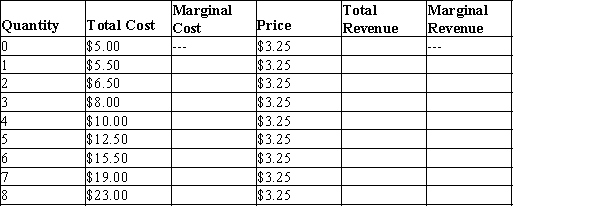 -Refer to Table 14-14. When Bob produces and sells the profit-maximizing quantity, how much profit does he earn?
 (Multiple Choice)
4.9/5 (92)
(92) A firm operating in a perfectly competitive industry will continue to operate in the short run but earn losses if the market price is less than that firm's average variable cost but greater than the firm's average fixed cost.
(True/False)
4.7/5 (73)
(73) Suppose the long-run supply curve for a good is upward-sloping. The upward slope could be explained by
(Multiple Choice)
4.7/5 (74)
(74) A competitive firm currently produces and sells 7,500 units of output at a price of $2.50 per unit. The firm's average fixed cost is $0.75 and its average total cost is $2.80. In the short run, should the firm continue to operate?
(Essay)
4.8/5 (77)
(77) Figure 14-7 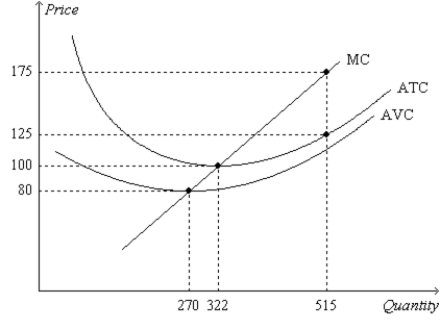 -Refer to Figure 14-7. In the long run, the firm will exit the market if the price of the good is
 (Multiple Choice)
4.9/5 (74)
(74) Land of Many Lakes (LML) sells butter to a broker in Albert Lea, Minnesota. Because the market for butter is generally considered to be competitive, LML does not
(Multiple Choice)
4.7/5 (81)
(81) Suppose that a competitive market is initially in equilibrium. Then demand increases. If some resources used in production are not available in sufficient quantities for entering firms,
(Multiple Choice)
4.9/5 (78)
(78) A firm that has little ability to influence market prices operates in a
(Multiple Choice)
4.8/5 (76)
(76) When it produces and sells 90 units of output, a competitive firm's average total cost is $42 and its profit is $360. What is the firm's marginal revenue if it sells 100 units of output?
(Essay)
4.9/5 (78)
(78) Suppose a competitive market is comprised of firms that face identical cost curves. The firms experience an increase in demand that results in positive profits for the firms. Which of the following events are then most likely to occur? (i)
New firms will enter the market.
(ii)
In the short run, price will rise; in the long run, price will rise further.
(iii)
In the long run, all firms will be producing at their efficient scale.
(Multiple Choice)
4.9/5 (80)
(80) If firms are competitive and profit maximizing, the price of a good equals the
(Multiple Choice)
4.9/5 (83)
(83) Scenario 14-4
The information below applies to a competitive firm that sells its output for $40 per unit.
• When the firm produces and sells 150 units of output, its average total cost is $24.50.
• When the firm produces and sells 151 units of output, its average total cost is $24.55.
-Refer to Scenario 14-4. Suppose the firm is currently producing and selling 150 units of output. Should the firm increase its output to 151 units?
(Multiple Choice)
4.8/5 (66)
(66) When market conditions in a competitive industry are such that firms cannot cover their total production costs, then
(Multiple Choice)
4.9/5 (76)
(76) Table 14-4
The table represents a demand curve faced by a firm in a competitive market. 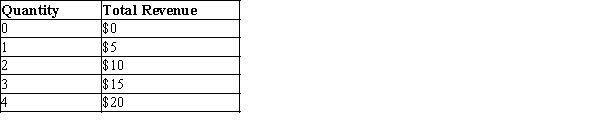 -Refer to Table 14-4. For this firm, the marginal revenue is
 (Multiple Choice)
4.8/5 (78)
(78) A miniature golf course is a good example of where fixed costs become relevant to the decision of when to open and when to close for the season.
(True/False)
4.9/5 (75)
(75) Which of the following firms is the closest to being a perfectly competitive firm?
(Multiple Choice)
4.9/5 (69)
(69) Scenario 14-4
The information below applies to a competitive firm that sells its output for $40 per unit.
• When the firm produces and sells 150 units of output, its average total cost is $24.50.
• When the firm produces and sells 151 units of output, its average total cost is $24.55.
-Refer to Scenario 14-4. Let Q represent the quantity of output. Which of the following magnitudes has the same value at Q = 150 and at Q = 151?
(Multiple Choice)
4.8/5 (85)
(85) Table 14-12
Bill's Birdhouses 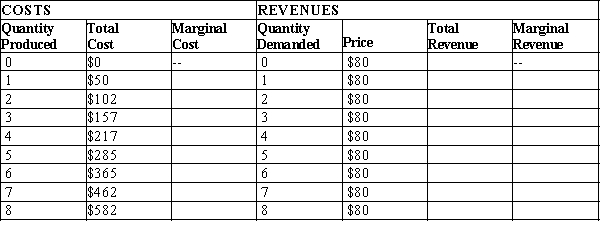 -Refer to Table 14-12. What is the average revenue when 4 units are sold?
 (Multiple Choice)
4.9/5 (72)
(72) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)