



 Chat with AI
Exam 16: Monopolistic Competition

Exam 1: Ten Principles of Economics455 Questions
Exam 2: Thinking Like an Economist643 Questions
Exam 3: Interdependence and the Gains From Trade547 Questions
Exam 4: The Market Forces of Supply and Demand693 Questions
Exam 5: Elasticity and Its Application626 Questions
Exam 6: Supply, Demand, and Government Policies668 Questions
Exam 7: Consumers, Producers, and the Efficiency of Markets547 Questions
Exam 8: Applications: the Costs of Taxation509 Questions
Exam 9: Application: International Trade521 Questions
Exam 10: Externalities543 Questions
Exam 11: Public Goods and Common Resources452 Questions
Exam 12: The Design of the Tax System664 Questions
Exam 13: The Costs of Production649 Questions
Exam 14: Firms in Competitive Markets604 Questions
Exam 15: Monopoly662 Questions
Exam 16: Monopolistic Competition649 Questions
Exam 17: Oligopoly522 Questions
Exam 18: The Markets for the Factors of Production592 Questions
Exam 19: Earnings and Discrimination511 Questions
Exam 20: Income Inequality and Poverty478 Questions
Exam 21: The Theory of Consumer Choice570 Questions
Exam 22: Frontiers in Microeconomics461 Questions
Exam 23: Measuring a Nation S Income547 Questions
Exam 24: Measuring the Cost of Living565 Questions
Exam 25: Production and Growth527 Questions
Exam 26: Saving, Investment, and the Financial System637 Questions
Exam 27: Tools of Finance534 Questions
Exam 28: Unemployment and Its Natural Rate701 Questions
Exam 29: The Monetary System540 Questions
Exam 30: Money Growth and Inflation504 Questions
Exam 31: Open-Economy Macroeconomics: Basic Concepts540 Questions
Exam 32: A Macroeconomic Theory of the Open Economy511 Questions
Exam 33: Aggregate Demand and Aggregate Supply572 Questions
Exam 34: The Influence of Monetary and Fiscal Policy on Aggregate Demand523 Questions
Exam 35: The Short-Run Tradeoff Between Inflation and Unemployment536 Questions
Exam 36: Six Debates Over Macroeconomic Policy354 Questions
Select questions type


Evaluate the following statement in the context of business-stealing and product-variety externalities: "We have too many student apartments in this town already. Statistics show that vacancy rates average 15 percent during any given semester."
(Essay)
5.0/5  (89)
(89) Figure 16-3
This figure depicts a situation in a monopolistically competitive market. 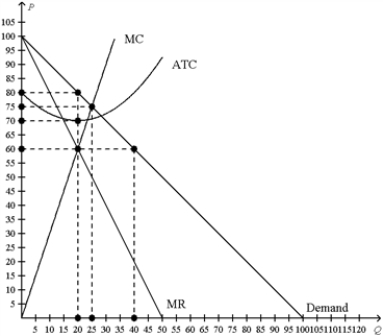 -Refer to Figure 16-3. This firm is operating
 (Multiple Choice)
4.8/5 (82)
(82) Figure 16-12 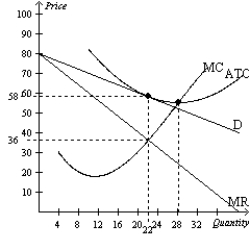 -Refer to Figure 16-12. What, if any, long run adjustment will take place in this industry?
 (Short Answer)
4.9/5 (75)
(75) When a monopolistically competitive firm is in long-run equilibrium,
(Multiple Choice)
4.9/5 (80)
(80) Policymakers have generally come to accept the view that advertising enhances the efficiency of markets.
(True/False)
4.8/5 (78)
(78) Table 16-2
The following table shows the total output produced by the top six firms as well as the total industry output for each industry. 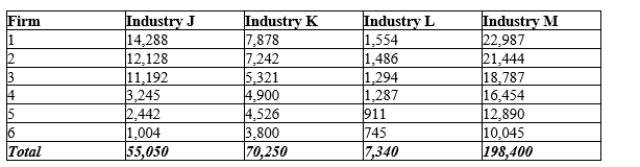 -Refer to Table 16-2. Which industry has the lowest concentration ratio?
 (Multiple Choice)
4.8/5 (69)
(69) Suppose that monopolistically competitive firms in a certain market are experiencing losses. In the transition from this initial situation to a long-run equilibrium,
(Multiple Choice)
4.9/5 (81)
(81) Scenario 16-7
Consider the problem facing two firms, YumYum and Bertollini, in the frozen food market. Each firm has just come up with an idea for a new "frozen meal for two" which it would sell for $9. Assume that the marginal cost for each new product is a constant $2, and the only fixed cost is for advertising. Each company knows that if it spends $12 million on advertising it will get 1.5 million consumers to try its new product. YumYum has done market research which suggests that its product does not have any "staying" power in the market. Even though it could get 1.5 million consumers to buy the product once, it is unlikely that they will continue to buy the product in the future. Bertollini's market research suggests that its product is very good, and consumers who try the product will continue to be consumers over the ensuing year. On the basis of its market research, Bertollini estimates that its initial 1.5 million customers will buy one unit of the product each month in the coming year, for a total of 18 million units.
-Refer to Scenario 16-7. Suppose YumYum has an opportunity to create a cheaper advertising campaign in newspapers rather than on television for its new product. This campaign will cost $8 million and is expected to result in the same 1.5 million one-time customers. YumYum should
(Multiple Choice)
4.9/5 (76)
(76) Monopolistic competition is an inefficient market structure because
(Multiple Choice)
4.7/5 (76)
(76) Which of the following conditions distinguishes monopolistic competition from perfect competition?
(Multiple Choice)
4.9/5 (77)
(77) Two college students, Mary and Maggie, are spending spring break in Florida. Mary buys a cup of coffee each morning at the local Starbucks rather than from one of the local coffee shops. Maggie claims that Mary is irrational because she never purchases Starbucks coffee at home, and Starbucks coffee costs more than the coffee sold by local shops. An economist would most likely explain Mary's behavior by suggesting that
(Multiple Choice)
4.9/5 (85)
(85) A monopolistically competitive firm is currently charging a price of $20 and producing 3,000 units/month. It faces monthly fixed costs of $1,000 and has an average variable cost of $22/unit. We would expect:
(Multiple Choice)
4.9/5 (83)
(83) In the long run, monopolistically competitive firms produce where demand equals marginal cost.
(True/False)
4.9/5 (77)
(77) One key difference between an oligopoly market and a competitive market is that oligopolistic firms
(Multiple Choice)
4.8/5 (87)
(87) A monopolistically competitive firm has the following cost structure:  The firm faces the following demand curve:
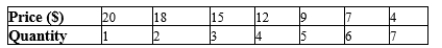 If the government forces this firm to produce at its efficient scale, it will
The firm faces the following demand curve:
If the government forces this firm to produce at its efficient scale, it will (Multiple Choice)
4.8/5 (86)
(86) Table 16-7
A monopolistically competitive firm faces the following demand schedule for its product. In addition, the firm has total fixed costs equal to 20. 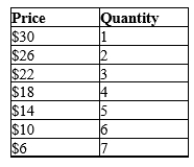 -Refer to Table 16-7. If the firm has a constant marginal cost of $7 per unit, how much profit will the firm earn at the profit-maximizing level of output?
 (Multiple Choice)
4.9/5 (72)
(72) In the long run, a monopolistically competitive firm produces at efficient scale.
(True/False)
4.8/5 (82)
(82) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)