



 Chat with AI
Exam 16: Monopolistic Competition

Exam 1: Ten Principles of Economics455 Questions
Exam 2: Thinking Like an Economist643 Questions
Exam 3: Interdependence and the Gains From Trade547 Questions
Exam 4: The Market Forces of Supply and Demand693 Questions
Exam 5: Elasticity and Its Application626 Questions
Exam 6: Supply, Demand, and Government Policies668 Questions
Exam 7: Consumers, Producers, and the Efficiency of Markets547 Questions
Exam 8: Applications: the Costs of Taxation509 Questions
Exam 9: Application: International Trade521 Questions
Exam 10: Externalities543 Questions
Exam 11: Public Goods and Common Resources452 Questions
Exam 12: The Design of the Tax System664 Questions
Exam 13: The Costs of Production649 Questions
Exam 14: Firms in Competitive Markets604 Questions
Exam 15: Monopoly662 Questions
Exam 16: Monopolistic Competition649 Questions
Exam 17: Oligopoly522 Questions
Exam 18: The Markets for the Factors of Production592 Questions
Exam 19: Earnings and Discrimination511 Questions
Exam 20: Income Inequality and Poverty478 Questions
Exam 21: The Theory of Consumer Choice570 Questions
Exam 22: Frontiers in Microeconomics461 Questions
Exam 23: Measuring a Nation S Income547 Questions
Exam 24: Measuring the Cost of Living565 Questions
Exam 25: Production and Growth527 Questions
Exam 26: Saving, Investment, and the Financial System637 Questions
Exam 27: Tools of Finance534 Questions
Exam 28: Unemployment and Its Natural Rate701 Questions
Exam 29: The Monetary System540 Questions
Exam 30: Money Growth and Inflation504 Questions
Exam 31: Open-Economy Macroeconomics: Basic Concepts540 Questions
Exam 32: A Macroeconomic Theory of the Open Economy511 Questions
Exam 33: Aggregate Demand and Aggregate Supply572 Questions
Exam 34: The Influence of Monetary and Fiscal Policy on Aggregate Demand523 Questions
Exam 35: The Short-Run Tradeoff Between Inflation and Unemployment536 Questions
Exam 36: Six Debates Over Macroeconomic Policy354 Questions
Select questions type


Table 16-5
This table shows the demand schedule, marginal cost, and average total cost for a monopolistically competitive firm. 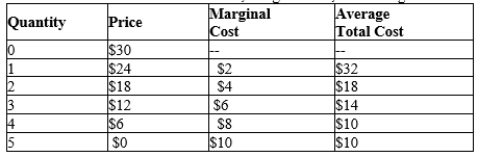 -Refer to Table 16-5. What is this firm's total cost at the profit-maximizing quantity?
 (Multiple Choice)
4.8/5  (87)
(87) The relationship between advertising and product differentiation is
(Multiple Choice)
4.9/5 (63)
(63) Economists measure a market's domination by a small number of firms with a statistic called the
(Short Answer)
4.9/5 (68)
(68) Figure 16-4 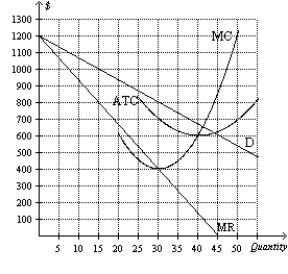 -Refer to Figure 16-4. Which of the following will occur in the long run in this industry?
 (Multiple Choice)
4.9/5 (74)
(74) A monopolistically competitive firm has the following cost structure: 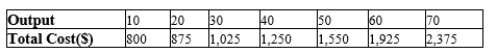 The firm faces the following demand curve:
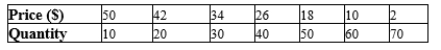 To maximize profit (or minimize losses), the firm will produce
The firm faces the following demand curve:
To maximize profit (or minimize losses), the firm will produce (Multiple Choice)
4.9/5 (88)
(88) Figure 16-5 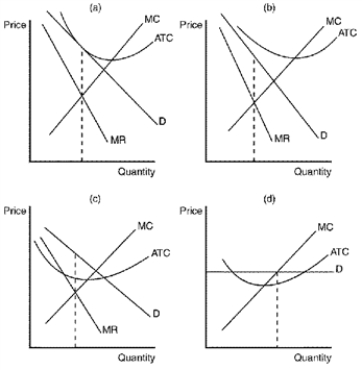 -Refer to Figure 16-5. Which of the graphs depicts a short-run equilibrium that will not encourage either the entry or exit of firms in a monopolistically competitive industry?
 (Multiple Choice)
4.8/5 (77)
(77) A monopolistically competitive industry is characterized by
(Multiple Choice)
4.8/5 (80)
(80) Suppose that monopolistically competitive firms in a certain market are earning positive profits. In the transition from this initial situation to a long-run equilibrium,
(Multiple Choice)
5.0/5 (84)
(84) Oligopoly is characterized by a few sellers offering similar products, whereas monopolistic competition is characterized by many sellers offering differentiated products.
(True/False)
4.9/5 (77)
(77) Why does a typical monopolistically competitive firm face a downward-sloping demand curve?
(Essay)
4.9/5 (72)
(72) Figure 16-12 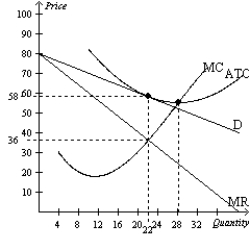 -Refer to Figure 16-12. If this firm minimized cost, how much output will it produce?
 (Short Answer)
4.7/5 (82)
(82) Figure 16-10
The figure is drawn for a monopolistically-competitive firm. 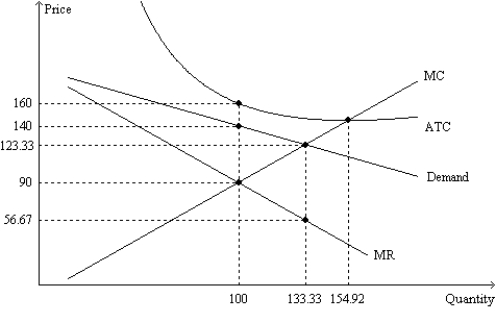 -Refer to Figure 16-10. In response to the situation represented by the figure, we would expect
 (Multiple Choice)
4.9/5 (77)
(77) As competitors enter a monopolistically competitive industry, the incumbent firms demand curves shift
(Multiple Choice)
4.9/5 (81)
(81) Scenario 16-7
Consider the problem facing two firms, YumYum and Bertollini, in the frozen food market. Each firm has just come up with an idea for a new "frozen meal for two" which it would sell for $9. Assume that the marginal cost for each new product is a constant $2, and the only fixed cost is for advertising. Each company knows that if it spends $12 million on advertising it will get 1.5 million consumers to try its new product. YumYum has done market research which suggests that its product does not have any "staying" power in the market. Even though it could get 1.5 million consumers to buy the product once, it is unlikely that they will continue to buy the product in the future. Bertollini's market research suggests that its product is very good, and consumers who try the product will continue to be consumers over the ensuing year. On the basis of its market research, Bertollini estimates that its initial 1.5 million customers will buy one unit of the product each month in the coming year, for a total of 18 million units.
-Refer to Scenario 16-7. If Bertollini decides to advertise its product it can expect to
(Multiple Choice)
5.0/5 (76)
(76) Figure 16-2. The figure is drawn for a monopolistically competitive firm. 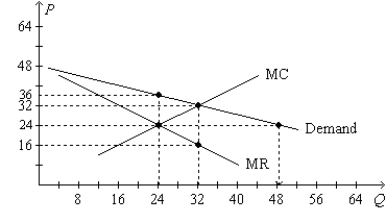 -Refer to Figure 16-2. In order to maximize profit, the firm will charge a price of
 (Multiple Choice)
4.8/5 (76)
(76) Table 16-4
This table shows the demand schedule, marginal cost, and average total cost for a monopolistically competitive firm. 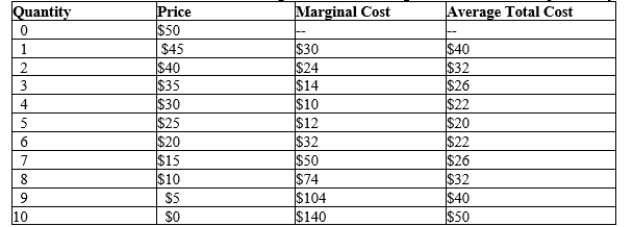 -Refer to Table 16-4. What is this firm's profit-maximizing level of output?
 (Multiple Choice)
4.8/5 (91)
(91) A markup of price over marginal cost is inconsistent with free entry and zero profit.
(True/False)
4.9/5 (78)
(78) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)