



 Chat with AI
Exam 16: Monopolistic Competition

Exam 1: Ten Principles of Economics455 Questions
Exam 2: Thinking Like an Economist643 Questions
Exam 3: Interdependence and the Gains From Trade547 Questions
Exam 4: The Market Forces of Supply and Demand693 Questions
Exam 5: Elasticity and Its Application626 Questions
Exam 6: Supply, Demand, and Government Policies668 Questions
Exam 7: Consumers, Producers, and the Efficiency of Markets547 Questions
Exam 8: Applications: the Costs of Taxation509 Questions
Exam 9: Application: International Trade521 Questions
Exam 10: Externalities543 Questions
Exam 11: Public Goods and Common Resources452 Questions
Exam 12: The Design of the Tax System664 Questions
Exam 13: The Costs of Production649 Questions
Exam 14: Firms in Competitive Markets604 Questions
Exam 15: Monopoly662 Questions
Exam 16: Monopolistic Competition649 Questions
Exam 17: Oligopoly522 Questions
Exam 18: The Markets for the Factors of Production592 Questions
Exam 19: Earnings and Discrimination511 Questions
Exam 20: Income Inequality and Poverty478 Questions
Exam 21: The Theory of Consumer Choice570 Questions
Exam 22: Frontiers in Microeconomics461 Questions
Exam 23: Measuring a Nation S Income547 Questions
Exam 24: Measuring the Cost of Living565 Questions
Exam 25: Production and Growth527 Questions
Exam 26: Saving, Investment, and the Financial System637 Questions
Exam 27: Tools of Finance534 Questions
Exam 28: Unemployment and Its Natural Rate701 Questions
Exam 29: The Monetary System540 Questions
Exam 30: Money Growth and Inflation504 Questions
Exam 31: Open-Economy Macroeconomics: Basic Concepts540 Questions
Exam 32: A Macroeconomic Theory of the Open Economy511 Questions
Exam 33: Aggregate Demand and Aggregate Supply572 Questions
Exam 34: The Influence of Monetary and Fiscal Policy on Aggregate Demand523 Questions
Exam 35: The Short-Run Tradeoff Between Inflation and Unemployment536 Questions
Exam 36: Six Debates Over Macroeconomic Policy354 Questions
Select questions type


Table 16-1
The following table shows the percentage of output supplied by the top eight firms in four different industries. 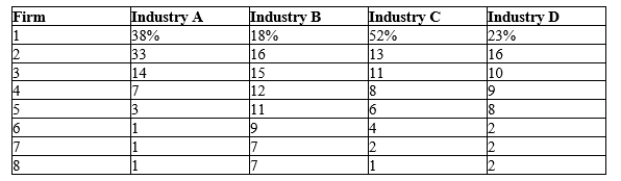 -Refer to Table 16-1. Which industry has the highest concentration ratio?
 (Multiple Choice)
4.8/5  (75)
(75) If advertising reduces a consumer's price sensitivity between identical goods, it is likely to
(Multiple Choice)
4.9/5 (89)
(89) Figure 16-11 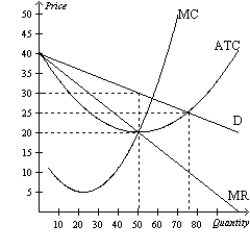 -Refer to Figure 16-11. If this firm profit-maximizes, how much output will it produce?
 (Short Answer)
4.8/5 (77)
(77) Although monopolistically competitive markets offer consumers a wide variety of differentiated products, there may still be insufficient variety if
(Multiple Choice)
4.9/5 (82)
(82) Figure 16-13 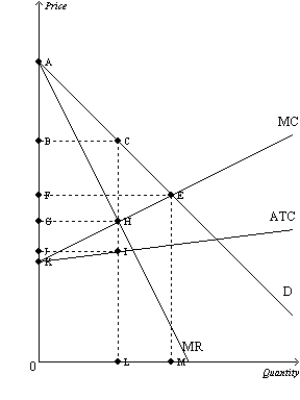 -Refer to Figure 16-13. What is the first step in this industry's adjustment to long run equilibrium?
 (Short Answer)
4.7/5 (78)
(78) Economists who argue that advertising enhances market efficiency suggest that celebrity advertising signals inferior product quality.
(True/False)
4.8/5 (86)
(86) An empirical study compared the price of eyeglasses in states that restricted advertising by optometrists with those that did not.The study revealed:
(Multiple Choice)
4.7/5 (77)
(77) Scenario 16-2
Suppose market demand for a product is given by the equation P = 20 - Q. For this market demand curve, marginal revenue is MR = 20 - 2Q.
-Refer to Scenario 16-2. If the marginal cost of producing this good is 4, what quantity would a profit-maximizing monopolist produce?
(Multiple Choice)
4.8/5 (75)
(75) Entry of new firms in monopolistically competitive industries can convey a negative externality on producers because firms lose customers and profits from the entry of new competitors. This externality is called the
(Short Answer)
4.8/5 (72)
(72) The product-variety externality states that entry of a new firm conveys a negative externality on consumers.
(True/False)
4.8/5 (68)
(68) Consider a monopolistically competitive firm in a market in long-run equilibrium. This firm is likely earning
(Multiple Choice)
4.9/5 (71)
(71) Scenario 16-3
Peter operates an ice cream shop in the center of Fairfield. He sells several unusual flavors of organic, homemade ice cream so he has a monopoly over his own ice cream, though he competes with many other firms selling ice cream in Fairfield for the same customers. Peter's demand and cost values for sales per day are given in the table below. (Everyone who purchases Peter's ice cream buys a double scoop cone because it's so delicious.) 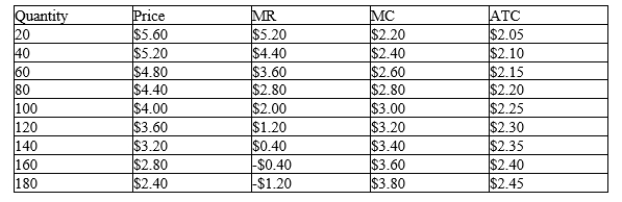 -Refer to Scenario 16-3. Which of the following statements best describes the long run adjustment in this market?
 (Multiple Choice)
4.8/5 (89)
(89) Figure 16-11
-Refer to Figure 16-11. If this firm profit-maximizes, what price will it charge?
-Refer to Figure 16-11. If this firm profit-maximizes, what price will it charge? (Short Answer)
4.8/5 (68)
(68) A recent outbreak of hepatitis was linked to a national fast-food restaurant chain. This is an example of a case in which
(Multiple Choice)
4.8/5 (73)
(73) Figure 16-13 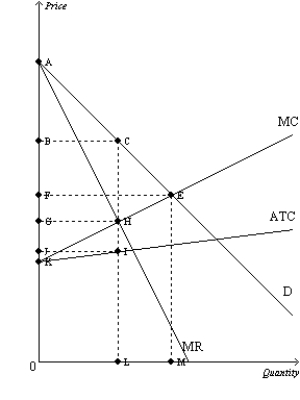 -Refer to Figure 16-13. Which letter represents the profit-maximizing price?
 (Short Answer)
4.9/5 (90)
(90) When a monopolistically competitive firm is in a long-run equilibrium, the values of marginal cost, average total cost, and price are all the same.
(True/False)
4.8/5 (88)
(88) Figure 16-8
The lines in the figures below illustrate the potential effect of entry and exit in a monopolistically competitive market on either the demand curve or the marginal cost curve of existing firms. 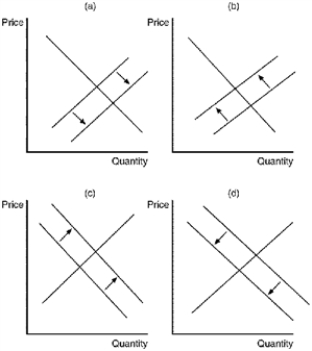 -Refer to Figure 16-8. Which of the diagrams illustrates the impact of some existing firms leaving the market?
 (Multiple Choice)
4.7/5 (74)
(74) Scenario 16-2
Suppose market demand for a product is given by the equation P = 20 - Q. For this market demand curve, marginal revenue is MR = 20 - 2Q.
-Refer to Scenario 16-2. If the marginal cost of producing this good is 4, how much total consumer surplus would consumers receive in this market?
(Multiple Choice)
4.9/5 (76)
(76) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)