



 Chat with AI
Exam 16: Monopolistic Competition

Exam 1: Ten Principles of Economics455 Questions
Exam 2: Thinking Like an Economist645 Questions
Exam 3: Interdependence and the Gains From Trade550 Questions
Exam 4: The Market Forces of Supply and Demand693 Questions
Exam 5: Elasticity and Its Application625 Questions
Exam 6: Supply, Demand, and Government Policies671 Questions
Exam 7: Consumers, Producers, and the Efficiency of Markets547 Questions
Exam 8: Application: The Costs of Taxation507 Questions
Exam 9: Application: International Trade521 Questions
Exam 10: Externalities543 Questions
Exam 11: Public Goods and Common Resources453 Questions
Exam 12: The Design of the Tax System563 Questions
Exam 13: The Costs of Production649 Questions
Exam 14: Firms in Competitive Markets608 Questions
Exam 15: Monopoly662 Questions
Exam 16: Monopolistic Competition649 Questions
Exam 17: Oligopoly522 Questions
Exam 18: The Markets for the Factors of Production592 Questions
Exam 19: Earnings and Discrimination511 Questions
Exam 20: Income Inequality and Poverty478 Questions
Exam 21: The Theory of Consumer Choice568 Questions
Exam 22: Frontiers in Microeconomics461 Questions
Select questions type


A market structure in which there are many firms selling products that are similar but not identical is known as
(Multiple Choice)
4.8/5  (92)
(92) Which of the following is an example of a monopolistically competitive industry?
(Multiple Choice)
4.9/5 (87)
(87) Which type of market structure has the fewest number of firms?
(Short Answer)
4.8/5 (78)
(78) Considering perfect competition, monopolistic competition, and monopoly, which of the market structures features entry in the long run?
(Essay)
4.7/5 (91)
(91) A monopolistically competitive firm faces the following demand curve for its product:  The firm has total fixed costs of $100 and a constant marginal cost of $25 per unit. The firm will maximize profit with the production of
 (Multiple Choice)
4.8/5 (81)
(81) In a market that is characterized by imperfect competition,
(Multiple Choice)
4.8/5 (71)
(71) If a monopolistically competitive firm can increase its level of production and lower its average total cost of production at the same time then
(Multiple Choice)
4.8/5 (80)
(80) Monopolistically competitive firms could reduce the average total cost of producing by increasing output; therefore, these firms have
(Short Answer)
4.9/5 (84)
(84) In the long run, a monopolistically competitive firm produces at efficient scale.
(True/False)
4.9/5 (81)
(81) Entry of new firms in monopolistically competitive industries can convey a positive externality on consumers because new products result in more consumer surplus. This externality is called the
(Short Answer)
4.9/5 (81)
(81) In a long-run equilibrium, both perfectly competitive markets and monopolistically competitive markets have price equal to average total cost.
(True/False)
5.0/5 (77)
(77) According to the signaling theory of advertising, consumers
(Multiple Choice)
4.9/5 (77)
(77) Use a graph to demonstrate why a profit-maximizing monopolistically competitive firm must operate at excess capacity. Explain why a perfectly competitive firm is not subject to the same constraint.
(Essay)
4.8/5 (79)
(79) If we observe a great deal of advertising of men's shaving products, we can infer that
(Multiple Choice)
4.9/5 (65)
(65) Table 16-7
A monopolistically competitive firm faces the following demand schedule for its product. In addition, the firm has total fixed costs equal to 20.  -Refer to Table 16-7. When this firm profit maximizes and faces a constant marginal cost of $7, what is the amount of its markup over marginal cost?
 (Short Answer)
4.9/5 (86)
(86) Figure 16-10
The figure is drawn for a monopolistically-competitive firm. 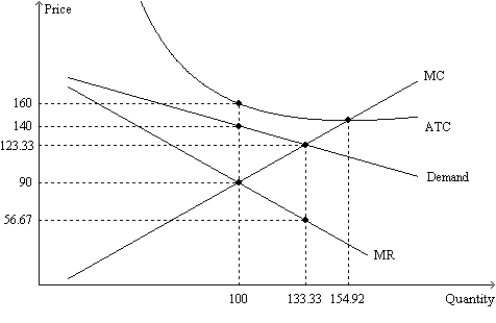 -Refer to Figure 16-10. In order to maximize its profit, the firm will choose to produce
 (Multiple Choice)
4.8/5 (81)
(81) Table 16-6
Beatrice's Birthday Cakes is one bakery among many in the market for birthday cakes. The following table presents cost and revenue data for birthday cakes at Beatrice's. 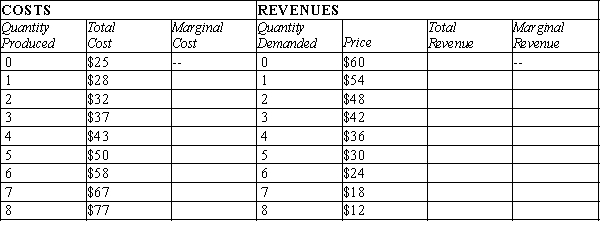 -Refer to Table 16-6. If the government forced Beatrice's to produce at the efficient scale of output, what is the maximum profit Beatrice's could earn?
 (Multiple Choice)
4.9/5 (96)
(96) Figure 16-13 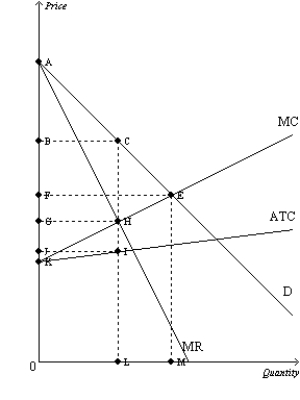 -Refer to Figure 16-13. What is the first step in this industry's adjustment to long run equilibrium?
 (Short Answer)
4.9/5 (82)
(82) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)