



 Chat with AI
Exam 14: Monopoly and Monopolistic Competition

Exam 1: Economics and Economic Reasoning158 Questions
Exam 2: The Production Possibility Model, Trade, and Globalization133 Questions
Exam 3: Economic Institutions163 Questions
Exam 4: Supply and Demand182 Questions
Exam 5: Using Supply and Demand163 Questions
Exam 6: Describing Supply and Demand: Elasticities216 Questions
Exam 7: Taxation and Government Intervention201 Questions
Exam 8: Market Failure Versus Government Failure197 Questions
Exam 9: Comparative Advantage, Exchange Rates, and Globalization118 Questions
Exam 10: International Trade Policy99 Questions
Exam 11: Production and Cost Analysis I194 Questions
Exam 12: Production and Cost Analysis II152 Questions
Exam 13: Perfect Competition170 Questions
Exam 14: Monopoly and Monopolistic Competition274 Questions
Exam 15: Oligopoly and Antitrust Policy142 Questions
Exam 16: Real-World Competition and Technology108 Questions
Exam 17: Work and the Labor Market150 Questions
Exam 18: Who Gets What the Distribution of Income131 Questions
Exam 19: The Logic of Individual Choice: the Foundation of Supply and Demand170 Questions
Exam 20: Game Theory, Strategic Decision Making, and Behavioral Economics103 Questions
Exam 21: Thinking Like a Modern Economist97 Questions
Exam 22: Behavioral Economics and Modern Economic Policy126 Questions
Exam 23: Microeconomic Policy, Economic Reasoning, and Beyond134 Questions
Exam 24: Economic Growth, Business Cycles, and Unemployment124 Questions
Exam 25: Measuring and Describing the Aggregate Economy229 Questions
Exam 26: The Keynesian Short-Run Policy Model: Demand-Side Policies220 Questions
Exam 27: The Classical Long-Run Policy Model: Growth and Supply-Side Policies133 Questions
Exam 28: The Financial Sector and the Economy214 Questions
Exam 29: Monetary Policy243 Questions
Exam 30: Financial Crises, Panics, and Unconventional Monetary Policy109 Questions
Exam 31: Deficits and Debt: the Austerity Debate150 Questions
Exam 32: The Fiscal Policy Dilemma119 Questions
Exam 33: Jobs and Unemployment78 Questions
Exam 34: Inflation, Deflation, and Macro Policy175 Questions
Exam 35: International Financial Policy211 Questions
Exam 36: Macro Policy in a Global Setting134 Questions
Exam 37: Structural Stagnation and Globalization125 Questions
Exam 38: Macro Policy in Developing Countries142 Questions
Select questions type


Consider the following diagram: 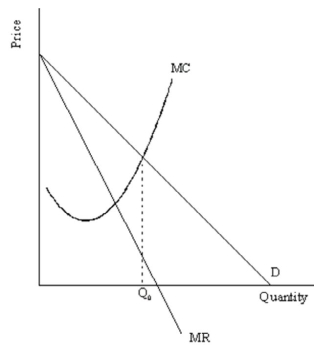 Explain why producing output level Q0 is not the monopolist's profit-maximizing output level.How much output should the firm produce? Illustrate as Q1 in the diagram below.
 (Essay)
4.8/5  (75)
(75) Refer to the graph shown. If this graph represents a monopoly market, the equilibrium price and quantity will be: 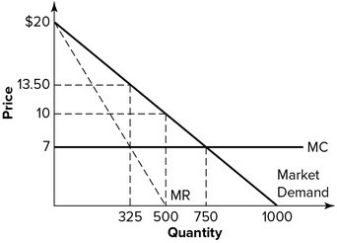
(Multiple Choice)
4.8/5 (70)
(70) Refer to the graph shown of a monopolistically competitive firm. In the long run: 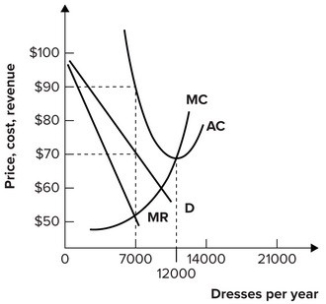
(Multiple Choice)
4.8/5 (82)
(82) Demonstrate graphically and explain verbally the case of a monopolistically competitive firm earning a positive economic profit.Is this firm in a short run or a long-run equilibrium? In the short run,how does this case differ from the monopoly market outcome?
(Essay)
4.9/5 (75)
(75) Refer to the graph shown depicting a monopolistically competitive firm. The average total cost curve is represented by curve: 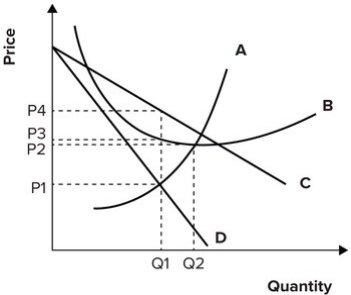
(Multiple Choice)
4.9/5 (63)
(63) Briefly discuss three possible barriers to entry for an industry and assess whether these barriers are good or bad for consumers or society as a whole.
(Essay)
4.8/5 (82)
(82) Refer to the graph shown. If regulators wanted this monopolist to earn only a normal profit, they would set price equal to: 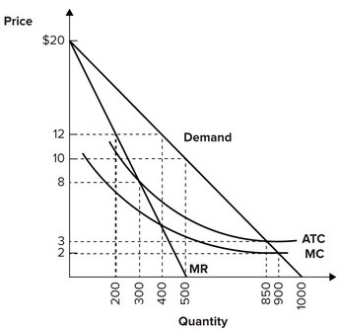
(Multiple Choice)
4.8/5 (95)
(95) Under normal monopoly, price exceeds marginal cost, which implies that the:
(Multiple Choice)
4.8/5 (62)
(62) Refer to the table shown, which shows the demand schedule for a product sold by a monopolist. Marginal revenue is closest to zero:
(Multiple Choice)
5.0/5 (82)
(82) Charging different prices to different individuals or groups for the same product is called:
(Multiple Choice)
4.8/5 (74)
(74) Refer to the graph shown of average costs for a typical firm. The lowest per-unit costs for the industry could be achieved if: 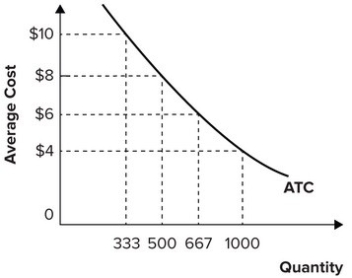
(Multiple Choice)
4.9/5 (79)
(79) 
(a)Complete the following table: P Q TR MR \ 10 1 9 2 8 3 7 4 6 5 5 6 4 7 3 8 2 9 1 10 Note: Marginal values are values between levels of output.
(b)Suppose the firm's variable costs are as given in the accompanying table.What is the firm's profit-maximizing level of output? Q VC 1 5 2 9 3 12 4 16 5 21 6 27 7 34 8 42 9 51 10 61 (c)What would the profit-maximizing output be if the government offered to pay the firm's variable costs of production?
(d)What would profit-maximizing output be if instead the government decided to levy a tax of $100 on the firm,independent of its output decision?
(e)Do we know whether the firm will exit the industry in the short run? How about in the long run? Why or why not?
(Essay)
4.8/5 (57)
(57) The best-selling mystery To the Nines by Janet Evanovich was sold in hardcover for $25.95 when it was released. One year later, the publisher issued a softcover edition for $7.99. If the marginal cost of printing a softcover book is not much less than the marginal cost of printing a hardcover, the pricing difference:
(Multiple Choice)
4.7/5 (73)
(73) If P = 3Qs + 3 represents market supply for a competitive industry and market demand is given by Qd = 31 - 1/3 P, the equilibrium price is:
(Multiple Choice)
4.9/5 (67)
(67) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)