



 Chat with AI
Exam 7: Taxation and Government Intervention

Exam 1: Economics and Economic Reasoning158 Questions
Exam 2: The Production Possibility Model, Trade, and Globalization133 Questions
Exam 3: Economic Institutions163 Questions
Exam 4: Supply and Demand182 Questions
Exam 5: Using Supply and Demand163 Questions
Exam 6: Describing Supply and Demand: Elasticities216 Questions
Exam 7: Taxation and Government Intervention201 Questions
Exam 8: Market Failure Versus Government Failure197 Questions
Exam 9: Comparative Advantage, Exchange Rates, and Globalization118 Questions
Exam 10: International Trade Policy99 Questions
Exam 11: Production and Cost Analysis I194 Questions
Exam 12: Production and Cost Analysis II152 Questions
Exam 13: Perfect Competition170 Questions
Exam 14: Monopoly and Monopolistic Competition274 Questions
Exam 15: Oligopoly and Antitrust Policy142 Questions
Exam 16: Real-World Competition and Technology108 Questions
Exam 17: Work and the Labor Market150 Questions
Exam 18: Who Gets What the Distribution of Income131 Questions
Exam 19: The Logic of Individual Choice: the Foundation of Supply and Demand170 Questions
Exam 20: Game Theory, Strategic Decision Making, and Behavioral Economics103 Questions
Exam 21: Thinking Like a Modern Economist97 Questions
Exam 22: Behavioral Economics and Modern Economic Policy126 Questions
Exam 23: Microeconomic Policy, Economic Reasoning, and Beyond134 Questions
Exam 24: Economic Growth, Business Cycles, and Unemployment124 Questions
Exam 25: Measuring and Describing the Aggregate Economy229 Questions
Exam 26: The Keynesian Short-Run Policy Model: Demand-Side Policies220 Questions
Exam 27: The Classical Long-Run Policy Model: Growth and Supply-Side Policies133 Questions
Exam 28: The Financial Sector and the Economy214 Questions
Exam 29: Monetary Policy243 Questions
Exam 30: Financial Crises, Panics, and Unconventional Monetary Policy109 Questions
Exam 31: Deficits and Debt: the Austerity Debate150 Questions
Exam 32: The Fiscal Policy Dilemma119 Questions
Exam 33: Jobs and Unemployment78 Questions
Exam 34: Inflation, Deflation, and Macro Policy175 Questions
Exam 35: International Financial Policy211 Questions
Exam 36: Macro Policy in a Global Setting134 Questions
Exam 37: Structural Stagnation and Globalization125 Questions
Exam 38: Macro Policy in Developing Countries142 Questions
Select questions type


The distance between the demand curve and the price the consumer has to pay for a product (given quantity demanded)is referred to as:

Free
(Multiple Choice)
5.0/5  (94)
(94) Correct Answer: Verified
C
Refer to the graph shown. Assume the market is initially in equilibrium at point j in the graph but the imposition of a per-unit tax on this product shifts the supply curve up from S0 to S1. The effect of the tax is to raise equilibrium price from: 
Free
(Multiple Choice)
4.9/5 (83)
(83) Correct Answer:Verified
VerifiedB
Demonstrate graphically and explain verbally the cost to society of a tax of t per carton imposed on the sellers of cigarettes.
Free
(Essay)
4.9/5 (83)
(83) Correct Answer:Verified
VerifiedImposing a tax will result in an upward shift of the supply curve from S0 to S1 in the diagram.The cost to society is represented by the loss of consumer and producer surplus that is not transferred to the government in the form of tax revenue.This deadweight loss is the area C + E in the diagram.Consumer surplus decreases from A + B + C to A and that producer surplus decreases from D + E + F to F.Areas B and D are collected as government revenue and are assumed to benefit society. 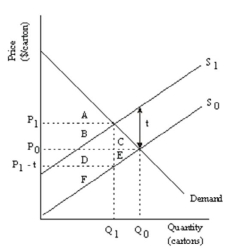
The problems created by price controls become greatest as time goes by when:
(Multiple Choice)
4.9/5 (80)
(80) If price is lowered by law from the market equilibrium value of $5 to a lower value of $4:
(Multiple Choice)
4.7/5 (76)
(76) Refer to the graph shown. With an effective price floor at $8, the effect is an implicit tax on: 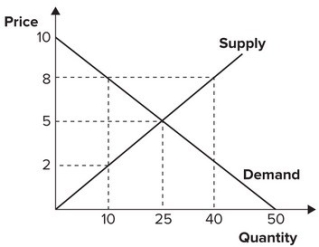
(Multiple Choice)
4.8/5 (82)
(82) Refer to the graph shown. When the market is in equilibrium, consumer surplus is area: 
(Multiple Choice)
4.9/5 (85)
(85) Refer to the graph shown. Assume the market is initially in equilibrium at point j in the graph but the imposition of a per-unit tax on this product shifts the supply curve up from S0 to S1. The lost producer surplus of this tax is equal to the area: 
(Multiple Choice)
4.7/5 (82)
(82) Refer to the graph shown. If the price of this product fell from $5.00 to $2.50 (because of a price ceiling or a shift in demand), producer surplus would fall from: 
(Multiple Choice)
4.8/5 (77)
(77) If the minimum that the Smith family would be willing to sell their house for is $185,000, but they in fact sell it for $210,000, they will receive:
(Multiple Choice)
4.9/5 (78)
(78) Refer to the following graph. 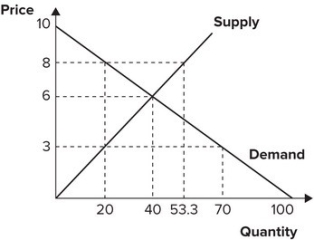 With an effective price ceiling at $3, the effect is an implicit tax on:
 (Multiple Choice)
4.9/5 (70)
(70) Demonstrate graphically and explain verbally how the problem of price controls differs in the short-run and the long run.
(Essay)
4.8/5 (73)
(73) Refer to the graph shown. With an effective price ceiling at Pc, the effect is an implicit tax on: 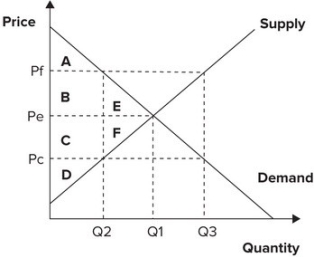
(Multiple Choice)
4.9/5 (85)
(85) Refer to the graph shown. An effective price floor at Pf imposes a deadweight loss shown by: 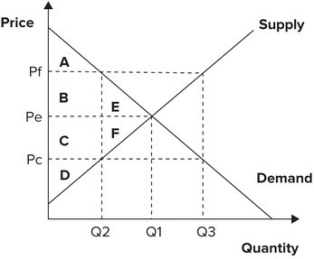
(Multiple Choice)
4.8/5 (75)
(75) Those with more inelastic demands will bear a larger burden of a tax because they:
(Multiple Choice)
4.7/5 (83)
(83) Suppose people freely choose to spend 40 percent of their income on healthcare, but then the government decides to tax 40 of a person's income to provide the same level of coverage as before. What can be said about deadweight loss in each case?
(Multiple Choice)
4.8/5 (84)
(84) Demonstrate graphically and explain verbally that the buyers bear the entire burden of a tax when demand is perfectly inelastic.
(Essay)
4.8/5 (78)
(78) What is the deadweight loss of taxation? What causes deadweight loss?
(Essay)
4.9/5 (66)
(66) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)