



 Chat with AI
Exam 13: Perfect Competition


Perfectly competitive firms are price takers.However,in the real world,it is rare that the customer goes into any business establishment and tells the seller what price he is willing to pay.Since buyers don't dictate price,where does price come from in perfectly competitive markets?

 (88)
 Verified
Price making behavior does not occur in a perfectly competitive market.All producers sell an identical product,the number of firms is large,and there is complete information.Hence,it will simply be impossible for any seller to extract a price greater than the market price;there will be no incentive for any seller to offer their product/service at any price lower than the market price because profits are maximized where price equals marginal revenue equals marginal cost.
Demonstrate graphically and explain verbally the case of a constant-cost industry in a perfectly competitive market.Draw both a firm and a market diagram.HINT: The long-run market supply curve in your diagram should be perfectly elastic (i.e. ,horizontal).
(65) VerifiedThe initial equilibrium is point A (in both the market and firm diagrams),with a price of P0,a market quantity exchanged of Q0 and all firms producing an output level of q0.Suppose there is an increase in demand from D0 to D1;this will impact both the market and firm diagrams.In the market diagram the equilibrium changes from point A to point B.At point B the price increases to P1 > P0 and the quantity exchanged also increases (to Q1 > Q0).The increase in market price results in a shift up of the demand curve facing the firms (from P0 = d0 to P1 = d1).The firms will increase production to the level where P1 intersects MC (point B in the firm diagram);firms will now produce q0 > q0.Points B in the diagrams do not represent a long-run equilibrium since at point B in the firm diagram firms are making a positive economic profit (since P1 > AC at q1).This will entice new firms into the industry,resulting in an increase in the short-run market supply curve from S0 to S1 and moving us to a new equilibrium point C in the market diagram with a market quantity exchanged of Q2 > Q1 and a price of P0.The increase in market quantity from Q0 to Q1 to Q2 does not impact factor prices (since we are examining a constant-cost industry)and thus firm cost curves do not change.As a result the return to the original price level P0 brings firms back to their original point A.Point C in the market diagram is a second long-run equilibrium situation because it corresponds to point A in the firm diagram where the firms are not earning any economic profit.Drawing a line connecting the two long-run equilibrium points in the market diagram (points A and C)gives us the long-run market supply curve (SLR in the diagram above).We can see that it is perfectly elastic,indicating a constant-cost industry. 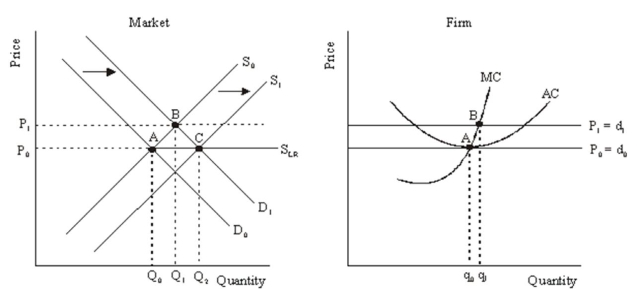
For a perfectly competitive firm, the profit-maximizing output level occurs where marginal cost equals price.
(81) VerifiedTrue
Suppose that the current equilibrium price of silver is $20 per ounce. If silver is produced under conditions of perfect competition and the industry is in long-run equilibrium, the average total cost of producing silver:
(76) Refer to the graph shown. The marginal cost of producing the 60th unit is: 
(94) Explain how the long-run market supply curve for a perfectly competitive industry depends upon factor prices.How would this apply to the milk producing industry?
(71) Refer to the graph shown. If the firm is producing 450 units of output, profit is equal to: 
(81) The marginal cost curve is a competitive firm's supply curve; it shows how many units of output a firm will be willing to sell at different prices.
(79) The demand for clothing increases. As a result, the price of clothing increases above the minimum average cost of producing it. In the long run, if the clothing industry is perfectly competitive and is a constant-cost industry:
(93) Demonstrate graphically and explain verbally how a demand curve facing a perfectly competitive firm relates to the market demand curve.
(83) The long-run industry supply curve will be upward-sloping if:
(74) Refer to the following graph. 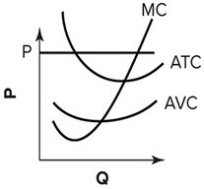 The perfectly competitive firm depicted is currently:
 (75) Refer to the following graph. 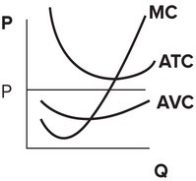 The perfectly competitive firm depicted is currently:
 (65) Refer to the graph shown. To maximize profit, this firm should produce: 
(79) Refer to the graph shown. If this perfectly competitive firm is producing 120 units of output, the market price is equal to: 
(76) Refer to the graph shown. If the market price is P4, the maximum profit the firm can earn is: 
(72) Suppose a perfectly competitive firm can increase its profits by increasing its output. Then it must be true that the firm's:
(74) To maximize profits, a perfectly competitive firm should produce until:
(83) Explain,using an example if necessary to be clear,why the minimum point on the average variable cost curve is the shutdown point.In other words,why is a competitive firm's supply curve that portion of the marginal cost curve that lies above the minimum average variable cost?
(66) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)