



 Chat with AI
Exam 13: Perfect Competition

Exam 1: Economics and Economic Reasoning158 Questions
Exam 2: The Production Possibility Model, Trade, and Globalization133 Questions
Exam 3: Economic Institutions163 Questions
Exam 4: Supply and Demand182 Questions
Exam 5: Using Supply and Demand163 Questions
Exam 6: Describing Supply and Demand: Elasticities216 Questions
Exam 7: Taxation and Government Intervention201 Questions
Exam 8: Market Failure Versus Government Failure197 Questions
Exam 9: Comparative Advantage, Exchange Rates, and Globalization118 Questions
Exam 10: International Trade Policy99 Questions
Exam 11: Production and Cost Analysis I194 Questions
Exam 12: Production and Cost Analysis II152 Questions
Exam 13: Perfect Competition170 Questions
Exam 14: Monopoly and Monopolistic Competition274 Questions
Exam 15: Oligopoly and Antitrust Policy142 Questions
Exam 16: Real-World Competition and Technology108 Questions
Exam 17: Work and the Labor Market150 Questions
Exam 18: Who Gets What the Distribution of Income131 Questions
Exam 19: The Logic of Individual Choice: the Foundation of Supply and Demand170 Questions
Exam 20: Game Theory, Strategic Decision Making, and Behavioral Economics103 Questions
Exam 21: Thinking Like a Modern Economist97 Questions
Exam 22: Behavioral Economics and Modern Economic Policy126 Questions
Exam 23: Microeconomic Policy, Economic Reasoning, and Beyond134 Questions
Exam 24: Economic Growth, Business Cycles, and Unemployment124 Questions
Exam 25: Measuring and Describing the Aggregate Economy229 Questions
Exam 26: The Keynesian Short-Run Policy Model: Demand-Side Policies220 Questions
Exam 27: The Classical Long-Run Policy Model: Growth and Supply-Side Policies133 Questions
Exam 28: The Financial Sector and the Economy214 Questions
Exam 29: Monetary Policy243 Questions
Exam 30: Financial Crises, Panics, and Unconventional Monetary Policy109 Questions
Exam 31: Deficits and Debt: the Austerity Debate150 Questions
Exam 32: The Fiscal Policy Dilemma119 Questions
Exam 33: Jobs and Unemployment78 Questions
Exam 34: Inflation, Deflation, and Macro Policy175 Questions
Exam 35: International Financial Policy211 Questions
Exam 36: Macro Policy in a Global Setting134 Questions
Exam 37: Structural Stagnation and Globalization125 Questions
Exam 38: Macro Policy in Developing Countries142 Questions
Select questions type


In a perfectly competitive market, a decrease in market demand in a long-run constant-cost industry causes:
(Multiple Choice)
4.7/5  (70)
(70) Refer to the graph shown. If the market price is P4, the firm will produce: 
(Multiple Choice)
4.9/5 (73)
(73) Many fast-food restaurants have begun offering value meals with fruit or salad instead of French fries. If consumers find this idea attractive, the market demand for potatoes will most likely:
(Multiple Choice)
4.8/5 (90)
(90) A perfectly competitive firm will be profitable if price at the profit-maximizing quantity is above:
(Multiple Choice)
4.7/5 (82)
(82) Firms know that when they enter a profitable industry,profits will eventually be eliminated by competition.Why would a firm want to enter such an industry?
(Essay)
4.8/5 (68)
(68) In a perfectly competitive market, market prices are determined by:
(Multiple Choice)
4.8/5 (72)
(72) Which of the necessary conditions for perfect competition are least likely to be satisfied in the real world? Explain your selections.
(Essay)
4.8/5 (73)
(73) In a perfectly competitive market, many firms produce many different varieties of the same product.
(True/False)
4.7/5 (86)
(86) A perfectly competitive firm facing a price of $10 decides to produce 100 units. If its marginal cost of producing the last unit is $12 and it is seeking to maximize profit, the firm should:
(Multiple Choice)
4.8/5 (92)
(92) Refer to the graphs shown, which depict a perfectly competitive market and firm. If market demand increases from D0 to D1, in the short run: 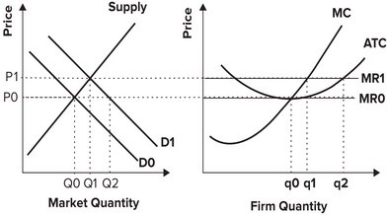
(Multiple Choice)
4.8/5 (95)
(95) An assumption of a competitive market is that both buyers and sellers are price takers. When we go to the mall to shop for clothing or to the grocery to buy food, what do we usually observe?
(Multiple Choice)
4.8/5 (75)
(75) Refer to the table shown. If the market price is $6, a perfectly competitive profit-maximizing firm will produce: Quantity Marginal Cast 1 \ 3 2 5 3 7 4 9
(Multiple Choice)
5.0/5 (78)
(78) In the wake of the 2008 recession, the electronics retailer Circuit City closed its stores. If we assume this was a short-run decision, the most likely explanation for it is that the price of a typical product sold at Circuit City stores was:
(Multiple Choice)
4.9/5 (73)
(73) Refer to the graph shown. If the firm increases output from 30 to 40, total revenue will increase: 
(Multiple Choice)
4.9/5 (76)
(76) Using a supply and demand and a typical firm diagram,illustrate the impact of a flood on the market for contractors once the flood has receded.NOTE: Assume the market was perfectly competitive and in a long-run equilibrium position before the flood.Also assume that construction is a constant-cost industry.
(Essay)
5.0/5 (84)
(84) Refer to the graphs shown, which depict a perfectly competitive market and firm. If market demand decreases from D0 to D1: 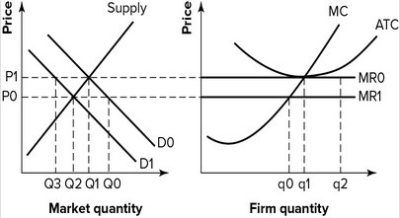
(Multiple Choice)
4.8/5 (75)
(75) Suppose that the marginal cost of producing cottonseed meal is $170 per ton. If the cottonseed oil industry is perfectly competitive and in long-run equilibrium, the average total cost of producing cottonseed oil:
(Multiple Choice)
4.9/5 (76)
(76) Refer to the graph shown. If market price increases from $5.00 per unit to $6.00 per unit, a profit-maximizing perfectly competitive firm will: 
(Multiple Choice)
4.8/5 (71)
(71) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)