



 Chat with AI
Exam 4: Supply and Demand

Exam 1: Economics and Economic Reasoning158 Questions
Exam 2: The Production Possibility Model, Trade, and Globalization133 Questions
Exam 3: Economic Institutions163 Questions
Exam 4: Supply and Demand182 Questions
Exam 5: Using Supply and Demand163 Questions
Exam 6: Describing Supply and Demand: Elasticities216 Questions
Exam 7: Taxation and Government Intervention201 Questions
Exam 8: Market Failure Versus Government Failure197 Questions
Exam 9: Comparative Advantage, Exchange Rates, and Globalization118 Questions
Exam 10: International Trade Policy99 Questions
Exam 11: Production and Cost Analysis I194 Questions
Exam 12: Production and Cost Analysis II152 Questions
Exam 13: Perfect Competition170 Questions
Exam 14: Monopoly and Monopolistic Competition274 Questions
Exam 15: Oligopoly and Antitrust Policy142 Questions
Exam 16: Real-World Competition and Technology108 Questions
Exam 17: Work and the Labor Market150 Questions
Exam 18: Who Gets What the Distribution of Income131 Questions
Exam 19: The Logic of Individual Choice: the Foundation of Supply and Demand170 Questions
Exam 20: Game Theory, Strategic Decision Making, and Behavioral Economics103 Questions
Exam 21: Thinking Like a Modern Economist97 Questions
Exam 22: Behavioral Economics and Modern Economic Policy126 Questions
Exam 23: Microeconomic Policy, Economic Reasoning, and Beyond134 Questions
Exam 24: Economic Growth, Business Cycles, and Unemployment124 Questions
Exam 25: Measuring and Describing the Aggregate Economy229 Questions
Exam 26: The Keynesian Short-Run Policy Model: Demand-Side Policies220 Questions
Exam 27: The Classical Long-Run Policy Model: Growth and Supply-Side Policies133 Questions
Exam 28: The Financial Sector and the Economy214 Questions
Exam 29: Monetary Policy243 Questions
Exam 30: Financial Crises, Panics, and Unconventional Monetary Policy109 Questions
Exam 31: Deficits and Debt: the Austerity Debate150 Questions
Exam 32: The Fiscal Policy Dilemma119 Questions
Exam 33: Jobs and Unemployment78 Questions
Exam 34: Inflation, Deflation, and Macro Policy175 Questions
Exam 35: International Financial Policy211 Questions
Exam 36: Macro Policy in a Global Setting134 Questions
Exam 37: Structural Stagnation and Globalization125 Questions
Exam 38: Macro Policy in Developing Countries142 Questions
Select questions type


Refer to the graphs shown. An increase in quantity demanded is best shown by which arrow? 


Free
(Multiple Choice)
4.8/5  (88)
(88) Correct Answer: Verified
A
The table below shows the quantity demanded and quantity supplied of DVDs at each price level. Price (dollars) Quantity Demanded Quantity Supplied Surplus (+) Shortage (-) 20.00 10 500 18.00 25 400 16.00 45 250 14.00 80 200 12.00 140 140 10.00 200 80 8.00 300 40 6.00 450 5 (a)Fill out the column entitled Surplus/Shortage.
(b)What are the equilibrium price and equilibrium quantity in this market?
(c)Suppose that consumers' taste changed in favor of DVDs due to their high quality.What happens at the original equilibrium price level calculated in Part (b)?
(d)Suppose that advances in technology reduced the production cost of DVD players.What happens at the original equilibrium price level calculated in Part (b)?
Free
(Essay)
4.7/5 (69)
(69) Correct Answer:Verified
Verified (a) (b)Equilibrium occurs when quantity demanded equals quantity supplied,i.e. ,when there are no shortages or surpluses in the market.This point is at a price of $12.00 per DVD and a quantity of 140 DVDs.
(c)The demand for DVDs will increase at each price level.Therefore,at $12.00 per unit,the quantity demanded will be greater than the quantity supplied (140 DVDs).A shortage will appear in the market.
(d)A decrease in the production cost of DVD players increases their supply.The equilibrium price of DVD players decreases,and consumers purchase more of them.Since DVD players and DVDs are complementary goods,the demand for DVDs will shift to the right.At a price of $12.00 per DVD,there will be a shortage of DVDs in the market.
Which of the following is not held constant as you move along the demand curve?
Free
(Multiple Choice)
4.8/5 (71)
(71) Correct Answer:Verified
VerifiedA
Consider the following supply and demand diagram for Tootsie Rolls.Note that the market is currently in equilibrium,with a price of P* and a quantity exchanged of Q*. 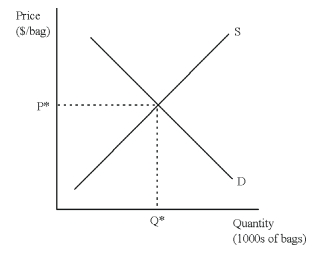 For each of the scenarios below,draw a picture that illustrates the impact on price and quantity exchanged.Explain each of your pictures by describing what is happening to the demand side of the market.
(a)The American Association of Chocolate Lovers designates the Tootsie Roll as its official candy.
(b)The Tootsie Roll Company computerizes their Tootsie Roll manufacturing plant,lowering unit costs of production.
For each of the scenarios below,draw a picture that illustrates the impact on price and quantity exchanged.Explain each of your pictures by describing what is happening to the demand side of the market.
(a)The American Association of Chocolate Lovers designates the Tootsie Roll as its official candy.
(b)The Tootsie Roll Company computerizes their Tootsie Roll manufacturing plant,lowering unit costs of production. (Essay)
4.9/5 (79)
(79) A decrease in the number of consumers in a market causes market demand to:
(Multiple Choice)
4.8/5 (89)
(89) The following graph shows the supply of movie downloads. If price changes from $4.00 to $2.00 then: 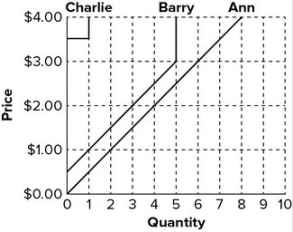
(Multiple Choice)
4.8/5 (89)
(89) Which of the following is not likely to change the supply of laptops?
(Multiple Choice)
4.8/5 (84)
(84) Given the graph shown, the quantity that would be associated with the price of $4 in a supply table would be: 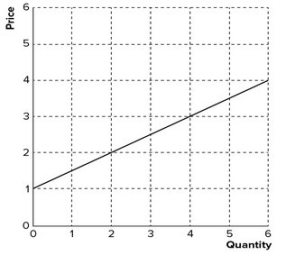
(Multiple Choice)
4.9/5 (84)
(84) Refer to the graphs shown. The effect of an increase in price on demand is best shown by which arrow? 

(Multiple Choice)
4.9/5 (82)
(82) If cigar prices tripled while sales of cigars rose 30 percent, this would likely be due to a shift in demand.
(True/False)
4.9/5 (74)
(74) What is meant by "the fallacy of composition"? Because of the fallacy of composition,it is not possible to apply the microeconomic analysis of individual firms and consumers directly to the macroeconomic analysis of entire nations.Explain why this is so.
(Essay)
4.8/5 (82)
(82) Refer to the graphs shown. The market is fat-free potato chips that contain the fat substitute olestra. Which graph best represents the impact of increased consumer concern about the effects of olestra on long-term health? 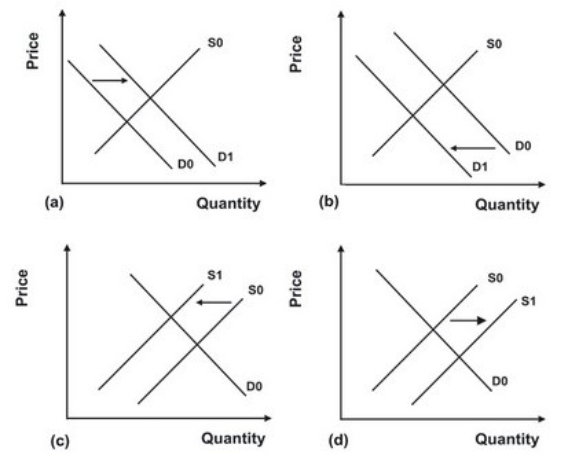
(Multiple Choice)
4.9/5 (80)
(80) How would a decline in demand for imported commodities by the Chinese affect the market for cargo transportation to China?
(Multiple Choice)
4.8/5 (82)
(82) For which of the following markets would the fallacy of composition least likely apply?
(Multiple Choice)
4.8/5 (72)
(72) Which of the following would best explain a decrease in the supply of squash?
(Multiple Choice)
4.8/5 (71)
(71) According to the law of demand an increase in the price of gasoline will:
(Multiple Choice)
4.9/5 (62)
(62) The law of supply states that, other things equal, as the price of a good goes:
(Multiple Choice)
4.8/5 (74)
(74) In one year,the price of soybeans was $3.50 a bushel,and the Jones family farm planted 7,500 acres of them.In the following year,although the price of soybeans fell to $3.25 a bushel,the Jones family farm planted 8,200 acres of them.Use the concepts of a shift in the supply curve versus a movement along the supply curve to explain why this increase in soybean acreage does not represent a violation of the law of supply.
(Essay)
4.8/5 (78)
(78) Refer to the graphs shown. The consequences of improved technology combined with an increase in the number of consumers can best be illustrated by: 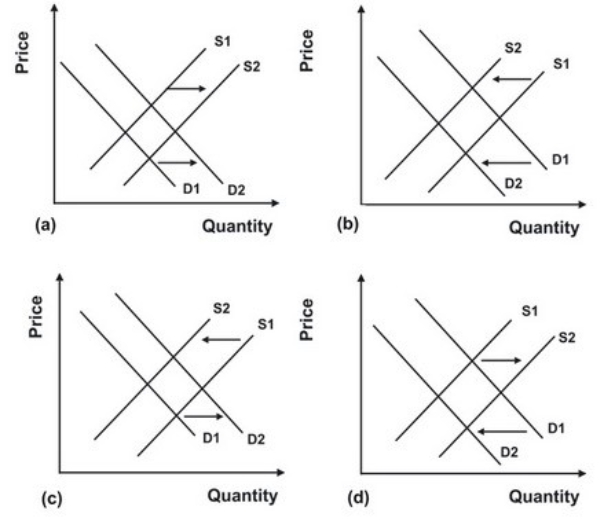
(Multiple Choice)
4.8/5 (74)
(74) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)