



 Chat with AI
Exam 4: Supply and Demand

Exam 1: Economics and Economic Reasoning158 Questions
Exam 2: The Production Possibility Model, Trade, and Globalization133 Questions
Exam 3: Economic Institutions163 Questions
Exam 4: Supply and Demand182 Questions
Exam 5: Using Supply and Demand163 Questions
Exam 6: Describing Supply and Demand: Elasticities216 Questions
Exam 7: Taxation and Government Intervention201 Questions
Exam 8: Market Failure Versus Government Failure197 Questions
Exam 9: Comparative Advantage, Exchange Rates, and Globalization118 Questions
Exam 10: International Trade Policy99 Questions
Exam 11: Production and Cost Analysis I194 Questions
Exam 12: Production and Cost Analysis II152 Questions
Exam 13: Perfect Competition170 Questions
Exam 14: Monopoly and Monopolistic Competition274 Questions
Exam 15: Oligopoly and Antitrust Policy142 Questions
Exam 16: Real-World Competition and Technology108 Questions
Exam 17: Work and the Labor Market150 Questions
Exam 18: Who Gets What the Distribution of Income131 Questions
Exam 19: The Logic of Individual Choice: the Foundation of Supply and Demand170 Questions
Exam 20: Game Theory, Strategic Decision Making, and Behavioral Economics103 Questions
Exam 21: Thinking Like a Modern Economist97 Questions
Exam 22: Behavioral Economics and Modern Economic Policy126 Questions
Exam 23: Microeconomic Policy, Economic Reasoning, and Beyond134 Questions
Exam 24: Economic Growth, Business Cycles, and Unemployment124 Questions
Exam 25: Measuring and Describing the Aggregate Economy229 Questions
Exam 26: The Keynesian Short-Run Policy Model: Demand-Side Policies220 Questions
Exam 27: The Classical Long-Run Policy Model: Growth and Supply-Side Policies133 Questions
Exam 28: The Financial Sector and the Economy214 Questions
Exam 29: Monetary Policy243 Questions
Exam 30: Financial Crises, Panics, and Unconventional Monetary Policy109 Questions
Exam 31: Deficits and Debt: the Austerity Debate150 Questions
Exam 32: The Fiscal Policy Dilemma119 Questions
Exam 33: Jobs and Unemployment78 Questions
Exam 34: Inflation, Deflation, and Macro Policy175 Questions
Exam 35: International Financial Policy211 Questions
Exam 36: Macro Policy in a Global Setting134 Questions
Exam 37: Structural Stagnation and Globalization125 Questions
Exam 38: Macro Policy in Developing Countries142 Questions
Select questions type


Price tends to be in equilibrium where supply and demand intersect because when quantity supplied:
(Multiple Choice)
4.8/5  (77)
(77) Three hurricanes, combined with the already high real-estate prices, have made people reconsider whether to retire to Florida. The cost of homeownership has increased due to stricter building codes. The influx of retirees is expected to rise. Which of the following factors is tending to move the demand curve for Florida housing to the right?
(Multiple Choice)
4.7/5 (75)
(75) For which of the following markets would the fallacy of composition most likely apply?
(Multiple Choice)
4.8/5 (76)
(76) The more the current price exceeds the equilibrium price, the:
(Multiple Choice)
4.9/5 (92)
(92) Suppliers will supply more of a good when the price of that good rises because the opportunity cost of not producing that good has risen.
(True/False)
4.8/5 (74)
(74) The supply of leather jackets would be expected to increase as a result of:
(Multiple Choice)
4.9/5 (84)
(84) Refer to the graphs showing the demand for music downloads. What arrow shows the effect of an increase in the number of consumers in the market on the demand for music downloads? 

(Multiple Choice)
4.8/5 (72)
(72) The statement, "Assuming that if it is rational for one person to stand at a football game to get a better view then it is rational for everyone to stand at a football game to get a better view" is an example of:
(Multiple Choice)
4.8/5 (83)
(83) Suppose that college tuition is higher this year than last year and that more students are enrolled in college this year than last year. Based on this information, we can best conclude that:
(Multiple Choice)
4.8/5 (81)
(81) Given the following individual demand tables for individuals A-D,construct a market demand curve. Price A .50 5 6 10 8 1.00 5 5 8 7 1.50 5 4 6 6 2.00 0 3 4 5 2.50 0 2 2 4 3.00 0 1 0 3
(Essay)
4.9/5 (77)
(77) Consider the following supply and demand picture of the market for Oreos.Note that the market is currently in equilibrium,with a price of P* and a quantity exchanged of Q*. 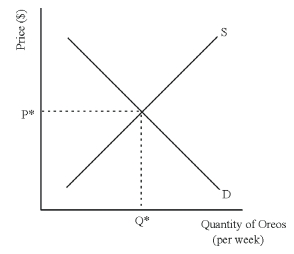 For each of the scenarios below,draw a picture that illustrates the impact on price and quantity exchanged.Explain each of your pictures by describing what is happening to the supply side of the market.
(a)The price of Hydrox cookies goes down.
(b)Due to a disastrous growing season,the price of cocoa triples.
For each of the scenarios below,draw a picture that illustrates the impact on price and quantity exchanged.Explain each of your pictures by describing what is happening to the supply side of the market.
(a)The price of Hydrox cookies goes down.
(b)Due to a disastrous growing season,the price of cocoa triples. (Essay)
4.9/5 (85)
(85) Which of the following would likely result in an increase in the demand for beef?
(Multiple Choice)
4.8/5 (76)
(76) When the going rate is $10.00 per hour, Ann wants to babysit 6 hours each week and Pat wants to babysit 4 hours each week. If the rate goes up to $12.00, Ann and Pat both double the number of hours they are willing to babysit each week. Based on this information, a combined supply curve will pass through the points:
(Multiple Choice)
4.8/5 (83)
(83) Refer to the graphs shown. Assume the graph reflects demand in the egg market. Which arrow best captures the impact of increased consumer concern about cholesterol on the egg market? 

(Multiple Choice)
4.8/5 (76)
(76) The following graph shows the supply of movie downloads. What is the market quantity that would be supplied at a price of $2.00? 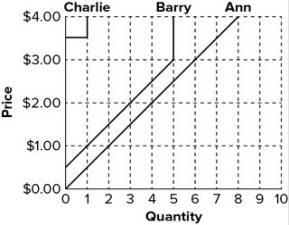
(Multiple Choice)
4.8/5 (72)
(72) When applied to labor markets, the law of supply suggests that:
(Multiple Choice)
4.8/5 (83)
(83) The model of supply and demand leads to the prediction that low interest rates cause:
(Multiple Choice)
4.7/5 (79)
(79) Which of the following would be expected to cause the quantity of wool supplied to decrease?
(Multiple Choice)
4.8/5 (73)
(73) At a price of $3.50, the quantity supplied by the market will be 14.
Price Ann's Supply Barry's Supply Charlie's Supply Market Supply \ 0.00 0 0 0 0 0.50 1 0 0 1 1.00 2 1 0 3 1.50 3 2 0 5 2.00 4 3 0 7 2.50 5 4 0 - 3.00 6 5 0 - 3.50 7 5 2 - 4.00 8 5 2 -
(True/False)
5.0/5 (80)
(80) Explain what it means to say that the cotton market is in "equilibrium." What forces (other than market forces)can be involved in determining the equilibrium price of cotton?
(Essay)
4.9/5 (65)
(65) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)