



 Chat with AI
Exam 14: Monopoly and Monopolistic Competition

Exam 1: Economics and Economic Reasoning158 Questions
Exam 2: The Production Possibility Model, Trade, and Globalization133 Questions
Exam 3: Economic Institutions163 Questions
Exam 4: Supply and Demand182 Questions
Exam 5: Using Supply and Demand163 Questions
Exam 6: Describing Supply and Demand: Elasticities216 Questions
Exam 7: Taxation and Government Intervention201 Questions
Exam 8: Market Failure Versus Government Failure197 Questions
Exam 9: Comparative Advantage, Exchange Rates, and Globalization118 Questions
Exam 10: International Trade Policy99 Questions
Exam 11: Production and Cost Analysis I194 Questions
Exam 12: Production and Cost Analysis II152 Questions
Exam 13: Perfect Competition170 Questions
Exam 14: Monopoly and Monopolistic Competition274 Questions
Exam 15: Oligopoly and Antitrust Policy142 Questions
Exam 16: Real-World Competition and Technology108 Questions
Exam 17: Work and the Labor Market150 Questions
Exam 18: Who Gets What the Distribution of Income131 Questions
Exam 19: The Logic of Individual Choice: the Foundation of Supply and Demand170 Questions
Exam 20: Game Theory, Strategic Decision Making, and Behavioral Economics103 Questions
Exam 21: Thinking Like a Modern Economist97 Questions
Exam 22: Behavioral Economics and Modern Economic Policy126 Questions
Exam 23: Microeconomic Policy, Economic Reasoning, and Beyond134 Questions
Exam 24: Economic Growth, Business Cycles, and Unemployment124 Questions
Exam 25: Measuring and Describing the Aggregate Economy229 Questions
Exam 26: The Keynesian Short-Run Policy Model: Demand-Side Policies220 Questions
Exam 27: The Classical Long-Run Policy Model: Growth and Supply-Side Policies133 Questions
Exam 28: The Financial Sector and the Economy214 Questions
Exam 29: Monetary Policy243 Questions
Exam 30: Financial Crises, Panics, and Unconventional Monetary Policy109 Questions
Exam 31: Deficits and Debt: the Austerity Debate150 Questions
Exam 32: The Fiscal Policy Dilemma119 Questions
Exam 33: Jobs and Unemployment78 Questions
Exam 34: Inflation, Deflation, and Macro Policy175 Questions
Exam 35: International Financial Policy211 Questions
Exam 36: Macro Policy in a Global Setting134 Questions
Exam 37: Structural Stagnation and Globalization125 Questions
Exam 38: Macro Policy in Developing Countries142 Questions
Select questions type


If P = Q/15 represents marginal cost for a monopolist and market supply for a competitive industry and market demand is given by Qd = 500 - 10P, the difference between the monopoly equilibrium and the competitive equilibrium is that a monopolist would produce:
(Multiple Choice)
4.9/5  (69)
(69) Refer to the graph shown of a monopolistically competitive firm. You can conclude that: 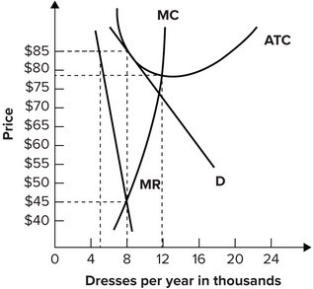
(Multiple Choice)
4.7/5 (87)
(87) Under monopolistic competition, a long-run equilibrium exists when price equals:
(Multiple Choice)
4.8/5 (81)
(81) Refer to the graph shown. If this monopolist were forced to set price equal to marginal cost, in the long run it probably would produce: 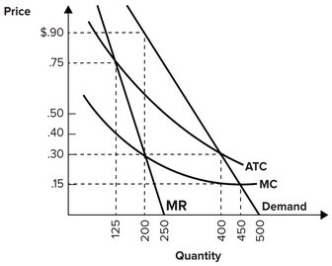
(Multiple Choice)
4.8/5 (75)
(75) If a natural monopolist were forced to set price equal to average cost, it would:
(Multiple Choice)
4.8/5 (80)
(80) If a monopolist increases output from 14 to 15 by lowering its price from $32 to $31, marginal revenue is:
(Multiple Choice)
4.8/5 (83)
(83) A profit-maximizing firm in a monopolistically competitive industry sells its product at a price:
(Multiple Choice)
4.8/5 (86)
(86) If a monopolist can price discriminate among buyers, it will charge buyers with more elastic demands a higher price.
(True/False)
4.8/5 (82)
(82) If a monopolistically competitive firm is earning economic profits in the short run:
(Multiple Choice)
4.7/5 (63)
(63) Refer to the graph shown. If this graph represents a monopoly market, the equilibrium price and quantity will be: 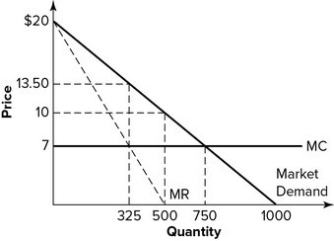
(Multiple Choice)
4.8/5 (67)
(67) Refer to the graph shown. Assuming that this monopolist maximizes profit, it will produce: 
(Multiple Choice)
5.0/5 (85)
(85) In long-run equilibrium, monopolistically competitive firms produce where:
(Multiple Choice)
4.9/5 (71)
(71) Which of the following statements for a monopolistic competitor in long-run equilibrium is true?
(Multiple Choice)
4.8/5 (84)
(84) Refer to the graph shown. At an output of a, the monopolist should: 
(Multiple Choice)
4.9/5 (88)
(88) Refer to the graph shown. The areas that represent the net gain to society of eliminating the monopoly are: 
(Multiple Choice)
4.9/5 (71)
(71) Why are barriers to entry important to maintaining a monopoly? Discuss the three most important types of barriers to entry.
(Essay)
4.8/5 (72)
(72) Refer to the graph shown. If this firm is maximizing profit, it will: 
(Multiple Choice)
4.7/5 (79)
(79) Refer to the graph shown. If the firm maximizes profit, its daily output will be: 
(Multiple Choice)
4.9/5 (76)
(76) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)