



 Chat with AI
Exam 49: Resource Markets

Exam 1: Economics: The World Around You90 Questions
Exam 2: Choice, Opportunity Costs, and Specialization94 Questions
Exam 3: Markets, Demand and Supply, and the Price System97 Questions
Exam 5: The Market System and the Private and Public Sector97 Questions
Exam 4: Elasticity: Demand and Supply126 Questions
Exam 6: National Income Accounting104 Questions
Exam 7: an Introduction to the Foreign Exchange Market and the Balance of Payments90 Questions
Exam 8: Consumer Choice132 Questions
Exam 9: Supply: The Costs of Doing Business106 Questions
Exam 10: Unemployment and Inflation129 Questions
Exam 11: Macroeconomic Equilibrium: Aggregate Demand and Supply122 Questions
Exam 12: Profit Maximization122 Questions
Exam 13: Aggregate Expenditures115 Questions
Exam 14: Perfect Competition135 Questions
Exam 15: Income and Expenditures Equilibrium134 Questions
Exam 16: Monopoly118 Questions
Exam 17: Fiscal Policy93 Questions
Exam 18: Monopolistic Competition and Oligopoly111 Questions
Exam 19: Antitrust and Regulation100 Questions
Exam 10: Money and Banking125 Questions
Exam 21: Market Failures, Government Failures, and Rent Seeking121 Questions
Exam 22: Monetary Policy141 Questions
Exam 23: Macroeconomic Policy: Tradeoffs, Expectations, Credibility, and Sources of Business Cycles112 Questions
Exam 24: Resource Markets112 Questions
Exam 25: Macroeconomic Viewpoints: New Keynesian, Monetarist, and New Classical99 Questions
Exam 26: The Labor Market114 Questions
Exam 27: Capital Markets100 Questions
Exam 28: Economic Growth99 Questions
Exam 29: Development Economics104 Questions
Exam 30: the Land Market and Natural Resources55 Questions
Exam 31: Aging, Social Security and Health Care88 Questions
Exam 32: Globalization84 Questions
Exam 33: Elasticity: Demand and Supply126 Questions
Exam 34: Income Distribution, Poverty and Government Policy115 Questions
Exam 35: World Trade Equilibrium112 Questions
Exam 36: Consumer Choice132 Questions
Exam 37: International Trade Restrictions109 Questions
Exam 38: World Trade Equilibrium112 Questions
Exam 39: Exchange Rates and Financial Links Between Countries132 Questions
Exam 40: International Trade Restrictions109 Questions
Exam 41: Supply: the Costs of Doing Business106 Questions
Exam 42: Exchange Rates and Financial Links Between Countries132 Questions
Exam 43: Profit Maximization122 Questions
Exam 44: Perfect Competition135 Questions
Exam 45: Monopoly118 Questions
Exam 46: Monopolistic Competition and Oligopoly111 Questions
Exam 47: Antitrust and Regulation100 Questions
Exam 48: Market Failures, Government Failures, and Rent Seeking121 Questions
Exam 49: Resource Markets112 Questions
Exam 50: The Labor Market114 Questions
Exam 51: Capital Markets100 Questions
Exam 52: The Land Market and Natural Resources55 Questions
Exam 53: Aging, Social Security and Health Care87 Questions
Exam 54: Income Distribution, Poverty and Government Policy115 Questions
Exam 55: World Trade Equilibrium112 Questions
Exam 56: International Trade Restrictions109 Questions
Exam 57: Exchange Rates and Financial Links Between Countries132 Questions
Select questions type


Suppose output of a firm hiring workers in a competitive labor market increases by three units when an additional worker is hired.This firm will hire more laborers if the market price of its product is $4 and the wage rate is $9.[Hint: Marginal revenue product of a resource is equal to the product of marginal product of the resource and the marginal revenue of the firm.]
(True/False)
4.8/5  (81)
(81) The profit-maximizing number of workers for a monopsony to employ is derived at the point where the marginal-revenue product of labor is equal to the marginal-factor cost of labor.
(True/False)
4.9/5 (67)
(67) A firm is said to be a monopsonist if it is the sole seller of a commodity in the market.
(True/False)
4.8/5 (78)
(78) Goods which are demanded to produce something else are said to have a(n):
(Multiple Choice)
4.9/5 (74)
(74) The negative slope of the demand curve of a resource indicates an inverse relationship between the price of the resource and the quantity demanded.
(True/False)
4.8/5 (75)
(75) The value of the marginal product of a resource is equal to:
(Multiple Choice)
4.9/5 (80)
(80) Under perfect competition in the resource market, the marginal factor cost curve:
(Multiple Choice)
4.9/5 (89)
(89) The figure given below shows the marginal revenue product (MRP)of accountants in a firm. Figure 28.2 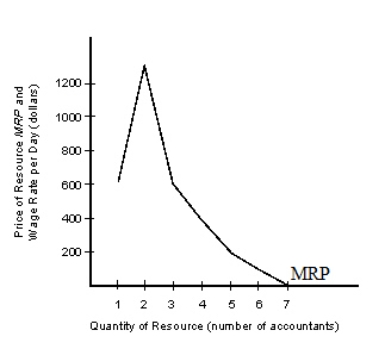 MRP = MP ´ MR
According to Figure 28.2, the:
MRP = MP ´ MR
According to Figure 28.2, the: (Multiple Choice)
4.9/5 (69)
(69) The following table shows output per hour produced by the different units of labor. Table 28.1
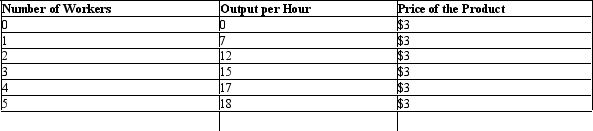 The marginal revenue product of a resource is equal to the product of the marginal product of an input and marginal revenue.
According to Table 28.1, if the wage rate is $9 per hour, how many workers should this firm hire?
The marginal revenue product of a resource is equal to the product of the marginal product of an input and marginal revenue.
According to Table 28.1, if the wage rate is $9 per hour, how many workers should this firm hire? (Multiple Choice)
4.7/5 (93)
(93) Which of the following statements best illustrates the relationship between the market for products and the market for resources?
(Multiple Choice)
4.9/5 (81)
(81) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)