



 Chat with AI
Exam 48: Market Failures, Government Failures, and Rent Seeking

Exam 1: Economics: The World Around You90 Questions
Exam 2: Choice, Opportunity Costs, and Specialization94 Questions
Exam 3: Markets, Demand and Supply, and the Price System97 Questions
Exam 5: The Market System and the Private and Public Sector97 Questions
Exam 4: Elasticity: Demand and Supply126 Questions
Exam 6: National Income Accounting104 Questions
Exam 7: an Introduction to the Foreign Exchange Market and the Balance of Payments90 Questions
Exam 8: Consumer Choice132 Questions
Exam 9: Supply: The Costs of Doing Business106 Questions
Exam 10: Unemployment and Inflation129 Questions
Exam 11: Macroeconomic Equilibrium: Aggregate Demand and Supply122 Questions
Exam 12: Profit Maximization122 Questions
Exam 13: Aggregate Expenditures115 Questions
Exam 14: Perfect Competition135 Questions
Exam 15: Income and Expenditures Equilibrium134 Questions
Exam 16: Monopoly118 Questions
Exam 17: Fiscal Policy93 Questions
Exam 18: Monopolistic Competition and Oligopoly111 Questions
Exam 19: Antitrust and Regulation100 Questions
Exam 10: Money and Banking125 Questions
Exam 21: Market Failures, Government Failures, and Rent Seeking121 Questions
Exam 22: Monetary Policy141 Questions
Exam 23: Macroeconomic Policy: Tradeoffs, Expectations, Credibility, and Sources of Business Cycles112 Questions
Exam 24: Resource Markets112 Questions
Exam 25: Macroeconomic Viewpoints: New Keynesian, Monetarist, and New Classical99 Questions
Exam 26: The Labor Market114 Questions
Exam 27: Capital Markets100 Questions
Exam 28: Economic Growth99 Questions
Exam 29: Development Economics104 Questions
Exam 30: the Land Market and Natural Resources55 Questions
Exam 31: Aging, Social Security and Health Care88 Questions
Exam 32: Globalization84 Questions
Exam 33: Elasticity: Demand and Supply126 Questions
Exam 34: Income Distribution, Poverty and Government Policy115 Questions
Exam 35: World Trade Equilibrium112 Questions
Exam 36: Consumer Choice132 Questions
Exam 37: International Trade Restrictions109 Questions
Exam 38: World Trade Equilibrium112 Questions
Exam 39: Exchange Rates and Financial Links Between Countries132 Questions
Exam 40: International Trade Restrictions109 Questions
Exam 41: Supply: the Costs of Doing Business106 Questions
Exam 42: Exchange Rates and Financial Links Between Countries132 Questions
Exam 43: Profit Maximization122 Questions
Exam 44: Perfect Competition135 Questions
Exam 45: Monopoly118 Questions
Exam 46: Monopolistic Competition and Oligopoly111 Questions
Exam 47: Antitrust and Regulation100 Questions
Exam 48: Market Failures, Government Failures, and Rent Seeking121 Questions
Exam 49: Resource Markets112 Questions
Exam 50: The Labor Market114 Questions
Exam 51: Capital Markets100 Questions
Exam 52: The Land Market and Natural Resources55 Questions
Exam 53: Aging, Social Security and Health Care87 Questions
Exam 54: Income Distribution, Poverty and Government Policy115 Questions
Exam 55: World Trade Equilibrium112 Questions
Exam 56: International Trade Restrictions109 Questions
Exam 57: Exchange Rates and Financial Links Between Countries132 Questions
Select questions type


A market failure occurs when the market outcome is not the socially efficient outcome.

Free
(True/False)
4.9/5  (77)
(77) Correct Answer: Verified
True
Which of the following is not a problem with a public good?
Free
(Multiple Choice)
4.9/5 (86)
(86) Correct Answer:Verified
VerifiedB
The government should subsidize the production of goods which generate a positive externality.
Free
(True/False)
4.9/5 (71)
(71) Correct Answer:Verified
VerifiedTrue
Private costs exceed social cost when external benefits are created.
(True/False)
4.9/5 (91)
(91) When a particular resource is commonly used, it tends to get underutilized.
(True/False)
4.9/5 (85)
(85) When each additional resource adds increasing amounts of additional output, it refers to a situation of:
(Multiple Choice)
4.8/5 (70)
(70) When a divergence between social costs and private costs exists, then:
(Multiple Choice)
4.9/5 (77)
(77) The following table shows the costs and benefit of producing a commodity. Table 13.1
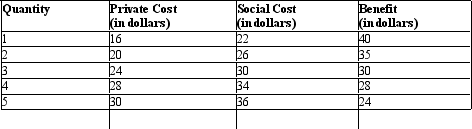 According to Table 13.1, at the social equilibrium:
 (Multiple Choice)
4.7/5 (66)
(66) When the government imposes a tax on production of a commodity:
(Multiple Choice)
5.0/5 (72)
(72) Suppose the wheat industry is in long-run equilibrium, so that farmers are earning a normal rate of return.Suppose the farmers are able to convince the Congress to provide a minimum price for wheat that is above the equilibrium price.The result would be:
(Multiple Choice)
4.8/5 (77)
(77) In the case of automobile and medical insurance, adverse selection might mean that, as the cost of insurance rises, the good drivers and healthy people reduce their coverage while the poor drivers and unhealthy people maintain their coverage.
(True/False)
4.8/5 (74)
(74) If a gas station selling gasoline is asked to incorporate the pollution costs, its supply curve will shift to the right.
(True/False)
4.8/5 (79)
(79) The Clean Air Act of 1972 required some companies to install the "best available" pollution control technologies.This was an example of:
(Multiple Choice)
4.7/5 (88)
(88) A person who takes less care of his health after obtaining a health insurance is creating a negative externality.
(True/False)
4.8/5 (77)
(77) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)