



 Chat with AI
Exam 14: Firms in Competitive Markets

Exam 1: Ten Lessons From Economics146 Questions
Exam 2: Thinking Like an Economist133 Questions
Exam 3: Interdependence and the Gains From Trade139 Questions
Exam 4: The Market Forces of Supply and Demand215 Questions
Exam 5: Elasticity and Its Application178 Questions
Exam 6: Supply, Demand and Government Policies145 Questions
Exam 7: Consumers, Producers and the Efficiency of Markets171 Questions
Exam 8: Application: the Costs of Taxation135 Questions
Exam 9: Application: International Trade151 Questions
Exam 10: Externalities199 Questions
Exam 11: Public Goods and Common Resources178 Questions
Exam 12: The Design of the Tax System154 Questions
Exam 13: The Costs of Production191 Questions
Exam 14: Firms in Competitive Markets198 Questions
Exam 15: Monopoly212 Questions
Exam 16: Monopolistic Competition212 Questions
Exam 17: Business Strategy and Oligopoly179 Questions
Exam 18: Competition Policy103 Questions
Exam 19: The Markets for the Factors of Production214 Questions
Exam 20: Earnings, Unions and Discrimination201 Questions
Exam 21: Income Inequity and Poverty111 Questions
Exam 22: The Theory of Consumer Choice158 Questions
Exam 23: Frontiers of Microeconomics111 Questions
Exam 24: Measuring a Nations Income51 Questions
Exam 25: Measuring the Cost of Living55 Questions
Exam 26: Production and Growth62 Questions
Exam 27: Saving, Investment and the Financial System62 Questions
Exam 28: The Natural Rate of Unemployment58 Questions
Exam 29: The Monetary System66 Questions
Exam 30: Inflation: Its Causes and Costs74 Questions
Exam 31: Open-Economy Macroeconomics: Basic Concepts68 Questions
Exam 32: A Macroeconomic Theory of the Open Economy61 Questions
Exam 33: Aggregate Demand and Aggregate Supply81 Questions
Exam 34: The Influence of Monetary and Fiscal Policy on Aggregate Demand73 Questions
Exam 35: The Short-Run Trade-Off Between Inflation and Unemployment57 Questions
Exam 36: Global Financial Crisis of 2008 and Beyond37 Questions
Exam 37: Five Debates Over Macroeconomic Policy38 Questions
Select questions type


In the long run, all of a firm's costs are variable.In this case the exit criterion for a profit-maximising firm is:
(Multiple Choice)
4.9/5  (72)
(72) The Wheeler Wheat Farm sells wheat to a grain broker.Since the market for wheat is generally considered to be competitive, the Wheeler Farm:
(Multiple Choice)
4.8/5 (76)
(76) By comparing the marginal revenue and marginal cost from each unit produced, a firm in a competitive market can determine the profit-maximising level of production.
(True/False)
4.9/5 (85)
(85) When firms in a competitive market have different costs, it is likely that:
(Multiple Choice)
5.0/5 (91)
(91) All of the following conditions are consistent with a firm's decision to shut down:
TR < VC, TR/Q < VC/Q, and P < MR.(TR = total revenue, VC = variable cost, Q = level of production, P = price and MR = marginal revenue.)
(True/False)
5.0/5 (73)
(73) Choose the correct statement.In the long-run, each firm in a competitive market with identical firms will:
i. operate at the firm's efficient scale
ii. produce at a point where Marginal Cost and Average Total Cost are equal
iii. will earn zero economic profit
(Multiple Choice)
4.8/5 (86)
(86) Regardless of the time horizon considered, firms in a competitive market will never earn positive economic profit.
(True/False)
4.9/5 (75)
(75) A profit-maximising firm should always increase the level of production if marginal cost exceeds marginal revenue.
(True/False)
4.8/5 (87)
(87) When entry and exit behaviour of firms in an industry does not affect a firm's cost structure:
(Multiple Choice)
4.8/5 (77)
(77) At the end of the process of entry and exit, it is possible that some firms in a competitive market are making positive economic profit.
(True/False)
4.9/5 (83)
(83) Graph 14-9 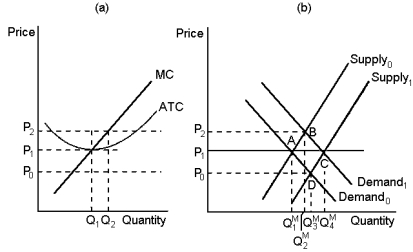 -Refer to Graph 14-9.When a firm in a competitive market, like the one depicted in panel (a), observes market price rising from P₁ to P₂, it is most likely the result of:
 (Multiple Choice)
4.9/5 (88)
(88) Graph 14-9
-Refer to Graph 14-9.Assume that the market starts in equilibrium at point A in panel (b).An increase in demand from DemanD₀ to DemanD₁ will result in:
-Refer to Graph 14-9.Assume that the market starts in equilibrium at point A in panel (b).An increase in demand from DemanD₀ to DemanD₁ will result in: (Multiple Choice)
4.8/5 (85)
(85) There are 500 profit-maximising firms in a competitive market.When market price is $10 per unit, each firm produces exactly 20 units of output.What are the total quantity supplied to the market, the total revenue, average revenue and marginal revenue of each firm?
(Essay)
4.8/5 (71)
(71) Suppose a movie theatre stays open late at night even though few people attend screenings this late.Which of the following principles are being demonstrated?
(i) fixed costs are sunk in the short-run
(ii) in the short-run, only variable costs are important to the decision to stay open for late evening showings
(iii) if variable exceeds revenue, the theatre owner is making a profitable strategic decision to remain open late into the night
(Multiple Choice)
4.9/5 (76)
(76) A long-run supply curve that is more elastic than a short-run supply curve results from which of the following circumstances?
(Multiple Choice)
4.9/5 (80)
(80) For a firm in a perfectly competitive market, the price of the good is always equal to:
(Multiple Choice)
4.7/5 (70)
(70) Which of the following statements are most likely to be true for the air transportation industry?
(i) in the short run, the cost of the airplane is sunk
(ii) the opportunity cost of a flight is the variable cost
(iii) as long as total revenue exceeds fixed cost, the airlines should continue operating
(Multiple Choice)
4.9/5 (70)
(70) Table 14-2
The price of each butterfly that David Butterfly, a butterfly farmer in Greytown, sells is:
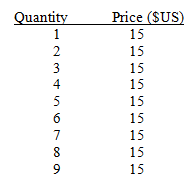 -Refer to Table 14-2.Marginal revenue is declining over the range:
 (Multiple Choice)
4.9/5 (78)
(78) If it is optimal for a firm to exit in the short-run, then it will also be optimal for the firm to exit in the long-run, all else equal.
(True/False)
4.8/5 (79)
(79) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)