



 Chat with AI
Exam 14: Firms in Competitive Markets

Exam 1: Ten Lessons From Economics146 Questions
Exam 2: Thinking Like an Economist133 Questions
Exam 3: Interdependence and the Gains From Trade139 Questions
Exam 4: The Market Forces of Supply and Demand215 Questions
Exam 5: Elasticity and Its Application178 Questions
Exam 6: Supply, Demand and Government Policies145 Questions
Exam 7: Consumers, Producers and the Efficiency of Markets171 Questions
Exam 8: Application: the Costs of Taxation135 Questions
Exam 9: Application: International Trade151 Questions
Exam 10: Externalities199 Questions
Exam 11: Public Goods and Common Resources178 Questions
Exam 12: The Design of the Tax System154 Questions
Exam 13: The Costs of Production191 Questions
Exam 14: Firms in Competitive Markets198 Questions
Exam 15: Monopoly212 Questions
Exam 16: Monopolistic Competition212 Questions
Exam 17: Business Strategy and Oligopoly179 Questions
Exam 18: Competition Policy103 Questions
Exam 19: The Markets for the Factors of Production214 Questions
Exam 20: Earnings, Unions and Discrimination201 Questions
Exam 21: Income Inequity and Poverty111 Questions
Exam 22: The Theory of Consumer Choice158 Questions
Exam 23: Frontiers of Microeconomics111 Questions
Exam 24: Measuring a Nations Income51 Questions
Exam 25: Measuring the Cost of Living55 Questions
Exam 26: Production and Growth62 Questions
Exam 27: Saving, Investment and the Financial System62 Questions
Exam 28: The Natural Rate of Unemployment58 Questions
Exam 29: The Monetary System66 Questions
Exam 30: Inflation: Its Causes and Costs74 Questions
Exam 31: Open-Economy Macroeconomics: Basic Concepts68 Questions
Exam 32: A Macroeconomic Theory of the Open Economy61 Questions
Exam 33: Aggregate Demand and Aggregate Supply81 Questions
Exam 34: The Influence of Monetary and Fiscal Policy on Aggregate Demand73 Questions
Exam 35: The Short-Run Trade-Off Between Inflation and Unemployment57 Questions
Exam 36: Global Financial Crisis of 2008 and Beyond37 Questions
Exam 37: Five Debates Over Macroeconomic Policy38 Questions
Select questions type


If a firm with increasing marginal costs is operating in a competitive market, then average revenue will be:
(Multiple Choice)
4.8/5  (78)
(78) A production cost that has already been committed and cannot be recovered is termed a:
(Multiple Choice)
4.9/5 (76)
(76) According to the information provided, what would Lee's accounting profits need to be to allow her to reach the zero economic profit equilibrium?
(Multiple Choice)
4.8/5 (84)
(84) Jess, an aspiring small business owner, is looking at starting up a home business growing organic kale, turning it into Kale Chips, and selling it at the local market.The market for Kale Chips is served by many small suppliers, however, she believes the current suppliers may be earning excess profits.She calculates the cost structure of her business, which she believes to be identical to all the other Kale Chip suppliers operating in her area.Unfortunately, her housemate has spilt red wine all over the worksheet and only the following could be recovered:
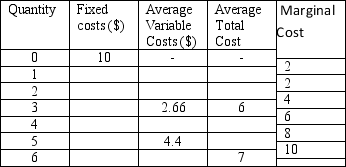 Suppose the current price of Kale Chips is $8.With the information supplied, should Jess enter into the Kale Chip industry? Why or why not? What will be the long-run competitive equilibrium price for Kale Chips? Could Jess earn a profit at this long-run price?
 (Essay)
5.0/5 (68)
(68) In the long run, a competitive market with 1000 identical firms will experience an equilibrium price equal to the minimum of each firm's average total cost.
(True/False)
4.9/5 (86)
(86) Whenever a perfectly competitive firm chooses to change its level of output, its marginal revenue:
(Multiple Choice)
4.9/5 (81)
(81) According to the information provided, what are Lee's opportunity costs of operating her new business?
(Multiple Choice)
4.9/5 (76)
(76) Graph 14-6 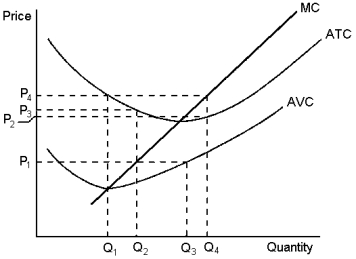 This graph depicts the cost structure of a firm in a competitive market.Use the graph to answer the following question(s).
-Refer to Graph 14-6.When market price is P₁, a profit-maximising firm's total revenue can be represented by the area:
This graph depicts the cost structure of a firm in a competitive market.Use the graph to answer the following question(s).
-Refer to Graph 14-6.When market price is P₁, a profit-maximising firm's total revenue can be represented by the area: (Multiple Choice)
4.9/5 (75)
(75) Table 14-2
The price of each butterfly that David Butterfly, a butterfly farmer in Greytown, sells is:
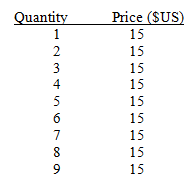 -Refer to Table 14-2.The price and quantity relationship shows that the market structure most likely facing a butterfly farmer is a:
 (Multiple Choice)
4.8/5 (71)
(71) If a firm in a competitive market sells 25 per cent less, then its total revenue will fall by 25 per cent.
(True/False)
4.8/5 (84)
(84) According to the information provided, as a result of the increase in the demand for abalone, we would predict that in the short run:
(Multiple Choice)
4.9/5 (71)
(71) Graph 14-1 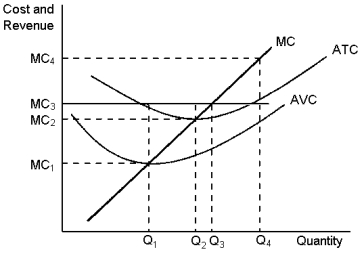 This graph depicts the cost structure for a firm in a competitive market.Use the graph to answer the following question(s).
-Refer to Graph 14-1.When market price is at MC2, a firm producing output level Q₁ would experience:
This graph depicts the cost structure for a firm in a competitive market.Use the graph to answer the following question(s).
-Refer to Graph 14-1.When market price is at MC2, a firm producing output level Q₁ would experience: (Multiple Choice)
4.9/5 (82)
(82) Prawns Galore, a prawn harvesting business in Southeast Queensland, has a 30-year loan on its prawn trawling boat.The annual loan payment is $25 000 and the boat has a market (salvage) value that exceeds its outstanding loan balance.Prior to the 2001 prawn harvesting season, Prawns Galore's accountant predicted that at expected market prices for prawns, Prawns Galore would have a net loss of $75 000 dollars after paying all 2001 expenses (including the annual loan payment).In this case, Prawns Galore should:
(Multiple Choice)
4.8/5 (76)
(76) It is not possible for the marginal firm in a competitive market to make an economic profit in the long-run.
(True/False)
4.9/5 (73)
(73) Sarah places a $110 value on seeing the Richmond Tigers play in the Grand Final.She purchases a ticket to the game for $60 but when she arrives at the game she discovers that her ticket is missing.A ticket scalper outside the stadium is selling tickets for $76 dollars.If Sarah purchases a ticket from one of the scalpers for $95, she is best demonstrating the principle that:
(Multiple Choice)
4.9/5 (80)
(80) In a competitive market, marginal revenue will only sometimes equal average revenue.
(True/False)
4.9/5 (86)
(86) If a seller is a price taker, they will be able to sell all the quantity they want at the market price.
(True/False)
4.9/5 (71)
(71) When looking at entering the marketplace, a prospective entrant should not consider fixed costs, as these will become sunk.
(True/False)
4.8/5 (81)
(81) Profit-maximising producers in a competitive market in general, produce output at a point where:
(Multiple Choice)
4.9/5 (68)
(68) The costs of investigating new factories can be regarded as a sunk cost.
(True/False)
4.9/5 (94)
(94) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)