



 Chat with AI
Exam 14: Firms in Competitive Markets

Exam 1: Ten Lessons From Economics146 Questions
Exam 2: Thinking Like an Economist133 Questions
Exam 3: Interdependence and the Gains From Trade139 Questions
Exam 4: The Market Forces of Supply and Demand215 Questions
Exam 5: Elasticity and Its Application178 Questions
Exam 6: Supply, Demand and Government Policies145 Questions
Exam 7: Consumers, Producers and the Efficiency of Markets171 Questions
Exam 8: Application: the Costs of Taxation135 Questions
Exam 9: Application: International Trade151 Questions
Exam 10: Externalities199 Questions
Exam 11: Public Goods and Common Resources178 Questions
Exam 12: The Design of the Tax System154 Questions
Exam 13: The Costs of Production191 Questions
Exam 14: Firms in Competitive Markets198 Questions
Exam 15: Monopoly212 Questions
Exam 16: Monopolistic Competition212 Questions
Exam 17: Business Strategy and Oligopoly179 Questions
Exam 18: Competition Policy103 Questions
Exam 19: The Markets for the Factors of Production214 Questions
Exam 20: Earnings, Unions and Discrimination201 Questions
Exam 21: Income Inequity and Poverty111 Questions
Exam 22: The Theory of Consumer Choice158 Questions
Exam 23: Frontiers of Microeconomics111 Questions
Exam 24: Measuring a Nations Income51 Questions
Exam 25: Measuring the Cost of Living55 Questions
Exam 26: Production and Growth62 Questions
Exam 27: Saving, Investment and the Financial System62 Questions
Exam 28: The Natural Rate of Unemployment58 Questions
Exam 29: The Monetary System66 Questions
Exam 30: Inflation: Its Causes and Costs74 Questions
Exam 31: Open-Economy Macroeconomics: Basic Concepts68 Questions
Exam 32: A Macroeconomic Theory of the Open Economy61 Questions
Exam 33: Aggregate Demand and Aggregate Supply81 Questions
Exam 34: The Influence of Monetary and Fiscal Policy on Aggregate Demand73 Questions
Exam 35: The Short-Run Trade-Off Between Inflation and Unemployment57 Questions
Exam 36: Global Financial Crisis of 2008 and Beyond37 Questions
Exam 37: Five Debates Over Macroeconomic Policy38 Questions
Select questions type


A firm's short-run supply curve is part of which of the following curves?
(Multiple Choice)
4.9/5  (101)
(101) If a firm in a competitive market increases production and its marginal revenue remains greater than its marginal cost, raising production will:
(Multiple Choice)
4.8/5 (85)
(85) Which of the following statements best reflects the production decision of a profit-maximising firm in a competitive market when price falls below the minimum of average variable cost?
(Multiple Choice)
4.9/5 (88)
(88) Table 14-2
The price of each butterfly that David Butterfly, a butterfly farmer in Greytown, sells is:
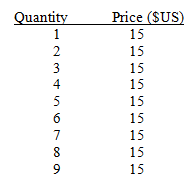 -Refer to Table 14-2.Price equals average revenue over the range of:
 (Multiple Choice)
4.8/5 (75)
(75) To maximise profit, a firm should operate at the minimum of average total cost.
(True/False)
4.8/5 (75)
(75) When a firm has little ability to influence market prices, it is said to be in what kind of a market?
(Multiple Choice)
4.9/5 (88)
(88) Table 14-1
This table shows the revenue and costs of a parrot farmer.  -Refer to Table 14-1.If the farmer is harvesting three parrots, the best response would be to:
 (Multiple Choice)
4.9/5 (80)
(80) Table 14-3
The market for Whizzly Jigs consists of many identical firms, each with the cost structure below.Suppose the current market price is $2. 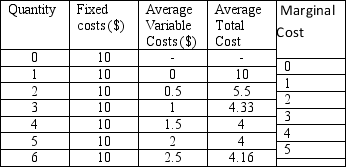
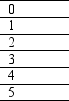 -Refer to table 14-3.Suppose the current market price is $2.What is the output of each individual firm?
 (Multiple Choice)
4.8/5 (80)
(80) In the long-run, a profit-maximising firm will choose to exit a market when:
(Multiple Choice)
4.9/5 (82)
(82) If, at a given output, the marginal cost curve lies below the marginal revenue curve but above the average total cost curve, then the firm can increase its profit by decreasing output.
(True/False)
4.9/5 (76)
(76) When a firm experiences zero-profit equilibrium, the firm's revenue must be sufficient to cover all opportunity costs.
(True/False)
4.7/5 (82)
(82) Suppose a competitive market consists of identical firms.The long-run and short-run supply curves will be identical when:
(Multiple Choice)
4.9/5 (75)
(75) When some resources used in production are only available in limited quantities, it is likely that the long-run supply curve in a competitive market is:
(Multiple Choice)
4.8/5 (85)
(85) Graph 14-8 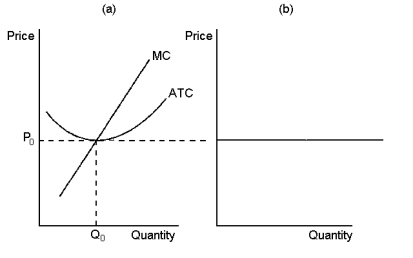 -Refer to Graph 14-8.If the figure in panel (a) reflects the long-run equilibrium of a profit-maximising firm in a competitive market, the figure in panel (b) most likely reflects:
 (Multiple Choice)
4.8/5 (84)
(84) Sunk costs are relevant to decisions about business strategy, as huge amounts of time have been invested in ensuring that the business is set up for success.
(True/False)
4.9/5 (85)
(85) Give two reasons why the long-run industry supply curve may slope upward.Use an example to demonstrate your reasons.
(Essay)
4.9/5 (90)
(90) Graph 14-1 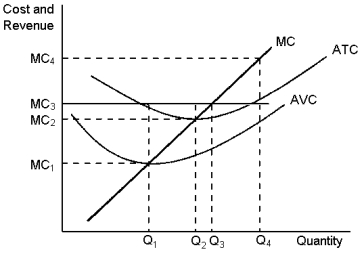 This graph depicts the cost structure for a firm in a competitive market.Use the graph to answer the following question(s).
-Refer to Graph 14-1.When market price is at MC4, a profit-maximising firm will produce what level of output?
This graph depicts the cost structure for a firm in a competitive market.Use the graph to answer the following question(s).
-Refer to Graph 14-1.When market price is at MC4, a profit-maximising firm will produce what level of output? (Multiple Choice)
4.7/5 (65)
(65) When firms in a perfectly competitive market face the same costs, in the long-run they must be operating:
(Multiple Choice)
4.7/5 (85)
(85) If a firm is making zero economic profit, it can still be making a positive accounting profit.
(True/False)
5.0/5 (83)
(83) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)