



 Chat with AI
Exam 14: Firms in Competitive Markets

Exam 1: Ten Lessons From Economics146 Questions
Exam 2: Thinking Like an Economist133 Questions
Exam 3: Interdependence and the Gains From Trade139 Questions
Exam 4: The Market Forces of Supply and Demand215 Questions
Exam 5: Elasticity and Its Application178 Questions
Exam 6: Supply, Demand and Government Policies145 Questions
Exam 7: Consumers, Producers and the Efficiency of Markets171 Questions
Exam 8: Application: the Costs of Taxation135 Questions
Exam 9: Application: International Trade151 Questions
Exam 10: Externalities199 Questions
Exam 11: Public Goods and Common Resources178 Questions
Exam 12: The Design of the Tax System154 Questions
Exam 13: The Costs of Production191 Questions
Exam 14: Firms in Competitive Markets198 Questions
Exam 15: Monopoly212 Questions
Exam 16: Monopolistic Competition212 Questions
Exam 17: Business Strategy and Oligopoly179 Questions
Exam 18: Competition Policy103 Questions
Exam 19: The Markets for the Factors of Production214 Questions
Exam 20: Earnings, Unions and Discrimination201 Questions
Exam 21: Income Inequity and Poverty111 Questions
Exam 22: The Theory of Consumer Choice158 Questions
Exam 23: Frontiers of Microeconomics111 Questions
Exam 24: Measuring a Nations Income51 Questions
Exam 25: Measuring the Cost of Living55 Questions
Exam 26: Production and Growth62 Questions
Exam 27: Saving, Investment and the Financial System62 Questions
Exam 28: The Natural Rate of Unemployment58 Questions
Exam 29: The Monetary System66 Questions
Exam 30: Inflation: Its Causes and Costs74 Questions
Exam 31: Open-Economy Macroeconomics: Basic Concepts68 Questions
Exam 32: A Macroeconomic Theory of the Open Economy61 Questions
Exam 33: Aggregate Demand and Aggregate Supply81 Questions
Exam 34: The Influence of Monetary and Fiscal Policy on Aggregate Demand73 Questions
Exam 35: The Short-Run Trade-Off Between Inflation and Unemployment57 Questions
Exam 36: Global Financial Crisis of 2008 and Beyond37 Questions
Exam 37: Five Debates Over Macroeconomic Policy38 Questions
Select questions type


Assume the market for lawn mowing is competitive.If a firm has no fixed costs and constant marginal costs, then a doubling of output will lead to a doubling of total revenue.
(True/False)
4.8/5  (75)
(75) When new firms have an incentive to enter a competitive market, their entry will:
(Multiple Choice)
4.8/5 (87)
(87) Use a graph to demonstrate the circumstances that would prevail in a perfectly competitive market where firms are experiencing economic losses.Identify costs, revenue and the economic losses on your graph.Using your graph, determine whether this firm will shut down in the short run, or choose to remain in the market.Explain your answer.
(Essay)
4.7/5 (71)
(71) Suppose a firm is operating in a competitive market where the price of the good is $12.If, at the current level of output, the firm's average cost is $15, marginal cost is $17, and fixed costs are $10, then the firm will:
(Multiple Choice)
4.9/5 (86)
(86) Suppose a profit-maximising firm in a competitive market is unable to generate enough revenue to pay all of its fixed costs.In the short run it should:
(Multiple Choice)
4.7/5 (82)
(82) Which of the following is not a characteristic of a perfectly competitive market?
(Multiple Choice)
4.8/5 (76)
(76) When you buy a product from a firm in a competitive market, the price you pay for the product is likely to be:
(Multiple Choice)
4.8/5 (79)
(79) Table 14-3
The market for Whizzly Jigs consists of many identical firms, each with the cost structure below.Suppose the current market price is $2. 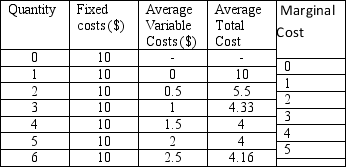
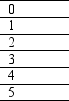 -Refer to table 14-3.Suppose the current market price is $2.Which of the following is likely to occur?
 (Multiple Choice)
4.7/5 (97)
(97) Kevin is a bricklayer in Melbourne.Bricklaying is a fiercely competitive industry with many small suppliers all offering similar products.Fortunately for Kevin he is one of the best bricklayers in the business, in fact, in one hour Kevin can lay twice as many bricks as any other bricklayer in town, which helps him keep his costs down.Suppose the market is initially at a competitive equilibrium.After a particularly inspiring season of The Block, there is a permanent increase in demand for home renovations.Following the increase in demand, is it possible for Kevin and the other bricklayers to make economic profit in the short-run? How about in the long-run? Explain.
(Essay)
4.9/5 (78)
(78) When a profit-maximising firm in a competitive market has zero economic profit, accounting profit:
(Multiple Choice)
4.7/5 (87)
(87) If all incumbent firms and all potential firms have the same cost curves and the market is characterised by free entry and exit, the long-run:
(Multiple Choice)
4.9/5 (77)
(77) The Wheeler Wheat Farm has a long-term lease on 5000 acres of land in New South Wales.The annual lease payment is $250,000.Prior to planting in the spring of 2001, the Wheeler Farm accountant predicted that the Farm would have $135 000 left after paying all of its costs except the annual lease payment.In this case, the Wheeler Wheat Farm should:
(Multiple Choice)
4.9/5 (87)
(87) When will a firm shut-down temporarily? When do firms exit an industry? Holding all else constant, is it ever the case that a firm will shut down in the short-run, but will find it profitable to stay in the long run?
(Essay)
4.9/5 (81)
(81) In long-run equilibrium of a competitive market, the number of firms in the markets adjusts so that all of the market demand is satisfied at a price equal to:
(Multiple Choice)
4.7/5 (85)
(85) A profit-maximising firm that is showing losses (negative profit) most likely faces which of the following conditions?
(Multiple Choice)
4.9/5 (75)
(75) If rational, profit-maximising firms (like rational people) think at the margin, then marginal adjustments to production:
(Multiple Choice)
4.9/5 (70)
(70) The long-run equilibrium in a competitive market characterised by firms with identical costs is generally characterised by firms operating at efficient scale.
(True/False)
4.8/5 (75)
(75) The market's short-run supply curve will be steeper than an individual firm's supply curve.
(True/False)
4.9/5 (76)
(76) The irrelevance of sunk costs is best described by which of the following business decisions?
(Multiple Choice)
4.9/5 (76)
(76) From the perspective of a price-taking competitive firm, what is the relationship between price, average revenue and marginal revenue?
(Essay)
4.9/5 (88)
(88) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)