



 Chat with AI
Exam 41: Supply: the Costs of Doing Business

Exam 1: Economics: The World Around You90 Questions
Exam 2: Choice, Opportunity Costs, and Specialization94 Questions
Exam 3: Markets, Demand and Supply, and the Price System97 Questions
Exam 5: The Market System and the Private and Public Sector97 Questions
Exam 4: Elasticity: Demand and Supply126 Questions
Exam 6: National Income Accounting104 Questions
Exam 7: an Introduction to the Foreign Exchange Market and the Balance of Payments90 Questions
Exam 8: Consumer Choice132 Questions
Exam 9: Supply: The Costs of Doing Business106 Questions
Exam 10: Unemployment and Inflation129 Questions
Exam 11: Macroeconomic Equilibrium: Aggregate Demand and Supply122 Questions
Exam 12: Profit Maximization122 Questions
Exam 13: Aggregate Expenditures115 Questions
Exam 14: Perfect Competition135 Questions
Exam 15: Income and Expenditures Equilibrium134 Questions
Exam 16: Monopoly118 Questions
Exam 17: Fiscal Policy93 Questions
Exam 18: Monopolistic Competition and Oligopoly111 Questions
Exam 19: Antitrust and Regulation100 Questions
Exam 10: Money and Banking125 Questions
Exam 21: Market Failures, Government Failures, and Rent Seeking121 Questions
Exam 22: Monetary Policy141 Questions
Exam 23: Macroeconomic Policy: Tradeoffs, Expectations, Credibility, and Sources of Business Cycles112 Questions
Exam 24: Resource Markets112 Questions
Exam 25: Macroeconomic Viewpoints: New Keynesian, Monetarist, and New Classical99 Questions
Exam 26: The Labor Market114 Questions
Exam 27: Capital Markets100 Questions
Exam 28: Economic Growth99 Questions
Exam 29: Development Economics104 Questions
Exam 30: the Land Market and Natural Resources55 Questions
Exam 31: Aging, Social Security and Health Care88 Questions
Exam 32: Globalization84 Questions
Exam 33: Elasticity: Demand and Supply126 Questions
Exam 34: Income Distribution, Poverty and Government Policy115 Questions
Exam 35: World Trade Equilibrium112 Questions
Exam 36: Consumer Choice132 Questions
Exam 37: International Trade Restrictions109 Questions
Exam 38: World Trade Equilibrium112 Questions
Exam 39: Exchange Rates and Financial Links Between Countries132 Questions
Exam 40: International Trade Restrictions109 Questions
Exam 41: Supply: the Costs of Doing Business106 Questions
Exam 42: Exchange Rates and Financial Links Between Countries132 Questions
Exam 43: Profit Maximization122 Questions
Exam 44: Perfect Competition135 Questions
Exam 45: Monopoly118 Questions
Exam 46: Monopolistic Competition and Oligopoly111 Questions
Exam 47: Antitrust and Regulation100 Questions
Exam 48: Market Failures, Government Failures, and Rent Seeking121 Questions
Exam 49: Resource Markets112 Questions
Exam 50: The Labor Market114 Questions
Exam 51: Capital Markets100 Questions
Exam 52: The Land Market and Natural Resources55 Questions
Exam 53: Aging, Social Security and Health Care87 Questions
Exam 54: Income Distribution, Poverty and Government Policy115 Questions
Exam 55: World Trade Equilibrium112 Questions
Exam 56: International Trade Restrictions109 Questions
Exam 57: Exchange Rates and Financial Links Between Countries132 Questions
Select questions type


The following table shows the cost of producing different units of ball point pens by a firm. Table 21.1
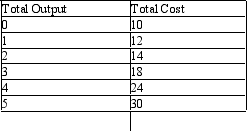 Refer to Table 21.1.What is the marginal cost of producing the fourth and the fifth unit?
 (Multiple Choice)
4.9/5  (68)
(68) The table given below shows the average total cost of production of a firm at different levels of the output. Table 21.5
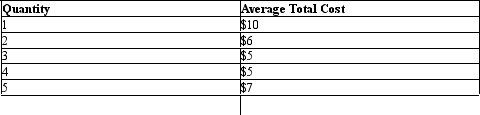 Refer to Table 21.5.At what level of production will the average total cost curve intersect the marginal cost curve?
 (Multiple Choice)
4.8/5 (76)
(76) The figure given below shows the average fixed cost (AFC)and the average variable cost (AVC)curves of a competive firm. Figure 21.1 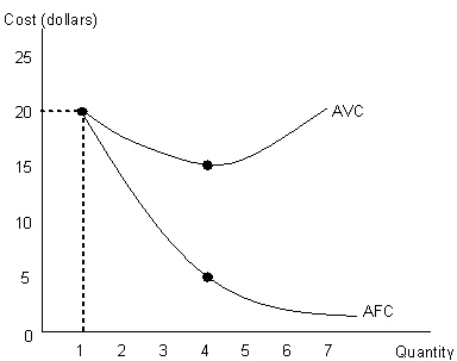 Refer to Figure 21.1.Compute the total cost of producing 4 units of the output.
 (Multiple Choice)
4.9/5 (84)
(84) Suppose that the total fixed cost of producing five sailboats is $4, 000, total variable cost is $4, 000, and the total cost of producing six sailboats is $10, 000.The marginal cost of the sixth sailboat is:
(Multiple Choice)
4.9/5 (70)
(70) If long-run costs are plotted on the vertical axis and quantity of output plotted on the horizontal axis, a line that is perfectly horizontal implies:
(Multiple Choice)
4.7/5 (69)
(69) According to economic theory, the difference between the long run and the short run is:
(Multiple Choice)
4.7/5 (70)
(70) The figure given below shows three Short Run Average Total Cost (SRATC)curves and the Long Run Average Total Cost (LRATC)curve of a firm. Figure 21.3 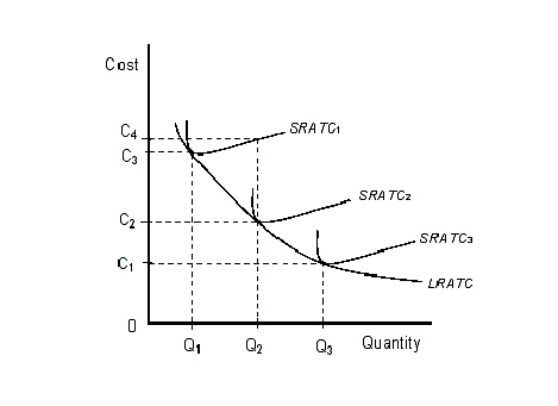 Which of the following would account for the shape of the long-run average-total-cost curve in Figure 21.3?
 (Multiple Choice)
4.9/5 (78)
(78) Which of the following is not a reason for economies of scale?
(Multiple Choice)
4.8/5 (91)
(91) If long-run costs are plotted on the vertical axis and quantity of output plotted on the horizontal axis, a positively sloped line implies _____.
(Multiple Choice)
4.8/5 (83)
(83) Why does the law of diminishing return not apply in the long run?
(Multiple Choice)
4.9/5 (86)
(86) When a firm expands in size such that its workers can specialize in any one activity, the long run average total cost of the firm gradually increases.
(True/False)
5.0/5 (70)
(70) For a steel manufacturing firm, overhead costs would include:
(Multiple Choice)
4.9/5 (74)
(74) The minimum efficient scale is the level of output where the short-run average-total-cost curve reaches its minimum point.
(True/False)
4.7/5 (75)
(75) If the cost borne by a firm when output is zero is $100 and that of producing 5 units is $250, then the variable cost of the firm is equal to $150.
(True/False)
4.8/5 (73)
(73) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)