



 Chat with AI
Exam 41: Supply: the Costs of Doing Business

Exam 1: Economics: The World Around You90 Questions
Exam 2: Choice, Opportunity Costs, and Specialization94 Questions
Exam 3: Markets, Demand and Supply, and the Price System97 Questions
Exam 5: The Market System and the Private and Public Sector97 Questions
Exam 4: Elasticity: Demand and Supply126 Questions
Exam 6: National Income Accounting104 Questions
Exam 7: an Introduction to the Foreign Exchange Market and the Balance of Payments90 Questions
Exam 8: Consumer Choice132 Questions
Exam 9: Supply: The Costs of Doing Business106 Questions
Exam 10: Unemployment and Inflation129 Questions
Exam 11: Macroeconomic Equilibrium: Aggregate Demand and Supply122 Questions
Exam 12: Profit Maximization122 Questions
Exam 13: Aggregate Expenditures115 Questions
Exam 14: Perfect Competition135 Questions
Exam 15: Income and Expenditures Equilibrium134 Questions
Exam 16: Monopoly118 Questions
Exam 17: Fiscal Policy93 Questions
Exam 18: Monopolistic Competition and Oligopoly111 Questions
Exam 19: Antitrust and Regulation100 Questions
Exam 10: Money and Banking125 Questions
Exam 21: Market Failures, Government Failures, and Rent Seeking121 Questions
Exam 22: Monetary Policy141 Questions
Exam 23: Macroeconomic Policy: Tradeoffs, Expectations, Credibility, and Sources of Business Cycles112 Questions
Exam 24: Resource Markets112 Questions
Exam 25: Macroeconomic Viewpoints: New Keynesian, Monetarist, and New Classical99 Questions
Exam 26: The Labor Market114 Questions
Exam 27: Capital Markets100 Questions
Exam 28: Economic Growth99 Questions
Exam 29: Development Economics104 Questions
Exam 30: the Land Market and Natural Resources55 Questions
Exam 31: Aging, Social Security and Health Care88 Questions
Exam 32: Globalization84 Questions
Exam 33: Elasticity: Demand and Supply126 Questions
Exam 34: Income Distribution, Poverty and Government Policy115 Questions
Exam 35: World Trade Equilibrium112 Questions
Exam 36: Consumer Choice132 Questions
Exam 37: International Trade Restrictions109 Questions
Exam 38: World Trade Equilibrium112 Questions
Exam 39: Exchange Rates and Financial Links Between Countries132 Questions
Exam 40: International Trade Restrictions109 Questions
Exam 41: Supply: the Costs of Doing Business106 Questions
Exam 42: Exchange Rates and Financial Links Between Countries132 Questions
Exam 43: Profit Maximization122 Questions
Exam 44: Perfect Competition135 Questions
Exam 45: Monopoly118 Questions
Exam 46: Monopolistic Competition and Oligopoly111 Questions
Exam 47: Antitrust and Regulation100 Questions
Exam 48: Market Failures, Government Failures, and Rent Seeking121 Questions
Exam 49: Resource Markets112 Questions
Exam 50: The Labor Market114 Questions
Exam 51: Capital Markets100 Questions
Exam 52: The Land Market and Natural Resources55 Questions
Exam 53: Aging, Social Security and Health Care87 Questions
Exam 54: Income Distribution, Poverty and Government Policy115 Questions
Exam 55: World Trade Equilibrium112 Questions
Exam 56: International Trade Restrictions109 Questions
Exam 57: Exchange Rates and Financial Links Between Countries132 Questions
Select questions type


Every firm has to bear its fixed costs even when it produces nothing.
(True/False)
4.7/5  (75)
(75) If marginal product increases with an increase in the variable input, the marginal cost must also increase as more units of the input are hired.
(True/False)
4.8/5 (79)
(79) The table given below shows the total cost of producing different units of the output by a competitive firm. Table 21.4
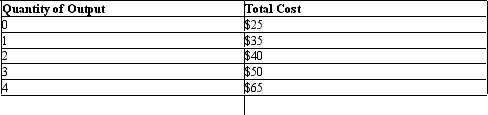 In Table 21.4, at 4 units of output,
 (Multiple Choice)
4.8/5 (76)
(76) The figure given below shows cost curves of a firm. Figure: 21.2 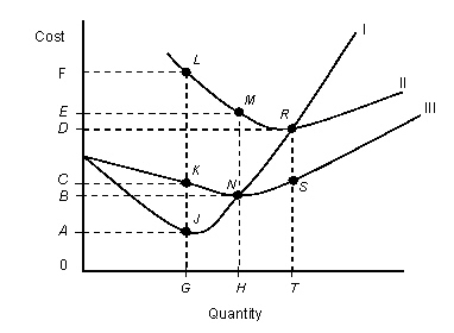 In the figure,
|: Marginal cost curve
||: Average total cost curve
|||: Average variable cost curve
Refer to Figure 21.2.At an output level of H, total fixed cost is:
In the figure,
|: Marginal cost curve
||: Average total cost curve
|||: Average variable cost curve
Refer to Figure 21.2.At an output level of H, total fixed cost is: (Multiple Choice)
4.8/5 (75)
(75) The table given below shows the average total cost of production of a firm at different levels of the output. Table 21.5
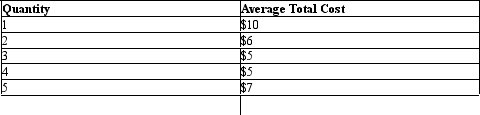 In Table 21.5, what is the total cost of producing 4 units?
 (Multiple Choice)
4.8/5 (82)
(82) "As I add more workers to the factory line, the additional output produced by each additional worker seems to decline.Eventually, the workers just get in each others' way." This statement by a factory supervisor refers to:
(Multiple Choice)
4.8/5 (90)
(90) As long as there are fixed resources, diminishing marginal returns will never exist.
(True/False)
4.8/5 (81)
(81) Assume that one laborer produces 6 units of output, two laborers produce 14 units, three produce 20 units, and four produce 24 units.If the cost is $20 per unit of labor and fixed costs are $100, what is the average total cost at 14 units of output?
(Multiple Choice)
4.7/5 (88)
(88) The table below shows the total cost of producing different units of a commodity. Table 21.2
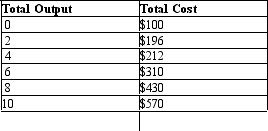 Refer to Table 21.2.If the production of 2 extra units (units 11 and 12)increases total cost by $162, then:
 (Multiple Choice)
4.8/5 (78)
(78) The marginal cost curve intersects the average total cost curve at the firm's most efficient point of production.
(True/False)
4.8/5 (87)
(87) If labor is the only variable input, an increase in the quantity of labor:
(Multiple Choice)
4.8/5 (82)
(82) The figure given below shows three Short Run Average Total Cost (SRATC)curves and the Long Run Average Total Cost (LRATC)curve of a firm. Figure 21.3 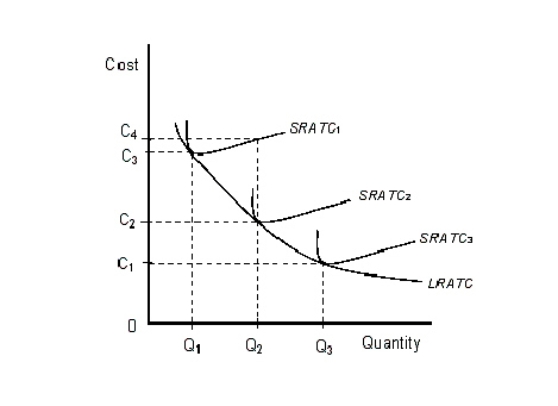 Refer to the Figure 21.3.In the long run, an increase in production from Q1 to Q3 would:
 (Multiple Choice)
4.7/5 (78)
(78) The following table shows the cost of producing different units of ball point pens by a firm. Table 21.1
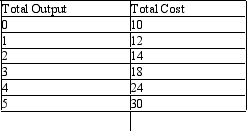 Refer to Table 21.1.What will be the average fixed cost of producing five ball point pens?
 (Multiple Choice)
4.8/5 (87)
(87) Economies and diseconomies of scale are the reasons why short-run average total cost decreases and then increases.
(True/False)
4.9/5 (78)
(78) If a firm experiences economies of scale throughout it will have a horizontal long-run average total cost curve.
(True/False)
4.8/5 (85)
(85) The long-run average total cost curve connects the lowest cost for each level of output given by the short run average total cost curves.
(True/False)
4.8/5 (90)
(90) Assume that one laborer produces 6 units of output, two laborers produce 14 units, three laborers 22 units, four laborers 24 units, and five laborers 25 units.Diminishing returns set in when the firm hires:
(Multiple Choice)
4.9/5 (71)
(71) In the oil tanker industry, large companies have lower risk and are able to optimize vessel utilization.If consolidation allows companies to lower their long-run average total costs, this is an example of:
(Multiple Choice)
4.8/5 (75)
(75) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)