



 Chat with AI
Exam 11: Technology, production, and Costs

Exam 1: Economics: Foundations and Models142 Questions
Exam 2: Trade-Offs, comparative Advantage, and the Market System152 Questions
Exam 3: Where Prices Come From: the Interaction of Demand and Supply149 Questions
Exam 4: Economic Efficiency, government Price Setting, and Taxes137 Questions
Exam 5: Externalities, environmental Policy, and Public Goods139 Questions
Exam 6: Elasticity: The Responsiveness of Demand and Supply149 Questions
Exam 7: The Economics of Health Care117 Questions
Exam 8: Firms, the Stock Market, and Corporate Governance140 Questions
Exam 9: Comparative Advantage and the Gains From International Trade124 Questions
Exam 10: Consumer Choice and Behavioral Economics154 Questions
Exam 11: Technology, production, and Costs174 Questions
Exam 12: Firms in Perfectly Competitive Markets153 Questions
Exam 13: Monopolistic Competition: The Competitive Model in a More Realistic Setting137 Questions
Exam 14: Oligopoly: Firms in Less Competitive Markets129 Questions
Exam 15: Monopoly and Antitrust Policy148 Questions
Exam 16: Pricing Strategy134 Questions
Exam 17: The Markets for Labor and Other Factors of Production149 Questions
Exam 18: Public Choice, taxes, and the Distribution of Income134 Questions
Exam 19: GDP: Measuring Total Production and Income135 Questions
Exam 20: Unemployment and Inflation148 Questions
Exam 21: Economic Growth, the Financial System, and Business Cycles130 Questions
Exam 22: Long-Run Economic Growth: Sources and Policies134 Questions
Exam 23: Aggregate Expenditure and Output in the Short Run157 Questions
Exam 24: Aggregate Demand and Aggregate Supply Analysis145 Questions
Exam 25: Money, banks, and the Federal Reserve System144 Questions
Exam 26: Monetary Policy145 Questions
Exam 27: Fiscal Policy155 Questions
Exam 28: Inflation, unemployment, and Federal Reserve Policy135 Questions
Exam 29: Macroeconomics in an Open Economy145 Questions
Exam 30: The International Financial System139 Questions
Select questions type


Figure 11-3 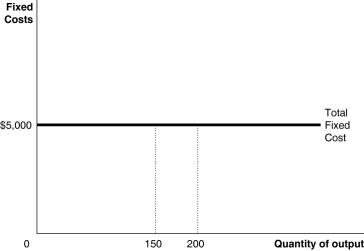 -Refer to Figure 11-3.What happens to the average fixed cost of production when the firm increases output from 150 to 200?
 (Multiple Choice)
4.8/5  (75)
(75) A firm's cost of production is determined by all of the following except
(Multiple Choice)
4.9/5 (78)
(78) A downward sloping marginal product of labor curve demonstrates the law of diminishing marginal returns.
(True/False)
4.8/5 (79)
(79) If a firm experiences positive technological change,it is able to produce more output using the same inputs.
(True/False)
4.8/5 (83)
(83) Which of the following is a factor of production that generally is fixed in the short run?
(Multiple Choice)
4.8/5 (95)
(95) Figure 11-1  -Refer to Figure 11-1.The marginal product of the 3rd worker is
 (Multiple Choice)
4.9/5 (87)
(87) Vipsana's Gyros House sells gyros.The cost of ingredients (pita,meat,spices,etc.)to make a gyro is $2.00.Vipsana pays her employees $60 per day.She also incurs a fixed cost of $120 per day.Calculate Vipsana's total cost per day when she produces 50 gyros using two workers?
(Multiple Choice)
4.9/5 (70)
(70) What is the difference between total cost and variable cost in the long run?
(Essay)
4.9/5 (68)
(68) Figure 11-1
-Refer to Figure 11-1.The marginal product of the 7th worker is
-Refer to Figure 11-1.The marginal product of the 7th worker is (Multiple Choice)
4.7/5 (69)
(69) Improvements in inventory control represent a positive technological change because they allow firms to produce the same output with fewer inputs.In recent years,many firms have adopted an inventory system in which firms accept shipments from suppliers as close as possible to the time they will be needed.Wal-Mart has been a pioneer in using inventory control systems to this in its stores.This type of inventory system is called a ________ inventory system.
(Multiple Choice)
4.9/5 (69)
(69) Red Stone Creamery currently hires 5 workers.When it added a 6th worker,its output actually fell.Which of the following statements is true?
(Multiple Choice)
4.9/5 (82)
(82) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)