



 Chat with AI
Exam 11: Technology, production, and Costs

Exam 1: Economics: Foundations and Models142 Questions
Exam 2: Trade-Offs, comparative Advantage, and the Market System152 Questions
Exam 3: Where Prices Come From: the Interaction of Demand and Supply149 Questions
Exam 4: Economic Efficiency, government Price Setting, and Taxes137 Questions
Exam 5: Externalities, environmental Policy, and Public Goods139 Questions
Exam 6: Elasticity: The Responsiveness of Demand and Supply149 Questions
Exam 7: The Economics of Health Care117 Questions
Exam 8: Firms, the Stock Market, and Corporate Governance140 Questions
Exam 9: Comparative Advantage and the Gains From International Trade124 Questions
Exam 10: Consumer Choice and Behavioral Economics154 Questions
Exam 11: Technology, production, and Costs174 Questions
Exam 12: Firms in Perfectly Competitive Markets153 Questions
Exam 13: Monopolistic Competition: The Competitive Model in a More Realistic Setting137 Questions
Exam 14: Oligopoly: Firms in Less Competitive Markets129 Questions
Exam 15: Monopoly and Antitrust Policy148 Questions
Exam 16: Pricing Strategy134 Questions
Exam 17: The Markets for Labor and Other Factors of Production149 Questions
Exam 18: Public Choice, taxes, and the Distribution of Income134 Questions
Exam 19: GDP: Measuring Total Production and Income135 Questions
Exam 20: Unemployment and Inflation148 Questions
Exam 21: Economic Growth, the Financial System, and Business Cycles130 Questions
Exam 22: Long-Run Economic Growth: Sources and Policies134 Questions
Exam 23: Aggregate Expenditure and Output in the Short Run157 Questions
Exam 24: Aggregate Demand and Aggregate Supply Analysis145 Questions
Exam 25: Money, banks, and the Federal Reserve System144 Questions
Exam 26: Monetary Policy145 Questions
Exam 27: Fiscal Policy155 Questions
Exam 28: Inflation, unemployment, and Federal Reserve Policy135 Questions
Exam 29: Macroeconomics in an Open Economy145 Questions
Exam 30: The International Financial System139 Questions
Select questions type


Figure 11-7  -Refer to Figure 11-7.The lines shown in the diagram are isocost lines.If the price of labor is $50 per unit,what is the price of capital along the isocost CE?
 (Multiple Choice)
4.8/5  (70)
(70) If average total cost is $50 and average fixed cost is $15 when output is 20 units,then the firm's total variable cost at that level of output is
(Multiple Choice)
4.9/5 (75)
(75) In the short run,marginal product of labor increases at first and then falls because
(Multiple Choice)
4.9/5 (76)
(76) If the average variable cost curve is above the marginal cost curve,then
(Multiple Choice)
4.8/5 (89)
(89) Is it possible for average total cost to be decreasing over a range of output where marginal cost is increasing? Briefly explain.
(Essay)
4.8/5 (86)
(86) Economies of scale exist as a firm increases its size in the long run because of all of the following except
(Multiple Choice)
4.9/5 (86)
(86) Which of the following are implicit costs for a typical firm?
(Multiple Choice)
4.7/5 (85)
(85) Table 11-3
 Table 11-3 shows cost data for Lotus Lanterns, a producer of whimsical night lights.
-Refer to Table 11-3.What is the variable cost of production when the firm produces 115 lanterns?
Table 11-3 shows cost data for Lotus Lanterns, a producer of whimsical night lights.
-Refer to Table 11-3.What is the variable cost of production when the firm produces 115 lanterns? (Multiple Choice)
4.9/5 (82)
(82) Figure 11-6 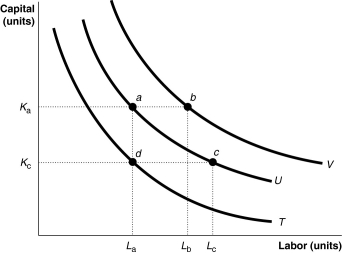 -Refer to Figure 11-6.Which of the following statements about the input combinations shown in the diagram is false?
 (Multiple Choice)
4.7/5 (81)
(81) Golda Rush quit her job as a manager for Home Depot to start her own hair dressing salon,Goldilocks.She gave up a salary of $40,000 per year,invested her savings of $30,000 (which was earning 5 percent interest)and borrowed $10,000 from a close friend,agreeing to pay 5 percent interest per year.In her first year,Golda spent $18,000 to rent a salon,hired a part-time assistant for $12,000 and incurred another $15,000 on equipment and hairdressing material.Based on this information,what is the amount of her implicit costs?
(Multiple Choice)
4.7/5 (68)
(68) As output increases,average fixed cost gets smaller and smaller.
(True/False)
4.8/5 (79)
(79) Figure 11-9  -Refer to Figure 11-9.What is the combination of inputs that produces 200 gooseberry pies at the lowest cost?
 (Multiple Choice)
4.9/5 (87)
(87) If production displays constant returns to scale,then all economies of scale have been exhausted.
(True/False)
4.8/5 (88)
(88) If the 15th unit of output has a marginal cost of $29.50 and the average cost of producing 14 units of output is $30.23,what will happen to the average cost of production if the 15th unit is produced?
(Multiple Choice)
4.9/5 (80)
(80) If,after hiring the 6th worker,a firm's output falls,then the marginal product of the 6th worker is negative.
(True/False)
5.0/5 (70)
(70) Figure 11-6
-Refer to Figure 11-6.The movement from isoquant T to isoquant U depicts
-Refer to Figure 11-6.The movement from isoquant T to isoquant U depicts (Multiple Choice)
4.8/5 (82)
(82) Which of the following would be categorized as an opportunity cost? a.not being able to spend your $10,000 savings if you sink the money in your business
B)the cost of purchasing supplies for your house-cleaning business
C)the cost of purchasing auto insurance for your dry-cleaning delivery business
A) a only
B) a and c only
C) b and c only
D) all of the above
(Not Answered)
This question doesn't have any answer yet
Economic costs of production differ from accounting costs in that
(Multiple Choice)
4.9/5 (79)
(79) The absolute value of the slope of an isocost line equals the ratio of
(Multiple Choice)
4.9/5 (79)
(79) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)