



 Chat with AI
Exam 12: Firms in Perfectly Competitive Markets

Exam 1: Economics: Foundations and Models142 Questions
Exam 2: Trade-Offs, comparative Advantage, and the Market System152 Questions
Exam 3: Where Prices Come From: the Interaction of Demand and Supply149 Questions
Exam 4: Economic Efficiency, government Price Setting, and Taxes137 Questions
Exam 5: Externalities, environmental Policy, and Public Goods139 Questions
Exam 6: Elasticity: The Responsiveness of Demand and Supply149 Questions
Exam 7: The Economics of Health Care117 Questions
Exam 8: Firms, the Stock Market, and Corporate Governance140 Questions
Exam 9: Comparative Advantage and the Gains From International Trade124 Questions
Exam 10: Consumer Choice and Behavioral Economics154 Questions
Exam 11: Technology, production, and Costs174 Questions
Exam 12: Firms in Perfectly Competitive Markets153 Questions
Exam 13: Monopolistic Competition: The Competitive Model in a More Realistic Setting137 Questions
Exam 14: Oligopoly: Firms in Less Competitive Markets129 Questions
Exam 15: Monopoly and Antitrust Policy148 Questions
Exam 16: Pricing Strategy134 Questions
Exam 17: The Markets for Labor and Other Factors of Production149 Questions
Exam 18: Public Choice, taxes, and the Distribution of Income134 Questions
Exam 19: GDP: Measuring Total Production and Income135 Questions
Exam 20: Unemployment and Inflation148 Questions
Exam 21: Economic Growth, the Financial System, and Business Cycles130 Questions
Exam 22: Long-Run Economic Growth: Sources and Policies134 Questions
Exam 23: Aggregate Expenditure and Output in the Short Run157 Questions
Exam 24: Aggregate Demand and Aggregate Supply Analysis145 Questions
Exam 25: Money, banks, and the Federal Reserve System144 Questions
Exam 26: Monetary Policy145 Questions
Exam 27: Fiscal Policy155 Questions
Exam 28: Inflation, unemployment, and Federal Reserve Policy135 Questions
Exam 29: Macroeconomics in an Open Economy145 Questions
Exam 30: The International Financial System139 Questions
Select questions type


Figure 12-7  -Refer to Figure 12-7.Suppose the prevailing price is $20 and the firm is currently producing 1,350 units.In the long-run equilibrium,
Free
(Multiple Choice)
4.9/5  (82)
(82) Correct Answer: Verified
B
The demand curve for an individual seller's product in perfect competition is
Free
(Multiple Choice)
4.9/5 (94)
(94) Correct Answer:Verified
VerifiedD
In August 2008,Ethan Nicholas developed the iShoot application for the apple iPhone 3G,and within five months had earned $800,000 from this program.By May 2009,Nicholas had dropped the price from $4.99 to $1.99 in an attempt to maintain sales.This example indicates that in a competitive market,
Free
(Multiple Choice)
4.9/5 (77)
(77) Correct Answer:Verified
VerifiedB
If a perfectly competitive firm's price is above its average total cost,the firm
(Multiple Choice)
4.8/5 (75)
(75) The price of a seller's product in perfect competition is determined by
(Multiple Choice)
4.8/5 (83)
(83) When a perfectly competitive firm finds that its market price is below its minimum average variable cost,it will sell
(Multiple Choice)
5.0/5 (88)
(88) A perfectly competitive industry achieves allocative efficiency because
(Multiple Choice)
4.9/5 (73)
(73) Assume that the medical screening industry is perfectly competitive.Consider a typical firm that is making short-run losses.Suppose the medical screening industry runs an effective advertising campaign which convinces a large number of people that yearly CT scans are critical for good health.How will this affect a typical firm that remains in the industry?
(Multiple Choice)
4.8/5 (81)
(81) Figure 12-5  Figure 12-5 shows cost and demand curves facing a typical firm in a constant-cost, perfectly competitive industry.
-Refer to Figure 12-5.What is the minimum price the firm requires to produce output?
Figure 12-5 shows cost and demand curves facing a typical firm in a constant-cost, perfectly competitive industry.
-Refer to Figure 12-5.What is the minimum price the firm requires to produce output? (Multiple Choice)
4.9/5 (81)
(81) Figure 12-8 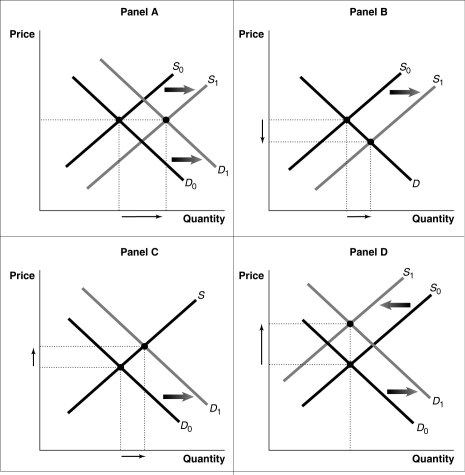 -Refer to Figure 12-8.Consider a typical firm in a perfectly competitive industry that makes short-run profits.Which of the diagrams in the figure shows the effect on the industry as it transitions to a long-run equilibrium?
 (Multiple Choice)
4.8/5 (86)
(86) Figure 12-6  Figure 12-6 shows cost and demand curves facing a profit-maximizing, perfectly competitive firm.
-Refer to Figure 12-6.At price P3,the firm would produce
Figure 12-6 shows cost and demand curves facing a profit-maximizing, perfectly competitive firm.
-Refer to Figure 12-6.At price P3,the firm would produce (Multiple Choice)
4.8/5 (80)
(80) A perfectly competitive firm produces 3,000 units of a good at a total cost of $36,000.The price of each good is $10.Calculate the firm's short-run profit or loss.
(Multiple Choice)
4.9/5 (82)
(82) The market demand curve for a perfectly competitive industry is the horizontal summation of each individual firm's demand curve.
(True/False)
4.7/5 (75)
(75) Figure 12-5
Figure 12-5 shows cost and demand curves facing a typical firm in a constant-cost, perfectly competitive industry.
-Refer to Figure 12-5.If the firm's fixed cost increases by $1,000 due to a new environmental regulation,what happens in the diagram above?
Figure 12-5 shows cost and demand curves facing a typical firm in a constant-cost, perfectly competitive industry.
-Refer to Figure 12-5.If the firm's fixed cost increases by $1,000 due to a new environmental regulation,what happens in the diagram above? (Multiple Choice)
4.8/5 (70)
(70) If,for the last unit of a good produced by a perfectly competitive firm,MR > MC,then in producing it,the firm
(Multiple Choice)
4.9/5 (76)
(76) What is meant by productive efficiency? How does a perfectly competitive firm achieve productive efficiency?
(Essay)
4.8/5 (87)
(87) Under what conditions should a competitive firm shut down in the short run?
(Essay)
4.7/5 (71)
(71) Figure 12-6
Figure 12-6 shows cost and demand curves facing a profit-maximizing, perfectly competitive firm.
-Refer to Figure 12-6.At price P4,the firm would produce
Figure 12-6 shows cost and demand curves facing a profit-maximizing, perfectly competitive firm.
-Refer to Figure 12-6.At price P4,the firm would produce (Multiple Choice)
4.9/5 (69)
(69) Figure 12-6
Figure 12-6 shows cost and demand curves facing a profit-maximizing, perfectly competitive firm.
-Refer to Figure 12-6.At price P4,the firm would
Figure 12-6 shows cost and demand curves facing a profit-maximizing, perfectly competitive firm.
-Refer to Figure 12-6.At price P4,the firm would (Multiple Choice)
4.8/5 (88)
(88) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)