



 Chat with AI
Exam 12: Firms in Perfectly Competitive Markets

Exam 1: Economics: Foundations and Models142 Questions
Exam 2: Trade-Offs, comparative Advantage, and the Market System152 Questions
Exam 3: Where Prices Come From: the Interaction of Demand and Supply149 Questions
Exam 4: Economic Efficiency, government Price Setting, and Taxes137 Questions
Exam 5: Externalities, environmental Policy, and Public Goods139 Questions
Exam 6: Elasticity: The Responsiveness of Demand and Supply149 Questions
Exam 7: The Economics of Health Care117 Questions
Exam 8: Firms, the Stock Market, and Corporate Governance140 Questions
Exam 9: Comparative Advantage and the Gains From International Trade124 Questions
Exam 10: Consumer Choice and Behavioral Economics154 Questions
Exam 11: Technology, production, and Costs174 Questions
Exam 12: Firms in Perfectly Competitive Markets153 Questions
Exam 13: Monopolistic Competition: The Competitive Model in a More Realistic Setting137 Questions
Exam 14: Oligopoly: Firms in Less Competitive Markets129 Questions
Exam 15: Monopoly and Antitrust Policy148 Questions
Exam 16: Pricing Strategy134 Questions
Exam 17: The Markets for Labor and Other Factors of Production149 Questions
Exam 18: Public Choice, taxes, and the Distribution of Income134 Questions
Exam 19: GDP: Measuring Total Production and Income135 Questions
Exam 20: Unemployment and Inflation148 Questions
Exam 21: Economic Growth, the Financial System, and Business Cycles130 Questions
Exam 22: Long-Run Economic Growth: Sources and Policies134 Questions
Exam 23: Aggregate Expenditure and Output in the Short Run157 Questions
Exam 24: Aggregate Demand and Aggregate Supply Analysis145 Questions
Exam 25: Money, banks, and the Federal Reserve System144 Questions
Exam 26: Monetary Policy145 Questions
Exam 27: Fiscal Policy155 Questions
Exam 28: Inflation, unemployment, and Federal Reserve Policy135 Questions
Exam 29: Macroeconomics in an Open Economy145 Questions
Exam 30: The International Financial System139 Questions
Select questions type


Table 12-1
 Table 12-1 shows the short-run cost data of a perfectly competitive firm that produces plastic camera cases. Assume that output can only be increased in batches of 100 units.
-Refer to Table 12-1.If the market price of each camera case is $8,what is the profit-maximizing quantity?
Table 12-1 shows the short-run cost data of a perfectly competitive firm that produces plastic camera cases. Assume that output can only be increased in batches of 100 units.
-Refer to Table 12-1.If the market price of each camera case is $8,what is the profit-maximizing quantity? (Multiple Choice)
5.0/5  (86)
(86) If,in a perfectly competitive industry,the market price facing a firm is above its average total cost at the output where marginal revenue equals marginal cost,then
(Multiple Choice)
4.8/5 (78)
(78) Using two graphs,illustrate how a positive technological change in the market for notebook computers could eliminate short-run economic profit for a firm in that market.On the first graph,use a supply and demand graph to illustrate the positive technological change.On the second graph,use demand,ATC,MC and MR curves to illustrate the elimination of economic profit resulting from the positive technological change.Explain what is taking place in each graph.
(Essay)
4.9/5 (94)
(94) Which of the following is the best example of a perfectly competitive industry?
(Multiple Choice)
4.9/5 (89)
(89) In an increasing-cost industry the long-run supply curve is upward sloping.
(True/False)
5.0/5 (72)
(72) If in the long run a firm makes zero profit,it should exit the industry.
(True/False)
4.8/5 (70)
(70) A firm's total profit can be calculated as all of the following except
(Multiple Choice)
5.0/5 (70)
(70) A perfectly competitive wheat farmer in a constant-cost industry produces 3,000 bushels of wheat at a total cost of $36,000.The prevailing market price is $15.What will happen to the market price of wheat in the long run?
(Multiple Choice)
4.7/5 (69)
(69) Figure 12-11 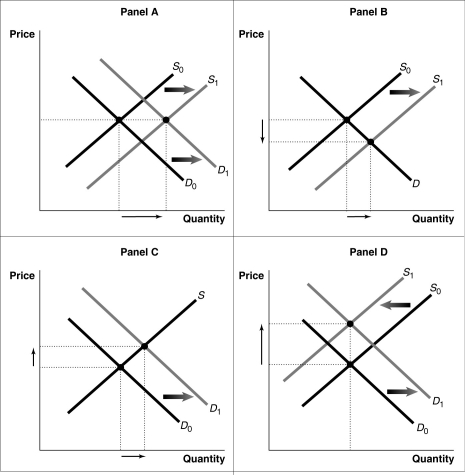 -Refer to Figure 12-11.Assume that the medical screening industry is perfectly competitive and that some firms are making short-run losses.Suppose the medical screening industry runs an effective advertising campaign which convinces a large number of people that yearly CT scans are critical for good health.Which of the diagrams in the figure best describes what happens in the industry?
 (Multiple Choice)
4.9/5 (78)
(78) Figure 12-4  Figure 12-4 shows the cost and demand curves for a profit-maximizing firm in a perfectly competitive market.
-Refer to Figure 12-4.If the market price is $30,should the firm represented in the diagram continue to stay in business?
Figure 12-4 shows the cost and demand curves for a profit-maximizing firm in a perfectly competitive market.
-Refer to Figure 12-4.If the market price is $30,should the firm represented in the diagram continue to stay in business? (Multiple Choice)
4.9/5 (80)
(80) The minimum point on the average variable cost curve is called the loss-minimizing point.
(True/False)
4.9/5 (80)
(80) Which of the following is a characteristic of an oligopolistic market structure?
(Multiple Choice)
4.8/5 (90)
(90) Figure 12-1  -Refer to Figure 12-1.If the firm is producing 200 units,
 (Multiple Choice)
4.9/5 (78)
(78) If a typical firm in a perfectly competitive industry is incurring losses,then
(Multiple Choice)
4.9/5 (69)
(69) Figure 12-5  Figure 12-5 shows cost and demand curves facing a typical firm in a constant-cost, perfectly competitive industry.
-Refer to Figure 12-5.If the market price is $20,what is the amount of the firm's profit?
Figure 12-5 shows cost and demand curves facing a typical firm in a constant-cost, perfectly competitive industry.
-Refer to Figure 12-5.If the market price is $20,what is the amount of the firm's profit? (Multiple Choice)
4.8/5 (73)
(73) A perfectly competitive firm in a constant-cost industry produces 1,000 units of a good at a total cost of $50,000.If the prevailing market price is $48,the number of firms and the industry's output will decrease in the long run.
(True/False)
4.7/5 (77)
(77) Which of the following describes a situation in which a good or service is produced at the lowest possible cost?
(Multiple Choice)
4.8/5 (74)
(74) A perfectly competitive firm's marginal revenue curve is downward sloping.
(True/False)
4.9/5 (79)
(79) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)