



 Chat with AI
Exam 12: Firms in Perfectly Competitive Markets

Exam 1: Economics: Foundations and Models142 Questions
Exam 2: Trade-Offs, comparative Advantage, and the Market System152 Questions
Exam 3: Where Prices Come From: the Interaction of Demand and Supply149 Questions
Exam 4: Economic Efficiency, government Price Setting, and Taxes137 Questions
Exam 5: Externalities, environmental Policy, and Public Goods139 Questions
Exam 6: Elasticity: The Responsiveness of Demand and Supply149 Questions
Exam 7: The Economics of Health Care117 Questions
Exam 8: Firms, the Stock Market, and Corporate Governance140 Questions
Exam 9: Comparative Advantage and the Gains From International Trade124 Questions
Exam 10: Consumer Choice and Behavioral Economics154 Questions
Exam 11: Technology, production, and Costs174 Questions
Exam 12: Firms in Perfectly Competitive Markets153 Questions
Exam 13: Monopolistic Competition: The Competitive Model in a More Realistic Setting137 Questions
Exam 14: Oligopoly: Firms in Less Competitive Markets129 Questions
Exam 15: Monopoly and Antitrust Policy148 Questions
Exam 16: Pricing Strategy134 Questions
Exam 17: The Markets for Labor and Other Factors of Production149 Questions
Exam 18: Public Choice, taxes, and the Distribution of Income134 Questions
Exam 19: GDP: Measuring Total Production and Income135 Questions
Exam 20: Unemployment and Inflation148 Questions
Exam 21: Economic Growth, the Financial System, and Business Cycles130 Questions
Exam 22: Long-Run Economic Growth: Sources and Policies134 Questions
Exam 23: Aggregate Expenditure and Output in the Short Run157 Questions
Exam 24: Aggregate Demand and Aggregate Supply Analysis145 Questions
Exam 25: Money, banks, and the Federal Reserve System144 Questions
Exam 26: Monetary Policy145 Questions
Exam 27: Fiscal Policy155 Questions
Exam 28: Inflation, unemployment, and Federal Reserve Policy135 Questions
Exam 29: Macroeconomics in an Open Economy145 Questions
Exam 30: The International Financial System139 Questions
Select questions type


Figure 12-6  Figure 12-6 shows cost and demand curves facing a profit-maximizing, perfectly competitive firm.
-Refer to Figure 12-6.At price P2,the firm would produce
Figure 12-6 shows cost and demand curves facing a profit-maximizing, perfectly competitive firm.
-Refer to Figure 12-6.At price P2,the firm would produce (Multiple Choice)
4.7/5  (75)
(75) If a perfectly competitive firm's price is less than its average total cost but greater than its average variable cost,the firm
(Multiple Choice)
4.9/5 (74)
(74) In the short run,if a firm shuts down it avoids its variable cost but not its fixed cost.
(True/False)
4.8/5 (83)
(83) All of the following can be used to compute average profit except
(Multiple Choice)
4.9/5 (66)
(66) A perfectly competitive firm's horizontal demand curve implies that the firm does not have to lower its price to sell more output.
(True/False)
4.9/5 (79)
(79) Assume the market for organic produce sold at farmers' markets is perfectly competitive.All else equal,as more farmers choose to produce and sell organic produce at farmers' markets,what is likely to happen to the equilibrium price of the produce and profits of the organic farmers in the long run?
(Multiple Choice)
4.9/5 (79)
(79) If in a perfectly competitive industry,the market price facing a firm is below its average total cost but above average variable cost at the output where marginal cost equals marginal revenue
(Multiple Choice)
5.0/5 (73)
(73) The demand curve for each seller's product in perfect competition is horizontal at the market price because
(Multiple Choice)
4.8/5 (76)
(76) An individual seller in perfect competition will not sell at a price lower than the market price because
(Multiple Choice)
4.9/5 (82)
(82) Assuming a market price of $4,fill in the columns in the following table.What is the profit-maximizing level of production? What are the two ways to determine the profit-maximizing level of production?
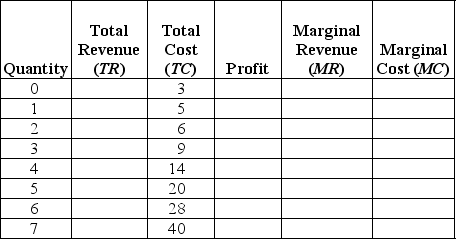
(Essay)
4.8/5 (70)
(70) Which of the following is not true for a firm in perfect competition?
(Multiple Choice)
4.9/5 (103)
(103) A perfectly competitive wheat farmer in a constant-cost industry produces 1,000 bushels of wheat at a total cost of $50,000.The prevailing market price is $48.What will happen to the market price of wheat in the long run?
(Multiple Choice)
4.7/5 (77)
(77) Figure 12-5  Figure 12-5 shows cost and demand curves facing a typical firm in a constant-cost, perfectly competitive industry.
-Refer to Figure 12-5.The firm's manager suggests that the firm's goal should be to maximize average profit.In that case,what is the output level and what is the average profit that will achieve the manager's goal?
Figure 12-5 shows cost and demand curves facing a typical firm in a constant-cost, perfectly competitive industry.
-Refer to Figure 12-5.The firm's manager suggests that the firm's goal should be to maximize average profit.In that case,what is the output level and what is the average profit that will achieve the manager's goal? (Multiple Choice)
5.0/5 (85)
(85) Figure 12-5
Figure 12-5 shows cost and demand curves facing a typical firm in a constant-cost, perfectly competitive industry.
-Refer to Figure 12-5.The figure shows the cost structure of a firm in a perfectly competitive market.If the firm's fixed cost increases by $1,000 due to a new environmental regulation,what happens to its profit-maximizing output level?
Figure 12-5 shows cost and demand curves facing a typical firm in a constant-cost, perfectly competitive industry.
-Refer to Figure 12-5.The figure shows the cost structure of a firm in a perfectly competitive market.If the firm's fixed cost increases by $1,000 due to a new environmental regulation,what happens to its profit-maximizing output level? (Multiple Choice)
4.8/5 (63)
(63) Figure 12-2  -Refer to Figure 12-2.Why is the total revenue curve a ray from the origin?
 (Multiple Choice)
4.9/5 (77)
(77) A perfectly competitive firm breaks even at a price equal to its minimum average total cost.
(True/False)
4.8/5 (68)
(68) Assume that the LCD and plasma television sets industry is perfectly competitive.Suppose a producer develops a successful innovation that enables it to lower its cost of production.What happens in the short run and in the long run?
(Multiple Choice)
4.8/5 (75)
(75) Maximizing average profit is equivalent to maximizing total profit.
(True/False)
4.8/5 (79)
(79) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)