



 Chat with AI
Exam 12: Firms in Perfectly Competitive Markets

Exam 1: Economics: Foundations and Models142 Questions
Exam 2: Trade-Offs, comparative Advantage, and the Market System152 Questions
Exam 3: Where Prices Come From: the Interaction of Demand and Supply149 Questions
Exam 4: Economic Efficiency, government Price Setting, and Taxes137 Questions
Exam 5: Externalities, environmental Policy, and Public Goods139 Questions
Exam 6: Elasticity: The Responsiveness of Demand and Supply149 Questions
Exam 7: The Economics of Health Care117 Questions
Exam 8: Firms, the Stock Market, and Corporate Governance140 Questions
Exam 9: Comparative Advantage and the Gains From International Trade124 Questions
Exam 10: Consumer Choice and Behavioral Economics154 Questions
Exam 11: Technology, production, and Costs174 Questions
Exam 12: Firms in Perfectly Competitive Markets153 Questions
Exam 13: Monopolistic Competition: The Competitive Model in a More Realistic Setting137 Questions
Exam 14: Oligopoly: Firms in Less Competitive Markets129 Questions
Exam 15: Monopoly and Antitrust Policy148 Questions
Exam 16: Pricing Strategy134 Questions
Exam 17: The Markets for Labor and Other Factors of Production149 Questions
Exam 18: Public Choice, taxes, and the Distribution of Income134 Questions
Exam 19: GDP: Measuring Total Production and Income135 Questions
Exam 20: Unemployment and Inflation148 Questions
Exam 21: Economic Growth, the Financial System, and Business Cycles130 Questions
Exam 22: Long-Run Economic Growth: Sources and Policies134 Questions
Exam 23: Aggregate Expenditure and Output in the Short Run157 Questions
Exam 24: Aggregate Demand and Aggregate Supply Analysis145 Questions
Exam 25: Money, banks, and the Federal Reserve System144 Questions
Exam 26: Monetary Policy145 Questions
Exam 27: Fiscal Policy155 Questions
Exam 28: Inflation, unemployment, and Federal Reserve Policy135 Questions
Exam 29: Macroeconomics in an Open Economy145 Questions
Exam 30: The International Financial System139 Questions
Select questions type


Figure 12-5  Figure 12-5 shows cost and demand curves facing a typical firm in a constant-cost, perfectly competitive industry.
-Refer to Figure 12-5.The firm's manager suggests that the firm's goal should be to maximize average profit.If the firm does this,what is the amount of profit that it will earn?
Figure 12-5 shows cost and demand curves facing a typical firm in a constant-cost, perfectly competitive industry.
-Refer to Figure 12-5.The firm's manager suggests that the firm's goal should be to maximize average profit.If the firm does this,what is the amount of profit that it will earn? (Multiple Choice)
4.9/5  (82)
(82) Figure 12-13 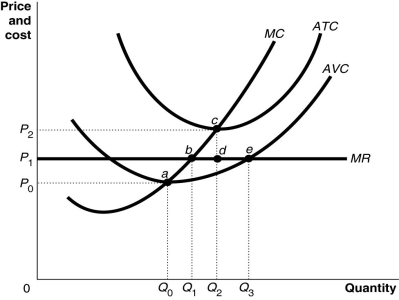 -Refer to Figure 12-13.If the market price is P1,what is the allocatively efficient output level?
 (Multiple Choice)
4.8/5 (74)
(74) Figure 12-6  Figure 12-6 shows cost and demand curves facing a profit-maximizing, perfectly competitive firm.
-Refer to Figure 12-6.At price P1,the firm would
Figure 12-6 shows cost and demand curves facing a profit-maximizing, perfectly competitive firm.
-Refer to Figure 12-6.At price P1,the firm would (Multiple Choice)
4.8/5 (89)
(89) Figure 12-6
Figure 12-6 shows cost and demand curves facing a profit-maximizing, perfectly competitive firm.
-Refer to Figure 12-6.Identify the short-run shut down point for the firm.
Figure 12-6 shows cost and demand curves facing a profit-maximizing, perfectly competitive firm.
-Refer to Figure 12-6.Identify the short-run shut down point for the firm. (Multiple Choice)
4.7/5 (80)
(80) Apple introduced its iPhone 3G in July 2008 and within a month sales had topped 3 million units.By April 2009,more than 25,000 apps for the iPhone 3G were available in the iTunes store,an indication that in a competitive market
(Multiple Choice)
4.8/5 (82)
(82) Suppose Veronica sells teapots in the perfectly competitive teapot market.Her output per day and her costs are as follows:
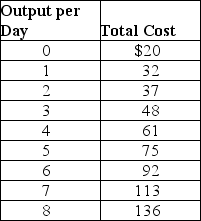 Suppose the current equilibrium price in the teapot market is $20.To maximize profit,how many teapots will Veronica produce,what price will she charge,and how much profit (or loss)will she make? Draw a graph to illustrate your answer.Your graph should include Veronica's demand,ATC,AVC,MC,and MR curves,the price she is charging,the quantity she is producing,and the area representing her profit (or loss).
 (Essay)
4.9/5 (73)
(73) If a firm in a perfectly competitive industry introduces a lower-cost way of producing an existing product,the firm will be able to earn economic profits in the long run.
(True/False)
4.8/5 (82)
(82) Figure 12-6
Figure 12-6 shows cost and demand curves facing a profit-maximizing, perfectly competitive firm.
-Refer to Figure 12-6.Identify the firm's short-run supply curve.
Figure 12-6 shows cost and demand curves facing a profit-maximizing, perfectly competitive firm.
-Refer to Figure 12-6.Identify the firm's short-run supply curve. (Multiple Choice)
4.8/5 (92)
(92) If total variable cost exceeds total revenue at all output levels,a perfectly competitive firm
(Multiple Choice)
4.9/5 (74)
(74) Firms in perfect competition produce the allocatively efficient output in the short run and in the long run.
(True/False)
4.8/5 (75)
(75) Figure 12-6
Figure 12-6 shows cost and demand curves facing a profit-maximizing, perfectly competitive firm.
-Refer to Figure 12-6.At price P3,the firm would
Figure 12-6 shows cost and demand curves facing a profit-maximizing, perfectly competitive firm.
-Refer to Figure 12-6.At price P3,the firm would (Multiple Choice)
4.9/5 (71)
(71) Figure 12-4  Figure 12-4 shows the cost and demand curves for a profit-maximizing firm in a perfectly competitive market.
-Refer to Figure 12-4.If the market price is $30,the firm's profit-maximizing output level is
Figure 12-4 shows the cost and demand curves for a profit-maximizing firm in a perfectly competitive market.
-Refer to Figure 12-4.If the market price is $30,the firm's profit-maximizing output level is (Multiple Choice)
4.9/5 (60)
(60) Figure 12-2  -Refer to Figure 12-2.What happens if the firm produces more than Q4 units?
 (Multiple Choice)
4.8/5 (69)
(69) Assume that price is greater than average variable cost.If a perfectly competitive seller is producing at an output where price is $11 and the marginal cost is $14.54,then to maximize profits the firm should
(Multiple Choice)
4.7/5 (78)
(78) An increase in demand for U.S.farm exports will ________ the market prices for these exports and ________ economic profit in these markets.
(Multiple Choice)
4.9/5 (81)
(81) Figure 12-4
Figure 12-4 shows the cost and demand curves for a profit-maximizing firm in a perfectly competitive market.
-Refer to Figure 12-4.If the market price is $30 and if the firm is producing output,what is the amount of its total variable cost?
Figure 12-4 shows the cost and demand curves for a profit-maximizing firm in a perfectly competitive market.
-Refer to Figure 12-4.If the market price is $30 and if the firm is producing output,what is the amount of its total variable cost? (Multiple Choice)
4.8/5 (89)
(89) Figure 12-6
Figure 12-6 shows cost and demand curves facing a profit-maximizing, perfectly competitive firm.
-Refer to Figure 12-6.At price P2,the firm would
Figure 12-6 shows cost and demand curves facing a profit-maximizing, perfectly competitive firm.
-Refer to Figure 12-6.At price P2,the firm would (Multiple Choice)
4.8/5 (77)
(77) Figure 12-9 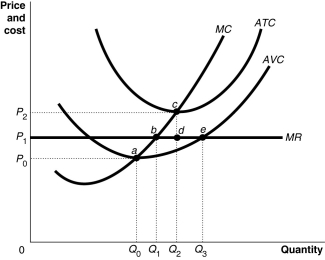 -Refer to Figure 12-9.Suppose the prevailing price is P1 and the firm is currently producing its loss-minimizing quantity.In the long-run equilibrium,
 (Multiple Choice)
4.7/5 (81)
(81) Suppose Veronica sells teapots in the perfectly competitive teapot market.Her output per day and her costs are as follows:
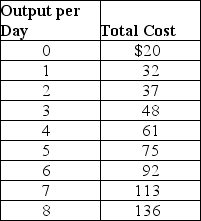 Suppose the current equilibrium price in the teapot market is $15.To maximize profit,how many teapots will Veronica produce,what price will she charge,and how much profit (or loss)will she make? Draw a graph to illustrate your answer.Your graph should include Veronica's demand,ATC,AVC,MC,and MR curves,the price she is charging,the quantity she is producing,and the area representing her profit (or loss).
 (Essay)
4.8/5 (76)
(76) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)