



 Chat with AI
Exam 7: Consumers, Producers and the Efficiency of Markets

Exam 1: Ten Lessons From Economics146 Questions
Exam 2: Thinking Like an Economist133 Questions
Exam 3: Interdependence and the Gains From Trade139 Questions
Exam 4: The Market Forces of Supply and Demand215 Questions
Exam 5: Elasticity and Its Application178 Questions
Exam 6: Supply, Demand and Government Policies145 Questions
Exam 7: Consumers, Producers and the Efficiency of Markets171 Questions
Exam 8: Application: the Costs of Taxation135 Questions
Exam 9: Application: International Trade151 Questions
Exam 10: Externalities199 Questions
Exam 11: Public Goods and Common Resources178 Questions
Exam 12: The Design of the Tax System154 Questions
Exam 13: The Costs of Production191 Questions
Exam 14: Firms in Competitive Markets198 Questions
Exam 15: Monopoly212 Questions
Exam 16: Monopolistic Competition212 Questions
Exam 17: Business Strategy and Oligopoly179 Questions
Exam 18: Competition Policy103 Questions
Exam 19: The Markets for the Factors of Production214 Questions
Exam 20: Earnings, Unions and Discrimination201 Questions
Exam 21: Income Inequity and Poverty111 Questions
Exam 22: The Theory of Consumer Choice158 Questions
Exam 23: Frontiers of Microeconomics111 Questions
Exam 24: Measuring a Nations Income51 Questions
Exam 25: Measuring the Cost of Living55 Questions
Exam 26: Production and Growth62 Questions
Exam 27: Saving, Investment and the Financial System62 Questions
Exam 28: The Natural Rate of Unemployment58 Questions
Exam 29: The Monetary System66 Questions
Exam 30: Inflation: Its Causes and Costs74 Questions
Exam 31: Open-Economy Macroeconomics: Basic Concepts68 Questions
Exam 32: A Macroeconomic Theory of the Open Economy61 Questions
Exam 33: Aggregate Demand and Aggregate Supply81 Questions
Exam 34: The Influence of Monetary and Fiscal Policy on Aggregate Demand73 Questions
Exam 35: The Short-Run Trade-Off Between Inflation and Unemployment57 Questions
Exam 36: Global Financial Crisis of 2008 and Beyond37 Questions
Exam 37: Five Debates Over Macroeconomic Policy38 Questions
Select questions type


Suppose that the demand for coffee rises.This means that the producer surplus for coffee will:
(Multiple Choice)
4.8/5  (78)
(78) The "generalised price" of a ticket is the sum of the monetary price of the ticket (the amount you pay in dollars) plus the other costs of obtaining that ticket (such as waiting in line).It can be written as:
Generalised Price = Monetary price + time standing in line.Suppose everyone has the same opportunity cost of time.If there are laws against scalping, will tickets go to those individuals who value the ticket the most when we use generalised price? (HINT: Suppose there is one ticket left for a concert for $40, and person A values that ticket at $50 and person B at $60.Who will buy the ticket?)
(Essay)
4.8/5 (75)
(75) Table 7-3
Market supply and demand for good X
-Refer to Table 7-3.The equilibrium or market-clearing price is:
(Multiple Choice)
4.7/5 (83)
(83) An allocation of resources that maximises total surplus is said to be equitable.
(True/False)
4.9/5 (93)
(93) Table 7-2
The costs of five possible sellers
-Refer to Table 7-2.If the market price is $8, the total cost in the market will be:
(Multiple Choice)
4.9/5 (70)
(70) In a perfectly competitive market, consumer surplus and producer surplus are equal.
(True/False)
4.7/5 (87)
(87) For producers, the willingness to sell is equivalent to the marginal cost of the product.
(True/False)
4.9/5 (63)
(63) Michele is willing to pay $12 to see St Trinians for the fourth time.She finds a theatre showing St Trinians for $12.00.Michele's consumer surplus is:
(Multiple Choice)
4.9/5 (80)
(80) 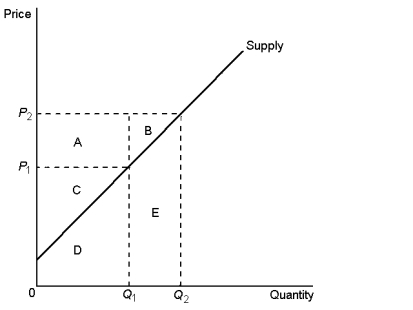 -According to Graph 7-3, area B represents:
Would a market that was characterised by unregulated pollution be classed as efficient? Why or why not?
(Essay)
4.8/5 (79)
(79) Table 7-7
Price of pizza Quantity of pizza demanded Fred Frieda >\ 15 0 0 \ 14 1 0 \ 13 3 1 \ 12 5 3 \ 11 7 5 \ 10 9 7 \ 9 11 9 Antonio's Pizza
Price Quantity supplied \ 15 28 \ 14 24 \ 13 20 \ 12 16 \ 11 12 \ 10 8 \ 9 4 <\ 9 0
-Based on Table 7-7, if Fred and Frieda are the only buyers in the pizza market and Antonio's is the only seller, what is the:
a.market equilibrium price?
b.market equilibrium quantity?
c.total consumer surplus at the market equilibrium?
d.total producer surplus at the market equilibrium?
e.total benefit to society of this market?
(Short Answer)
4.9/5 (83)
(83) Even though participants in the economy are motivated by self-interest, the 'invisible hand' of the marketplace guides this self-interest into promoting general economic wellbeing.
(True/False)
4.8/5 (78)
(78) Graph 7-4 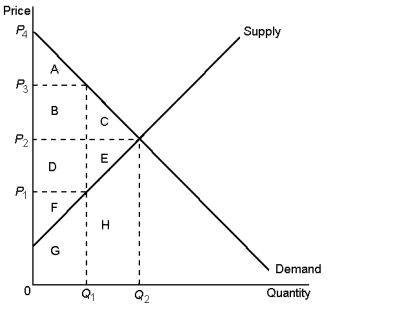 -In Graph 7-4, the efficient price-quantity combination is:
 (Multiple Choice)
4.7/5 (69)
(69) If demand increases, the price of a product, as well as producer surplus:
(Multiple Choice)
4.9/5 (79)
(79) If Dale sells a shirt for $80 and his producer surplus from the sale is $13, his cost must have been:
(Multiple Choice)
4.7/5 (97)
(97) Graph 7-4
-In Graph 7-4, at the market-clearing equilibrium, total surplus is represented by the area:
-In Graph 7-4, at the market-clearing equilibrium, total surplus is represented by the area: (Multiple Choice)
4.8/5 (83)
(83) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)