



 Chat with AI
Exam 13: The Costs of Production

Exam 1: Ten Lessons From Economics146 Questions
Exam 2: Thinking Like an Economist133 Questions
Exam 3: Interdependence and the Gains From Trade139 Questions
Exam 4: The Market Forces of Supply and Demand215 Questions
Exam 5: Elasticity and Its Application178 Questions
Exam 6: Supply, Demand and Government Policies145 Questions
Exam 7: Consumers, Producers and the Efficiency of Markets171 Questions
Exam 8: Application: the Costs of Taxation135 Questions
Exam 9: Application: International Trade151 Questions
Exam 10: Externalities199 Questions
Exam 11: Public Goods and Common Resources178 Questions
Exam 12: The Design of the Tax System154 Questions
Exam 13: The Costs of Production191 Questions
Exam 14: Firms in Competitive Markets198 Questions
Exam 15: Monopoly212 Questions
Exam 16: Monopolistic Competition212 Questions
Exam 17: Business Strategy and Oligopoly179 Questions
Exam 18: Competition Policy103 Questions
Exam 19: The Markets for the Factors of Production214 Questions
Exam 20: Earnings, Unions and Discrimination201 Questions
Exam 21: Income Inequity and Poverty111 Questions
Exam 22: The Theory of Consumer Choice158 Questions
Exam 23: Frontiers of Microeconomics111 Questions
Exam 24: Measuring a Nations Income51 Questions
Exam 25: Measuring the Cost of Living55 Questions
Exam 26: Production and Growth62 Questions
Exam 27: Saving, Investment and the Financial System62 Questions
Exam 28: The Natural Rate of Unemployment58 Questions
Exam 29: The Monetary System66 Questions
Exam 30: Inflation: Its Causes and Costs74 Questions
Exam 31: Open-Economy Macroeconomics: Basic Concepts68 Questions
Exam 32: A Macroeconomic Theory of the Open Economy61 Questions
Exam 33: Aggregate Demand and Aggregate Supply81 Questions
Exam 34: The Influence of Monetary and Fiscal Policy on Aggregate Demand73 Questions
Exam 35: The Short-Run Trade-Off Between Inflation and Unemployment57 Questions
Exam 36: Global Financial Crisis of 2008 and Beyond37 Questions
Exam 37: Five Debates Over Macroeconomic Policy38 Questions
Select questions type


Suppose an apple orchardist increases the number of fruit pickers hired for a season.The number of apple trees remains the same.As a result the orchardist's:
(Multiple Choice)
5.0/5  (66)
(66) The marginal cost curve intersects the average variable cost curve at the minimum of the average variable cost curve.
(True/False)
4.9/5 (81)
(81) Even if a firm was to produce nothing, it still incurs some variable costs in the short-run.
(True/False)
4.8/5 (81)
(81) How would a production function that exhibits decreasing marginal product affect the shape of the total cost curve? Explain or draw a graph.
(Essay)
4.9/5 (78)
(78) Which of the following describes the marginal product of labour?
(Multiple Choice)
4.7/5 (80)
(80) Graph 13-3 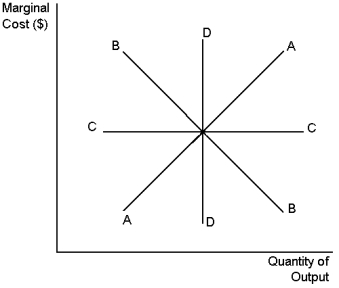 -Refer to Graph 13-3.If marginal cost is rising, then:
 (Multiple Choice)
4.7/5 (84)
(84) As a firm moves along its long-run average cost curve, it is adjusting the size of its factory to the quantity of production.
(True/False)
4.9/5 (93)
(93) The short run is defined as the period of time in which all factors of production are fixed.
(True/False)
4.9/5 (73)
(73) The marginal cost curve can rise even if the average total cost is falling.
(True/False)
5.0/5 (74)
(74) Graph 13-4 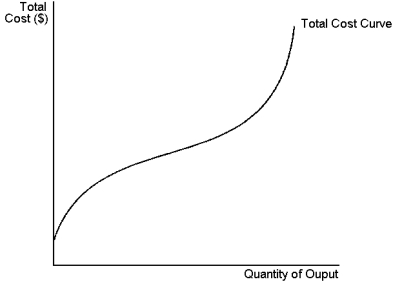 -Refer to Graph 13-4.Which of the following can be inferred from the figure shown?
(i) marginal costs vary for different levels of output
(ii) diminishing marginal product does not occur directly after the first worker
(iii) marginal product of the second worker exceeds that of the first
-Refer to Graph 13-4.Which of the following can be inferred from the figure shown?
(i) marginal costs vary for different levels of output
(ii) diminishing marginal product does not occur directly after the first worker
(iii) marginal product of the second worker exceeds that of the first (Multiple Choice)
4.9/5 (85)
(85) The firm's total cost can be used to determine both the firm's average total cost and its marginal cost.
(True/False)
4.9/5 (77)
(77) A second or third worker may have a higher marginal product than the first worker in certain circumstances.
(True/False)
4.9/5 (79)
(79) Dave is majoring in computer information development at University of Environmental Sustainability.While he has been attending university, Dave has started a computer consulting business to help local residents set up a local skill-sharing network.Dave charges $25 per hour for his consulting services.Dave also works five hours a week for the Arts Faculty to maintain its departmental web page.The Arts Faculty pays Dave $20 per hour.From this information we can conclude that:
(Multiple Choice)
4.9/5 (67)
(67) Table 13-3
Consider the following firm which makes high-performance racing bicycles.All costs are given in dollars.Output is shown on a monthly basis.The firm's fixed costs include a rent of $800 and a lease cost of $400 per month. 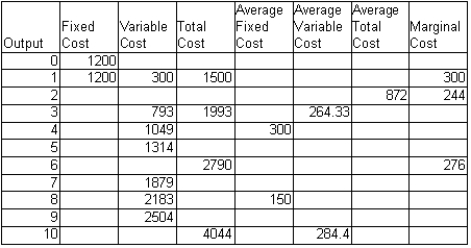 -Refer to Table 13-3.What is the marginal cost of producing the tenth bicycle in a given month?
 (Multiple Choice)
4.8/5 (86)
(86) The amount of money that a firm pays to buy inputs is called:
(Multiple Choice)
4.8/5 (82)
(82) Economists normally assume that a firm would?
(i) sell a higher output if this would increase revenue
(ii) sell a lower output and collect less revenue, if this would increase profit
(iii) sell a higher output and incur more costs, if this would increase profit
(Multiple Choice)
4.8/5 (81)
(81) A firm's variable costs divided by the quantity produced is the:
(Multiple Choice)
4.8/5 (89)
(89) Diminishing marginal product causes the average variable cost curve to:
(Multiple Choice)
4.7/5 (92)
(92) Graph 13-2 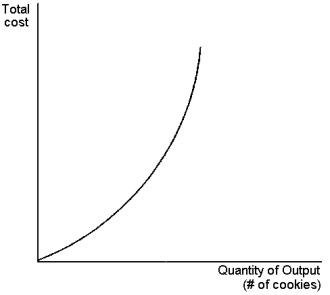 This graph depicts a total cost function for a firm that produces cookies.Use the graph to answer the following question(s).
-Refer to Graph 13-2.Identify the true statements from the list below.(i) the marginal cost of cookie production is increasing
(ii) cookie production exhibits diminishing marginal product
(iii) the slope of the production function increases as quantity of inputs increase
This graph depicts a total cost function for a firm that produces cookies.Use the graph to answer the following question(s).
-Refer to Graph 13-2.Identify the true statements from the list below.(i) the marginal cost of cookie production is increasing
(ii) cookie production exhibits diminishing marginal product
(iii) the slope of the production function increases as quantity of inputs increase (Multiple Choice)
4.9/5 (60)
(60) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)