



 Chat with AI
Exam 8: Market Failure Versus Government Failure

Exam 1: Economics and Economic Reasoning158 Questions
Exam 2: The Production Possibility Model, Trade, and Globalization133 Questions
Exam 3: Economic Institutions163 Questions
Exam 4: Supply and Demand182 Questions
Exam 5: Using Supply and Demand163 Questions
Exam 6: Describing Supply and Demand: Elasticities216 Questions
Exam 7: Taxation and Government Intervention201 Questions
Exam 8: Market Failure Versus Government Failure197 Questions
Exam 9: Comparative Advantage, Exchange Rates, and Globalization118 Questions
Exam 10: International Trade Policy99 Questions
Exam 11: Production and Cost Analysis I194 Questions
Exam 12: Production and Cost Analysis II152 Questions
Exam 13: Perfect Competition170 Questions
Exam 14: Monopoly and Monopolistic Competition274 Questions
Exam 15: Oligopoly and Antitrust Policy142 Questions
Exam 16: Real-World Competition and Technology108 Questions
Exam 17: Work and the Labor Market150 Questions
Exam 18: Who Gets What the Distribution of Income131 Questions
Exam 19: The Logic of Individual Choice: the Foundation of Supply and Demand170 Questions
Exam 20: Game Theory, Strategic Decision Making, and Behavioral Economics103 Questions
Exam 21: Thinking Like a Modern Economist97 Questions
Exam 22: Behavioral Economics and Modern Economic Policy126 Questions
Exam 23: Microeconomic Policy, Economic Reasoning, and Beyond134 Questions
Exam 24: Economic Growth, Business Cycles, and Unemployment124 Questions
Exam 25: Measuring and Describing the Aggregate Economy229 Questions
Exam 26: The Keynesian Short-Run Policy Model: Demand-Side Policies220 Questions
Exam 27: The Classical Long-Run Policy Model: Growth and Supply-Side Policies133 Questions
Exam 28: The Financial Sector and the Economy214 Questions
Exam 29: Monetary Policy243 Questions
Exam 30: Financial Crises, Panics, and Unconventional Monetary Policy109 Questions
Exam 31: Deficits and Debt: the Austerity Debate150 Questions
Exam 32: The Fiscal Policy Dilemma119 Questions
Exam 33: Jobs and Unemployment78 Questions
Exam 34: Inflation, Deflation, and Macro Policy175 Questions
Exam 35: International Financial Policy211 Questions
Exam 36: Macro Policy in a Global Setting134 Questions
Exam 37: Structural Stagnation and Globalization125 Questions
Exam 38: Macro Policy in Developing Countries142 Questions
Select questions type


An economist argues that the states that have spent the most on higher education in the last 25 years have experienced the least economic growth. One might conclude that higher education:
(Multiple Choice)
4.9/5  (87)
(87) When negative externalities are present, market failure often occurs because:
(Multiple Choice)
5.0/5 (75)
(75) Economists generally prefer direct regulation to incentive-based programs because explicit regulation tends to be more efficient.
(True/False)
4.8/5 (86)
(86) At one time many economists were suspicious of brand names. They saw them as a barrier to entry with no benefits to consumers. In the 1970s economists began to see a possible benefit of brand names to consumers. They discovered that brand names were a way to:
(Multiple Choice)
4.9/5 (87)
(87) What is the adverse selection problem? Give an example in the market for used cars or health insurance.
(Essay)
5.0/5 (75)
(75) The following table shows four firms, the amount each pollutes, the marginal cost for each firm to clean up pollution, and the total cost to each firm of eliminating all pollution. Firm Total Discharge (in tons) Marginal Cost of Cleanup (per tan) Total Cost of Cleanup A 60 \ 5.00 \ 300 B 70 \ 8.00 \ 560 C 80 \ 7.50 \ 600 D 90 \ 4.00 \ 360 The total discharge of these four companies is 300 tons. Assume there is no one else who pollutes. Suppose that the government gives each company a pollution permit equal to 50 percent of its present discharge. However, companies are allowed to reduce pollution more than 50 percent and sell their permit or reduce less than 50 percent and buy a permit from another company. If firms maximize profits, what would happen?
(Multiple Choice)
5.0/5 (84)
(84) Refer to the graph shown. The price and quantity that would prevail if all social costs and benefits were taken into account is: 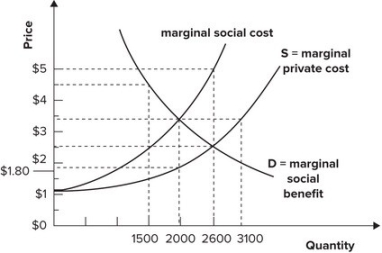
(Multiple Choice)
5.0/5 (63)
(63) Refer to the graph shown, which shows the demand and supply for a new vaccine against the common cold. Suppose once vaccinated, a person cannot catch a cold or give a cold to someone else. As a result, the marginal social benefit curve will: 
(Multiple Choice)
4.9/5 (84)
(84) Refer to the following graph.  Assuming a marginal cost external to the trade equals the tax shown in the graph, the market price necessary to induce consumers to purchase the efficient quantity each year is:
 (Multiple Choice)
4.9/5 (88)
(88) Which of the following is not a characteristic of a public good?
(Multiple Choice)
4.9/5 (82)
(82) If the marginal benefit of one more unit of a public good is $500 for Sam and $800 for Alex, the social benefit of one more unit of a public good is:
(Multiple Choice)
4.8/5 (82)
(82) The following table shows four firms, the amount each pollutes, the marginal cost for each firm to clean up pollution, and the total cost to each firm of eliminating all pollution. Firm Total Discharge (in tons) Marginal Cost of Cleanup (per tan) Total Cost of Cleanup A 60 \ 5.00 \ 300 B 70 \ 8.00 \ 560 C 80 \ 7.50 \ 600 D 90 \ 4.00 \ 360 The total discharge of these four companies is 300 tons. Assume there is no one else who pollutes. If the government establishes an effluent fee of $7.00 per ton, how much tax would firms pay to the government?
(Multiple Choice)
4.8/5 (89)
(89) If a corrective tax on gasoline results in the efficient output of gasoline by internalizing negative externalities associated with pollution:
(Multiple Choice)
4.9/5 (85)
(85) In 1990, the Clean Air Act was amended to place a national cap on sulfur dioxide emissions, giving electric utilities an allowance of a set amount of emissions and allowing the utilities to trade their allowances. This type of plan is:
(Multiple Choice)
4.8/5 (79)
(79) In a tax incentive program, the person who conserves the most pays:
(Multiple Choice)
4.8/5 (81)
(81) Refer to the following graph.  The point on the graph corresponding to the socially optimal output per year and the price sellers must receive to make that amount available is shown by point:
 (Multiple Choice)
4.7/5 (80)
(80) Some economists believe that the market will not solve all problems. They are referring to:
(Multiple Choice)
4.8/5 (86)
(86) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)