



 Chat with AI
Exam 12: Production and Cost Analysis II

Exam 1: Economics and Economic Reasoning158 Questions
Exam 2: The Production Possibility Model, Trade, and Globalization133 Questions
Exam 3: Economic Institutions163 Questions
Exam 4: Supply and Demand182 Questions
Exam 5: Using Supply and Demand163 Questions
Exam 6: Describing Supply and Demand: Elasticities216 Questions
Exam 7: Taxation and Government Intervention201 Questions
Exam 8: Market Failure Versus Government Failure197 Questions
Exam 9: Comparative Advantage, Exchange Rates, and Globalization118 Questions
Exam 10: International Trade Policy99 Questions
Exam 11: Production and Cost Analysis I194 Questions
Exam 12: Production and Cost Analysis II152 Questions
Exam 13: Perfect Competition170 Questions
Exam 14: Monopoly and Monopolistic Competition274 Questions
Exam 15: Oligopoly and Antitrust Policy142 Questions
Exam 16: Real-World Competition and Technology108 Questions
Exam 17: Work and the Labor Market150 Questions
Exam 18: Who Gets What the Distribution of Income131 Questions
Exam 19: The Logic of Individual Choice: the Foundation of Supply and Demand170 Questions
Exam 20: Game Theory, Strategic Decision Making, and Behavioral Economics103 Questions
Exam 21: Thinking Like a Modern Economist97 Questions
Exam 22: Behavioral Economics and Modern Economic Policy126 Questions
Exam 23: Microeconomic Policy, Economic Reasoning, and Beyond134 Questions
Exam 24: Economic Growth, Business Cycles, and Unemployment124 Questions
Exam 25: Measuring and Describing the Aggregate Economy229 Questions
Exam 26: The Keynesian Short-Run Policy Model: Demand-Side Policies220 Questions
Exam 27: The Classical Long-Run Policy Model: Growth and Supply-Side Policies133 Questions
Exam 28: The Financial Sector and the Economy214 Questions
Exam 29: Monetary Policy243 Questions
Exam 30: Financial Crises, Panics, and Unconventional Monetary Policy109 Questions
Exam 31: Deficits and Debt: the Austerity Debate150 Questions
Exam 32: The Fiscal Policy Dilemma119 Questions
Exam 33: Jobs and Unemployment78 Questions
Exam 34: Inflation, Deflation, and Macro Policy175 Questions
Exam 35: International Financial Policy211 Questions
Exam 36: Macro Policy in a Global Setting134 Questions
Exam 37: Structural Stagnation and Globalization125 Questions
Exam 38: Macro Policy in Developing Countries142 Questions
Select questions type


Which of the following provides the best explanation for diseconomies of scale?
(Multiple Choice)
4.9/5  (85)
(85) Technical efficiency in production means a given level of output is produced with the minimum amount of inputs.
(True/False)
4.7/5 (91)
(91) To manufacture 1,000 pairs of shoes in a week, a firm must use at least 1,500 workers and 5 machines or 100 machines and 150 workers. Which method can be technically efficient?
(Multiple Choice)
4.9/5 (68)
(68) Economies of scale occur when a firm's long-run average total cost curve is:
(Multiple Choice)
4.9/5 (86)
(86) Refer to the graph shown. A firm planning to produce 1,500 units of output would choose the scale of operation represented by: 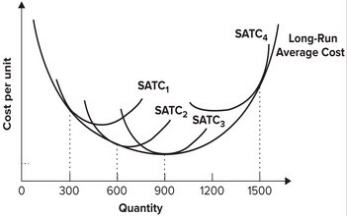
(Multiple Choice)
4.7/5 (70)
(70) 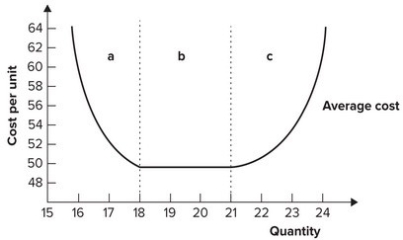
The upward-sloping portion of the long-run average total cost curve is caused by:
(Multiple Choice)
4.8/5 (83)
(83) The level of production that minimizes long-run average total costs is referred to as the:
(Multiple Choice)
4.8/5 (83)
(83) Which of the following provides the best explanation for constant returns to scale?
(Multiple Choice)
5.0/5 (81)
(81) A firm can use 50 workers and 10 machines, 70 workers and 9 machines, or 75 workers and 9 machines to produce 40 chairs. If each worker costs $20 and each machine is rented for $500, the economically efficient input combination is:
(Multiple Choice)
4.9/5 (90)
(90) Consider the following Long Run Average Total Cost (LRATC)curve diagram: 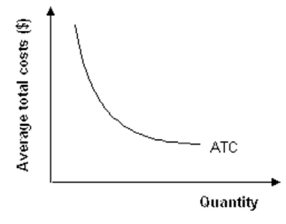 How will this diagram change (if at all)if the firm's workers "learn by doing"? Illustrate your answer with a diagram.
 (Essay)
4.8/5 (80)
(80) The minimum efficient level of production refers to the production level in the long run that spreads setup costs out just enough to make production profitable.
(True/False)
4.8/5 (77)
(77) The long-run average cost curve is tangent to the short-run average total cost curve at the minimum point of the short-run average total cost curve when the:
(Multiple Choice)
4.7/5 (86)
(86) The long-run average cost curve is horizontal when production exhibits:
(Multiple Choice)
4.8/5 (85)
(85) The relationship between long-run and short-run average total costs is known as the:
(Multiple Choice)
4.9/5 (72)
(72) If labor costs $10 per unit and machines rent for $20 apiece, the slope of an isocost line might imply a substitution of:
(Multiple Choice)
4.9/5 (76)
(76) What is an entrepreneur and what are the things that the entrepreneur must do to translate the cost of production into supply? Why is there a scarcity of entrepreneurial talent?
(Essay)
4.9/5 (66)
(66) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)