



 Chat with AI
Exam 16: Monopoly

Exam 1: Economics: The World Around You90 Questions
Exam 2: Choice, Opportunity Costs, and Specialization94 Questions
Exam 3: Markets, Demand and Supply, and the Price System97 Questions
Exam 5: The Market System and the Private and Public Sector97 Questions
Exam 4: Elasticity: Demand and Supply126 Questions
Exam 6: National Income Accounting104 Questions
Exam 7: an Introduction to the Foreign Exchange Market and the Balance of Payments90 Questions
Exam 8: Consumer Choice132 Questions
Exam 9: Supply: The Costs of Doing Business106 Questions
Exam 10: Unemployment and Inflation129 Questions
Exam 11: Macroeconomic Equilibrium: Aggregate Demand and Supply122 Questions
Exam 12: Profit Maximization122 Questions
Exam 13: Aggregate Expenditures115 Questions
Exam 14: Perfect Competition135 Questions
Exam 15: Income and Expenditures Equilibrium134 Questions
Exam 16: Monopoly118 Questions
Exam 17: Fiscal Policy93 Questions
Exam 18: Monopolistic Competition and Oligopoly111 Questions
Exam 19: Antitrust and Regulation100 Questions
Exam 10: Money and Banking125 Questions
Exam 21: Market Failures, Government Failures, and Rent Seeking121 Questions
Exam 22: Monetary Policy141 Questions
Exam 23: Macroeconomic Policy: Tradeoffs, Expectations, Credibility, and Sources of Business Cycles112 Questions
Exam 24: Resource Markets112 Questions
Exam 25: Macroeconomic Viewpoints: New Keynesian, Monetarist, and New Classical99 Questions
Exam 26: The Labor Market114 Questions
Exam 27: Capital Markets100 Questions
Exam 28: Economic Growth99 Questions
Exam 29: Development Economics104 Questions
Exam 30: the Land Market and Natural Resources55 Questions
Exam 31: Aging, Social Security and Health Care88 Questions
Exam 32: Globalization84 Questions
Exam 33: Elasticity: Demand and Supply126 Questions
Exam 34: Income Distribution, Poverty and Government Policy115 Questions
Exam 35: World Trade Equilibrium112 Questions
Exam 36: Consumer Choice132 Questions
Exam 37: International Trade Restrictions109 Questions
Exam 38: World Trade Equilibrium112 Questions
Exam 39: Exchange Rates and Financial Links Between Countries132 Questions
Exam 40: International Trade Restrictions109 Questions
Exam 41: Supply: the Costs of Doing Business106 Questions
Exam 42: Exchange Rates and Financial Links Between Countries132 Questions
Exam 43: Profit Maximization122 Questions
Exam 44: Perfect Competition135 Questions
Exam 45: Monopoly118 Questions
Exam 46: Monopolistic Competition and Oligopoly111 Questions
Exam 47: Antitrust and Regulation100 Questions
Exam 48: Market Failures, Government Failures, and Rent Seeking121 Questions
Exam 49: Resource Markets112 Questions
Exam 50: The Labor Market114 Questions
Exam 51: Capital Markets100 Questions
Exam 52: The Land Market and Natural Resources55 Questions
Exam 53: Aging, Social Security and Health Care87 Questions
Exam 54: Income Distribution, Poverty and Government Policy115 Questions
Exam 55: World Trade Equilibrium112 Questions
Exam 56: International Trade Restrictions109 Questions
Exam 57: Exchange Rates and Financial Links Between Countries132 Questions
Select questions type


The figures given below represent the revenue curves of a monopolist. Figure 10.2  TR: Total revenue curve
AR: Average revenue curve
MR: Marginal revenue curve
Refer to Figure 10.2.If the output at E is 600 units, then the output at B is _____ units.(We know that the slope of the marginal revenue curve is twice the slope of the average revenue curve. )
TR: Total revenue curve
AR: Average revenue curve
MR: Marginal revenue curve
Refer to Figure 10.2.If the output at E is 600 units, then the output at B is _____ units.(We know that the slope of the marginal revenue curve is twice the slope of the average revenue curve. ) (Multiple Choice)
4.7/5  (72)
(72) The price charged by a monopolist is the point on the demand curve that corresponds to the output where marginal revenue equals marginal cost.
(True/False)
4.9/5 (79)
(79) When long-run average costs are declining for the entire range of demand, the firm is known as a(n):
(Multiple Choice)
5.0/5 (87)
(87) Perfect competition provides one model in which there are many firms with no barriers to entry.If perfect competition as a model lies on one extreme, the model that lies on the opposite extreme is:
(Multiple Choice)
4.9/5 (78)
(78) A monopolist enjoys the least market power compared to the other market structures.
(True/False)
4.9/5 (77)
(77) The following figures show the demand and cost curves of a perfectly competitive and a monopoly firm respectively. Figure 10.7  D: Average Revenue
AC: Average cost
MC: Marginal cost
MR: Marginal cost
Calculate the deadweight loss in Figure 10.6, if the perfectly competitive industry is monopolized after it had been producing an output of 10, 000 units?
D: Average Revenue
AC: Average cost
MC: Marginal cost
MR: Marginal cost
Calculate the deadweight loss in Figure 10.6, if the perfectly competitive industry is monopolized after it had been producing an output of 10, 000 units? (Multiple Choice)
4.7/5 (76)
(76) Grocery store coupons, mail-in rebates, senior discounts, and in-state versus out-of-state tuition fees are all examples of:
(Multiple Choice)
4.8/5 (63)
(63) The table given below shows the price, marginal revenue and marginal cost of a monopolist at different levels of the output.The firm does not incur a fixed cost of production. Table 10.4
 Refer to Table 10.4 and calculate the total revenue earned by the monopolist at the profit maximizing level of output.
 (Multiple Choice)
4.8/5 (86)
(86) The figure given below shows the cost and revenue curves of a monopolist. Figure 10.9 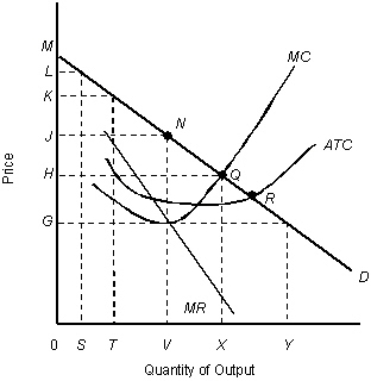 D: Average revenue
MR: Marginal revenue
ATC: Average total cost
MC: Marginal cost
In Figure 10.9, what is the consumer surplus at the profit-maximizing levels of output and price?
D: Average revenue
MR: Marginal revenue
ATC: Average total cost
MC: Marginal cost
In Figure 10.9, what is the consumer surplus at the profit-maximizing levels of output and price? (Multiple Choice)
4.7/5 (75)
(75) The following figure shows the revenue and cost curves of a monopolist. Figure 10.3  D: Average Revenue
MR: Marginal Revenue
ATC: Average Total Cost
MC: marginal Cost
Consider the monopolist described in the Figure 10.3.If the firm engages in profit-maximizing behavior, economic profit per unit of output will be:
D: Average Revenue
MR: Marginal Revenue
ATC: Average Total Cost
MC: marginal Cost
Consider the monopolist described in the Figure 10.3.If the firm engages in profit-maximizing behavior, economic profit per unit of output will be: (Multiple Choice)
4.9/5 (82)
(82) Under price discrimination, a monopolist equates the marginal cost with the average revenues in different markets.
(True/False)
4.9/5 (69)
(69) Economies of scale, control over a scarce input, and patents are all examples of barriers to entry.
(True/False)
4.9/5 (80)
(80) If an industry experiences economies of scale in production, then entry into the market by other firms is easy.
(True/False)
4.7/5 (75)
(75) If a monopolist is producing the output level at which price equals average total cost in the short run, then the firm is earning a normal profit.
(True/False)
4.8/5 (84)
(84) The table given below shows the prices charged and marginal cost incurred by a monopolist for different units of the output. Table 10.3
 Assume that the firm described in Table 10.2 is incurring a total cost of $7, 000 at the profit-maximizing output level.The firm will
 (Multiple Choice)
4.8/5 (66)
(66) Which of the following is an industry without significant barriers to entry?
(Multiple Choice)
4.9/5 (76)
(76) The perfectly competitive market structure results in economic efficiency because:
(Multiple Choice)
4.9/5 (79)
(79) The table given below shows the price charged by a firm and the marginal cost incurred by it for the different levels of the output. Table 10.2
 Assume that the firm described in Table 10.2 is incurring a total cost of $25 at the profit-maximizing output level.The firm will:
 (Multiple Choice)
4.9/5 (97)
(97) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)