



 Chat with AI
Exam 36: Consumer Choice

Exam 1: Economics: The World Around You90 Questions
Exam 2: Choice, Opportunity Costs, and Specialization94 Questions
Exam 3: Markets, Demand and Supply, and the Price System97 Questions
Exam 5: The Market System and the Private and Public Sector97 Questions
Exam 4: Elasticity: Demand and Supply126 Questions
Exam 6: National Income Accounting104 Questions
Exam 7: an Introduction to the Foreign Exchange Market and the Balance of Payments90 Questions
Exam 8: Consumer Choice132 Questions
Exam 9: Supply: The Costs of Doing Business106 Questions
Exam 10: Unemployment and Inflation129 Questions
Exam 11: Macroeconomic Equilibrium: Aggregate Demand and Supply122 Questions
Exam 12: Profit Maximization122 Questions
Exam 13: Aggregate Expenditures115 Questions
Exam 14: Perfect Competition135 Questions
Exam 15: Income and Expenditures Equilibrium134 Questions
Exam 16: Monopoly118 Questions
Exam 17: Fiscal Policy93 Questions
Exam 18: Monopolistic Competition and Oligopoly111 Questions
Exam 19: Antitrust and Regulation100 Questions
Exam 10: Money and Banking125 Questions
Exam 21: Market Failures, Government Failures, and Rent Seeking121 Questions
Exam 22: Monetary Policy141 Questions
Exam 23: Macroeconomic Policy: Tradeoffs, Expectations, Credibility, and Sources of Business Cycles112 Questions
Exam 24: Resource Markets112 Questions
Exam 25: Macroeconomic Viewpoints: New Keynesian, Monetarist, and New Classical99 Questions
Exam 26: The Labor Market114 Questions
Exam 27: Capital Markets100 Questions
Exam 28: Economic Growth99 Questions
Exam 29: Development Economics104 Questions
Exam 30: the Land Market and Natural Resources55 Questions
Exam 31: Aging, Social Security and Health Care88 Questions
Exam 32: Globalization84 Questions
Exam 33: Elasticity: Demand and Supply126 Questions
Exam 34: Income Distribution, Poverty and Government Policy115 Questions
Exam 35: World Trade Equilibrium112 Questions
Exam 36: Consumer Choice132 Questions
Exam 37: International Trade Restrictions109 Questions
Exam 38: World Trade Equilibrium112 Questions
Exam 39: Exchange Rates and Financial Links Between Countries132 Questions
Exam 40: International Trade Restrictions109 Questions
Exam 41: Supply: the Costs of Doing Business106 Questions
Exam 42: Exchange Rates and Financial Links Between Countries132 Questions
Exam 43: Profit Maximization122 Questions
Exam 44: Perfect Competition135 Questions
Exam 45: Monopoly118 Questions
Exam 46: Monopolistic Competition and Oligopoly111 Questions
Exam 47: Antitrust and Regulation100 Questions
Exam 48: Market Failures, Government Failures, and Rent Seeking121 Questions
Exam 49: Resource Markets112 Questions
Exam 50: The Labor Market114 Questions
Exam 51: Capital Markets100 Questions
Exam 52: The Land Market and Natural Resources55 Questions
Exam 53: Aging, Social Security and Health Care87 Questions
Exam 54: Income Distribution, Poverty and Government Policy115 Questions
Exam 55: World Trade Equilibrium112 Questions
Exam 56: International Trade Restrictions109 Questions
Exam 57: Exchange Rates and Financial Links Between Countries132 Questions
Select questions type


Suppose the prices of goods X, Y, and Z are $4, $1, and $5, respectively, and the last unit purchased of good X has a marginal utility MUx = 16 utils.At the point of equilibrium, the marginal utility of the last unit purchased of goods Y and Z will be:
(Multiple Choice)
4.8/5  (83)
(83) As a consumer eats additional pieces of pizza, total utility will _____.
(Multiple Choice)
4.8/5 (86)
(86) It is often observed that, over the same period of time and for the same good, marginal utility declines rapidly for some consumers and very little for others.This observation illustrates:
(Multiple Choice)
4.8/5 (81)
(81) The below figure shows the various combinations of the goods X and Y that yield different levels of utility. Figure 6.3 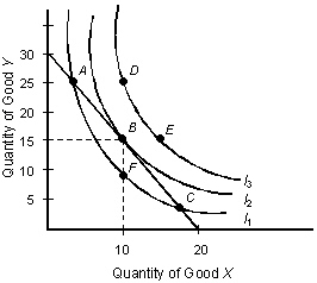 Refer to Figure 6.3.The consumer prefers _____ to _____.
 (Multiple Choice)
5.0/5 (75)
(75) In economic theory, the idea of the equimarginal principle, or consumer equilibrium, means:
(Multiple Choice)
4.8/5 (78)
(78) According to neuroeconomists, the limbic portion of the brain called the amygdala is more primitive and deals with emotion.
(True/False)
4.9/5 (83)
(83) An "all you can eat" restaurant illustrates the economic principle:
(Multiple Choice)
4.7/5 (75)
(75) The below indifference map shows the various combinations of hours of music and apples that yield different levels of utility. Figure 6.1 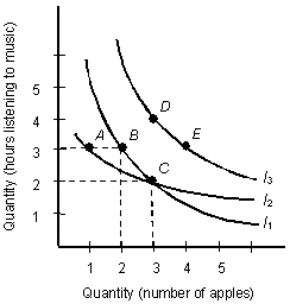 According to indifference curve I1 in Figure 6.1, for each extra apple the consumer eats, he or she must simultaneously sacrifice ____ of listening to music to keep total utility constant.
 (Multiple Choice)
4.9/5 (79)
(79) Which of the following statements about marginal utility is correct?
(Multiple Choice)
4.8/5 (74)
(74) The principle that people would rather leave things as they are is called _____.
(Multiple Choice)
4.7/5 (75)
(75) Consumer equilibrium exists when the marginal utility per dollar of expenditure is the same for all goods and services.
(True/False)
4.8/5 (78)
(78) In the theory of utility, it is assumed that marginal utility:
(Multiple Choice)
4.9/5 (70)
(70) The _____ effect indicates that an individual's income can buy more of all goods when the price of one good declines, everything else held constant.
(Multiple Choice)
4.9/5 (83)
(83) When attempting to explain why a consumer purchases a Ford automobile instead of a Honda automobile or a Compaq computer instead of an IBM computer, an economist would assert:
(Multiple Choice)
4.9/5 (72)
(72) When marginal utility is negative, total utility is _____.
(Multiple Choice)
4.9/5 (84)
(84) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)