



 Chat with AI
Exam 36: Consumer Choice

Exam 1: Economics: The World Around You90 Questions
Exam 2: Choice, Opportunity Costs, and Specialization94 Questions
Exam 3: Markets, Demand and Supply, and the Price System97 Questions
Exam 5: The Market System and the Private and Public Sector97 Questions
Exam 4: Elasticity: Demand and Supply126 Questions
Exam 6: National Income Accounting104 Questions
Exam 7: an Introduction to the Foreign Exchange Market and the Balance of Payments90 Questions
Exam 8: Consumer Choice132 Questions
Exam 9: Supply: The Costs of Doing Business106 Questions
Exam 10: Unemployment and Inflation129 Questions
Exam 11: Macroeconomic Equilibrium: Aggregate Demand and Supply122 Questions
Exam 12: Profit Maximization122 Questions
Exam 13: Aggregate Expenditures115 Questions
Exam 14: Perfect Competition135 Questions
Exam 15: Income and Expenditures Equilibrium134 Questions
Exam 16: Monopoly118 Questions
Exam 17: Fiscal Policy93 Questions
Exam 18: Monopolistic Competition and Oligopoly111 Questions
Exam 19: Antitrust and Regulation100 Questions
Exam 10: Money and Banking125 Questions
Exam 21: Market Failures, Government Failures, and Rent Seeking121 Questions
Exam 22: Monetary Policy141 Questions
Exam 23: Macroeconomic Policy: Tradeoffs, Expectations, Credibility, and Sources of Business Cycles112 Questions
Exam 24: Resource Markets112 Questions
Exam 25: Macroeconomic Viewpoints: New Keynesian, Monetarist, and New Classical99 Questions
Exam 26: The Labor Market114 Questions
Exam 27: Capital Markets100 Questions
Exam 28: Economic Growth99 Questions
Exam 29: Development Economics104 Questions
Exam 30: the Land Market and Natural Resources55 Questions
Exam 31: Aging, Social Security and Health Care88 Questions
Exam 32: Globalization84 Questions
Exam 33: Elasticity: Demand and Supply126 Questions
Exam 34: Income Distribution, Poverty and Government Policy115 Questions
Exam 35: World Trade Equilibrium112 Questions
Exam 36: Consumer Choice132 Questions
Exam 37: International Trade Restrictions109 Questions
Exam 38: World Trade Equilibrium112 Questions
Exam 39: Exchange Rates and Financial Links Between Countries132 Questions
Exam 40: International Trade Restrictions109 Questions
Exam 41: Supply: the Costs of Doing Business106 Questions
Exam 42: Exchange Rates and Financial Links Between Countries132 Questions
Exam 43: Profit Maximization122 Questions
Exam 44: Perfect Competition135 Questions
Exam 45: Monopoly118 Questions
Exam 46: Monopolistic Competition and Oligopoly111 Questions
Exam 47: Antitrust and Regulation100 Questions
Exam 48: Market Failures, Government Failures, and Rent Seeking121 Questions
Exam 49: Resource Markets112 Questions
Exam 50: The Labor Market114 Questions
Exam 51: Capital Markets100 Questions
Exam 52: The Land Market and Natural Resources55 Questions
Exam 53: Aging, Social Security and Health Care87 Questions
Exam 54: Income Distribution, Poverty and Government Policy115 Questions
Exam 55: World Trade Equilibrium112 Questions
Exam 56: International Trade Restrictions109 Questions
Exam 57: Exchange Rates and Financial Links Between Countries132 Questions
Select questions type


The law of diminishing marginal utility states that as additional units are consumed, satisfaction per unit will decline.
(True/False)
4.8/5  (63)
(63) The additional satisfaction that a consumer receives from one more unit of a good or service is known as _____.
(Multiple Choice)
4.9/5 (76)
(76) Derek has $1 to spend at the grocery store.An apple, an orange, and a banana cost $.50 each.If Derek's MUA/PA (ratio of marginal utility to price)of an apple is 45, MUO/PO of an orange is 38, and MUB/PB of a banana is 52, he will purchase a(n)_____ first and a(n)_____ second.
(Multiple Choice)
4.9/5 (76)
(76) The theory of bounded rationality states that it is likely for consumers to have perfect information.
(True/False)
4.7/5 (89)
(89) The below figure shows the various combinations of the goods X and Y that yield different levels of utility. Figure 6.3 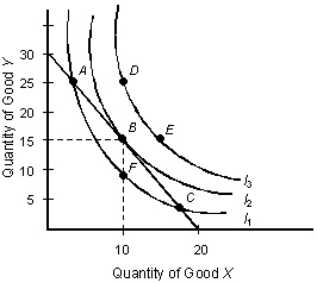 In Figure 6.3, if the price of one unit of good X and good Y is $30 and $20, respectively, the consumer's income is _____.
 (Multiple Choice)
4.7/5 (74)
(74) As you move along an indifference curve, your total utility increases or decreases depending on whether it's an upward or downward movement.
(True/False)
4.9/5 (69)
(69) If a good is free, a rational consumer will continue to consume that good, irrespective of its marginal utility.
(True/False)
4.9/5 (96)
(96) Jason is trying to decide whether to buy a bagel or a muffin for breakfast.The bagel costs $.50 and has a marginal utility of 5.The muffin costs $1 and has a marginal utility of 20.Which should he buy, and why?
(Multiple Choice)
4.8/5 (79)
(79) Suppose the price of beef declines by $0.50 per pound at the supermarket.Consumers of beef immediately increase their purchases of beef.This illustrates:
(Multiple Choice)
4.7/5 (87)
(87) When a good becomes more expensive, it yields less satisfaction per dollar, so consumers buy less of it and more of other goods.This is called the _____ effect.
(Multiple Choice)
4.9/5 (82)
(82) A utility-maximizing consumer always purchases a good that yields the greatest average utility per dollar of expenditure.
(True/False)
4.8/5 (84)
(84) Suppose that apples and bananas both cost the same, but the marginal utility of bananas is twice as high as that for apples.This implies the consumer should purchase more apples and fewer bananas in order to maximize utility.
(True/False)
4.7/5 (81)
(81) When economists describe the theory of consumer choice, they
(Multiple Choice)
4.8/5 (62)
(62) In labor markets, a change in the wage rate has both an income and a substitution effect.An increase in wages causes an increase in real income but at the same time it increases the relative price of leisure for the worker.If the increase in the wage rate causes an individual to work less:
(Multiple Choice)
4.9/5 (95)
(95) The below figure shows the various combinations of the goods X and Y that yield different levels of utility. Figure 6.3 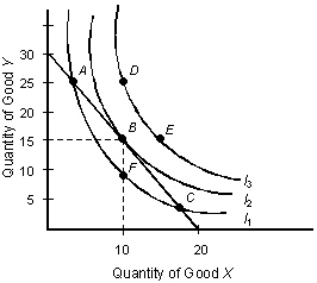 In Figure 6.3, the consumer is in equilibrium at point:
 (Multiple Choice)
4.9/5 (78)
(78) Neuroeconomics suggests that the frontal lobe carries out most decision making and strategic thinking takes place in the prefrontal cortex.
(True/False)
4.9/5 (73)
(73) If all consumers had identical preferences, then their marginal utility schedules would be the same.
(True/False)
4.8/5 (82)
(82) Which of the following statements concerning income and substitution effects is nottrue?
(Multiple Choice)
4.9/5 (94)
(94) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)