



 Chat with AI
Exam 5: Externalities, environmental Policy, and Public Goods

Exam 1: Economics: Foundations and Models447 Questions
Exam 2: Trade-Offs, comparative Advantage, and the Market System492 Questions
Exam 3: Where Prices Come From: the Interaction of Demand and Supply476 Questions
Exam 4: Economic Efficiency, government Price Setting, and Taxes420 Questions
Exam 5: Externalities, environmental Policy, and Public Goods263 Questions
Exam 6: Elasticity: the Responsiveness of Demand and Supply294 Questions
Exam 7: The Economics of Health Care338 Questions
Exam 8: Firms,the Stock Market,and Corporate Governance522 Questions
Exam 9: Comparative Advantage and the Gains From International Trade377 Questions
Exam 10: Consumer Choice and Behavioral Economics300 Questions
Exam 11: Technology,production,and Costs327 Questions
Exam 12: Firms in Perfectly Competitive Markets296 Questions
Exam 13: Monopolistic Competition: the Competitive Model in a More Realistic Setting272 Questions
Exam 14: Oligopoly: Firms in Less Competitive Markets258 Questions
Exam 15: Monopoly and Antitrust Policy279 Questions
Exam 16: Pricing Strategy261 Questions
Exam 17: The Markets for Labor and Other Factors of Production281 Questions
Exam 18: Public Choice, taxes, and the Distribution of Income258 Questions
Exam 19: Gdp: Measuring Total Production and Income261 Questions
Exam 20: Unemployment and Inflation291 Questions
Exam 21: Economic Growth, the Financial System, and Business Cycles253 Questions
Exam 22: Long-Run Economic Growth: Sources and Policies262 Questions
Exam 23: Aggregate Expenditure and Output in the Short Run301 Questions
Exam 24: Aggregate Demand and Aggregate Supply Analysis286 Questions
Exam 25: Money,banks,and the Federal Reserve System281 Questions
Exam 26: Monetary Policy275 Questions
Exam 27: Fiscal Policy306 Questions
Exam 28: Inflation, unemployment, and Federal Reserve Policy257 Questions
Exam 29: Macroeconomics in an Open Economy278 Questions
Exam 30: The International Financial System258 Questions
Select questions type


The marginal private cost of a good or service is the cost borne by the producer.
(True/False)
4.9/5  (80)
(80) When products that create positive externalities are produced,at the market equilibrium output,the social benefit generated by consuming the product exceeds the private benefit.
(True/False)
4.7/5 (72)
(72) Assume that production from an electric utility caused acid rain and that the government imposed a tax on the utility equal to the cost of the acid rain.This is an example of
(Multiple Choice)
4.9/5 (79)
(79) Some policymakers have argued that products like cigarettes,alcohol,and sweetened soda generate negative externalities in consumption.All else equal,if the government decided to impose a tax on soda,the equilibrium quantity of soda would ________ and the equilibrium price of soda would ________.
(Multiple Choice)
4.8/5 (84)
(84) An important difference between the demand for a private good and the demand for a public good is that
(Multiple Choice)
4.8/5 (71)
(71)  Companies producing toilet paper bleach the paper to make it white.The bleach is discharged into rivers and lakes and causes substantial environmental damage.Figure 5-9 illustrates the situation in the toilet paper market.
-Refer to Figure 5-9.Let's suppose the government imposes a tax of $50 per unit of toilet paper to bring about the efficient level of production.What happens to the market price of toilet paper?
Companies producing toilet paper bleach the paper to make it white.The bleach is discharged into rivers and lakes and causes substantial environmental damage.Figure 5-9 illustrates the situation in the toilet paper market.
-Refer to Figure 5-9.Let's suppose the government imposes a tax of $50 per unit of toilet paper to bring about the efficient level of production.What happens to the market price of toilet paper? (Multiple Choice)
4.8/5 (68)
(68) Which of the following describes how a negative externality affects a competitive market?
(Multiple Choice)
4.8/5 (82)
(82)  Figure 5-2 shows a market with a negative externality.
-Refer to Figure 5-2.The true marginal cost of the last unit produced is represented by the price
Figure 5-2 shows a market with a negative externality.
-Refer to Figure 5-2.The true marginal cost of the last unit produced is represented by the price (Multiple Choice)
4.8/5 (72)
(72) Governments can increase the consumption of a product that creates positive externalities by
(Multiple Choice)
4.9/5 (81)
(81) 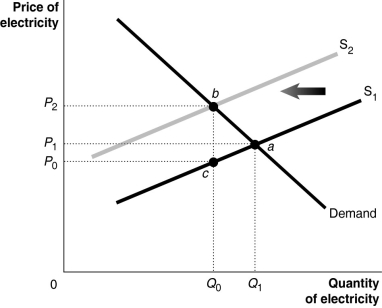 Coal burning utilities release sulfur dioxide and nitric acid which react with water to produce acid rain.Acid rain damages trees and crops and kills fish.Because the utilities do not bear the cost of the acid rain,they overproduce the quantity of electricity.This is illustrated in Figure 5-11.
-Refer to Figure 5-11.S1 represents the supply curve that reflects the private cost of production and S2 represents the supply curve that reflects the social cost of production.One way to internalize the external cost generated by utilities is to impose a Pigovian tax on the production of electricity.What is the size of the Pigovian tax that will internalize the cost of the externality?
Coal burning utilities release sulfur dioxide and nitric acid which react with water to produce acid rain.Acid rain damages trees and crops and kills fish.Because the utilities do not bear the cost of the acid rain,they overproduce the quantity of electricity.This is illustrated in Figure 5-11.
-Refer to Figure 5-11.S1 represents the supply curve that reflects the private cost of production and S2 represents the supply curve that reflects the social cost of production.One way to internalize the external cost generated by utilities is to impose a Pigovian tax on the production of electricity.What is the size of the Pigovian tax that will internalize the cost of the externality? (Multiple Choice)
4.9/5 (80)
(80) For-profit producers will produce only private goods because
(Multiple Choice)
4.9/5 (92)
(92) The Coase Theorem asserts that government intervention is a prerequisite for addressing externality problems.
(True/False)
4.9/5 (79)
(79) If there is pollution in producing a product,then the market equilibrium price
(Multiple Choice)
4.8/5 (92)
(92) For the Coase theorem to work there must be clear assignment of property rights.
(True/False)
4.9/5 (80)
(80)  Suppose there are several paper mills producing paper for a market.These mills,located upstream from a fishing village,discharge a large amount of wastewater into the river.The waste material affects the number of fish in the river and the use of the river for recreation and as a public water supply source.Figure 5-4 shows the paper market.Use this Figure to answer the following question(s).
-Refer to Figure 5-4.What does S1 represent?
Suppose there are several paper mills producing paper for a market.These mills,located upstream from a fishing village,discharge a large amount of wastewater into the river.The waste material affects the number of fish in the river and the use of the river for recreation and as a public water supply source.Figure 5-4 shows the paper market.Use this Figure to answer the following question(s).
-Refer to Figure 5-4.What does S1 represent? (Multiple Choice)
4.8/5 (86)
(86) If policymakers use a pollution tax to control pollution,the tax per unit of pollution should be set
(Multiple Choice)
5.0/5 (81)
(81) Government imposed quantitative limits on the amount of pollution firms are allowed to produce is an example of
(Multiple Choice)
4.8/5 (82)
(82) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)