



 Chat with AI
Exam 14: Oligopoly: Firms in Less Competitive Markets

Exam 1: Economics: Foundations and Models447 Questions
Exam 2: Trade-Offs, comparative Advantage, and the Market System492 Questions
Exam 3: Where Prices Come From: the Interaction of Demand and Supply476 Questions
Exam 4: Economic Efficiency, government Price Setting, and Taxes420 Questions
Exam 5: Externalities, environmental Policy, and Public Goods263 Questions
Exam 6: Elasticity: the Responsiveness of Demand and Supply294 Questions
Exam 7: The Economics of Health Care338 Questions
Exam 8: Firms,the Stock Market,and Corporate Governance522 Questions
Exam 9: Comparative Advantage and the Gains From International Trade377 Questions
Exam 10: Consumer Choice and Behavioral Economics300 Questions
Exam 11: Technology,production,and Costs327 Questions
Exam 12: Firms in Perfectly Competitive Markets296 Questions
Exam 13: Monopolistic Competition: the Competitive Model in a More Realistic Setting272 Questions
Exam 14: Oligopoly: Firms in Less Competitive Markets258 Questions
Exam 15: Monopoly and Antitrust Policy279 Questions
Exam 16: Pricing Strategy261 Questions
Exam 17: The Markets for Labor and Other Factors of Production281 Questions
Exam 18: Public Choice, taxes, and the Distribution of Income258 Questions
Exam 19: Gdp: Measuring Total Production and Income261 Questions
Exam 20: Unemployment and Inflation291 Questions
Exam 21: Economic Growth, the Financial System, and Business Cycles253 Questions
Exam 22: Long-Run Economic Growth: Sources and Policies262 Questions
Exam 23: Aggregate Expenditure and Output in the Short Run301 Questions
Exam 24: Aggregate Demand and Aggregate Supply Analysis286 Questions
Exam 25: Money,banks,and the Federal Reserve System281 Questions
Exam 26: Monetary Policy275 Questions
Exam 27: Fiscal Policy306 Questions
Exam 28: Inflation, unemployment, and Federal Reserve Policy257 Questions
Exam 29: Macroeconomics in an Open Economy278 Questions
Exam 30: The International Financial System258 Questions
Select questions type


Explain why member firms of a cartel like OPEC have incentives to agree to a low cartel production level and then produce more than its quota.

Free
(Essay)
4.9/5  (68)
(68) Correct Answer: Verified
A low cartel production level results in a high market price for oil.Thereafter,each firm has an incentive to unilaterally cheat on the agreement by producing beyond its quota.Of course,ultimately if everyone cheats then the price of oil will fall,but at least for a while some members will earn higher profits than they would if they had adhered to their quotas.
A cooperative equilibrium results when firms
Free
(Multiple Choice)
4.8/5 (64)
(64) Correct Answer:Verified
VerifiedB
Game theory was developed in the 1940s by John von Neuman,a mathematician,and an economist named
(Multiple Choice)
4.9/5 (82)
(82) Prisoner's dilemma games imply that cooperative behavior between two people or two firms always breaks down.But reality teaches us that people and firms often cooperate successfully to achieve their goals.Why do the results from prisoner's dilemma games fail to predict real-world results?
(Multiple Choice)
5.0/5 (76)
(76) According to Porter's Five Competitive Forces Model,which kinds of products are most likely to limit the ability of firms in an industry to raise prices?
(Multiple Choice)
4.8/5 (77)
(77) Price leadership is a form of explicit collusion where one firm in an oligopoly announces a price change and expects all other firms to follow suit.
(True/False)
4.9/5 (80)
(80) Collusion makes firms better off because if they act as a single entity (a cartel)they can reduce output and increase their prices and profits.But some cartels have failed and others are unstable.Which of the following is a reason why cartels often break down?
(Multiple Choice)
4.9/5 (68)
(68) If an industry is made up of five identical firms,the four-firm concentration ratio is
(Multiple Choice)
4.8/5 (78)
(78) In a Nash equilibrium,all players select non-dominant strategies.
(True/False)
4.9/5 (75)
(75) If economies of scale are relatively unimportant in an industry,the typical firm's long-run average total cost curve will reach a minimum at a level of output that is a ________ fraction of total industry sales.The industry will be ________.
(Multiple Choice)
4.8/5 (85)
(85) Table 14-9 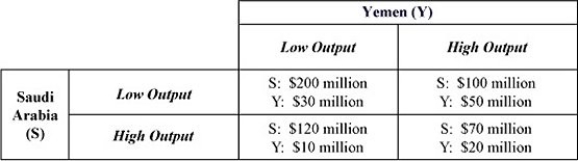 -Refer to Table 14-9.Saudi Arabia and Yemen must decide how much oil to produce.Since the demand for oil is inelastic,relatively low production rates drive up prices and profits.Saudi Arabia,the world's largest and lowest-cost producer,is able to influence market price;it has an incentive to keep output low.Yemen,on the other hand,is a relatively high-cost producer with much smaller reserves.Use the payoff matrix in Table 14-9 to answer the following questions.
a.What is the dominant strategy for Saudi Arabia?
b.What is the dominant strategy for Yemen?
c.What is the Nash equilibrium?
-Refer to Table 14-9.Saudi Arabia and Yemen must decide how much oil to produce.Since the demand for oil is inelastic,relatively low production rates drive up prices and profits.Saudi Arabia,the world's largest and lowest-cost producer,is able to influence market price;it has an incentive to keep output low.Yemen,on the other hand,is a relatively high-cost producer with much smaller reserves.Use the payoff matrix in Table 14-9 to answer the following questions.
a.What is the dominant strategy for Saudi Arabia?
b.What is the dominant strategy for Yemen?
c.What is the Nash equilibrium? (Essay)
4.9/5 (78)
(78) Which of the following is not part of an oligopolist's business strategy?
(Multiple Choice)
4.9/5 (75)
(75) Does the strength of each of the five competitive forces from Michael Porter's model remain constant over time? Briefly explain.
(Essay)
4.9/5 (72)
(72)  Alistair Luggage and Baine Baggage are the only firms selling luggage in the upscale town of Montecito.Each firm must decide on whether to increase its advertising budget to compete for customers.If one firm increases its advertising budget but the other does not,then the firm with the higher advertising budget will increase its profit.Table 14-4 shows the payoff matrix for this advertising game.
-Refer to Table 14-4.Does Baine have a dominant strategy and if so,what is it?
Alistair Luggage and Baine Baggage are the only firms selling luggage in the upscale town of Montecito.Each firm must decide on whether to increase its advertising budget to compete for customers.If one firm increases its advertising budget but the other does not,then the firm with the higher advertising budget will increase its profit.Table 14-4 shows the payoff matrix for this advertising game.
-Refer to Table 14-4.Does Baine have a dominant strategy and if so,what is it? (Multiple Choice)
4.9/5 (77)
(77) In economics,the study of the decisions of firms in industries where the profits of each firm depend on its interactions with other firms is called
(Multiple Choice)
4.9/5 (73)
(73) A consequence of the quota that has been imposed on the importation of sugar into the United States is
(Multiple Choice)
4.8/5 (72)
(72) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)