



 Chat with AI
Exam 11: Technology,production,and Costs

Exam 1: Economics: Foundations and Models447 Questions
Exam 2: Trade-Offs, comparative Advantage, and the Market System492 Questions
Exam 3: Where Prices Come From: the Interaction of Demand and Supply476 Questions
Exam 4: Economic Efficiency, government Price Setting, and Taxes420 Questions
Exam 5: Externalities, environmental Policy, and Public Goods263 Questions
Exam 6: Elasticity: the Responsiveness of Demand and Supply294 Questions
Exam 7: The Economics of Health Care338 Questions
Exam 8: Firms,the Stock Market,and Corporate Governance522 Questions
Exam 9: Comparative Advantage and the Gains From International Trade377 Questions
Exam 10: Consumer Choice and Behavioral Economics300 Questions
Exam 11: Technology,production,and Costs327 Questions
Exam 12: Firms in Perfectly Competitive Markets296 Questions
Exam 13: Monopolistic Competition: the Competitive Model in a More Realistic Setting272 Questions
Exam 14: Oligopoly: Firms in Less Competitive Markets258 Questions
Exam 15: Monopoly and Antitrust Policy279 Questions
Exam 16: Pricing Strategy261 Questions
Exam 17: The Markets for Labor and Other Factors of Production281 Questions
Exam 18: Public Choice, taxes, and the Distribution of Income258 Questions
Exam 19: Gdp: Measuring Total Production and Income261 Questions
Exam 20: Unemployment and Inflation291 Questions
Exam 21: Economic Growth, the Financial System, and Business Cycles253 Questions
Exam 22: Long-Run Economic Growth: Sources and Policies262 Questions
Exam 23: Aggregate Expenditure and Output in the Short Run301 Questions
Exam 24: Aggregate Demand and Aggregate Supply Analysis286 Questions
Exam 25: Money,banks,and the Federal Reserve System281 Questions
Exam 26: Monetary Policy275 Questions
Exam 27: Fiscal Policy306 Questions
Exam 28: Inflation, unemployment, and Federal Reserve Policy257 Questions
Exam 29: Macroeconomics in an Open Economy278 Questions
Exam 30: The International Financial System258 Questions
Select questions type


Quantity of Lanterns Fixed Cost (dollars) Variable Cost (dollars) Total Cost (dollars) Average Total Cost (dollars) 75 200 170 370 4.93 80 200 230 430 5.36 90 200 7.67 100 200 810 115 200 11.8 117 200 1264 1464 12.5 120 200 1480 Table 11-7 shows cost data for Lotus Lanterns,a producer of whimsical night lights.
-Refer to Table 11-7.What is the variable cost of production when the firm produces 115 lanterns?
(Multiple Choice)
4.9/5  (75)
(75) In the short run,if average product is at its maximum,then average variable cost is at its minimum.
(True/False)
4.8/5 (85)
(85) Figure 11-18  -Refer to Figure 11-18.A curve that connects points A,D,and E is called
 (Multiple Choice)
4.9/5 (69)
(69) 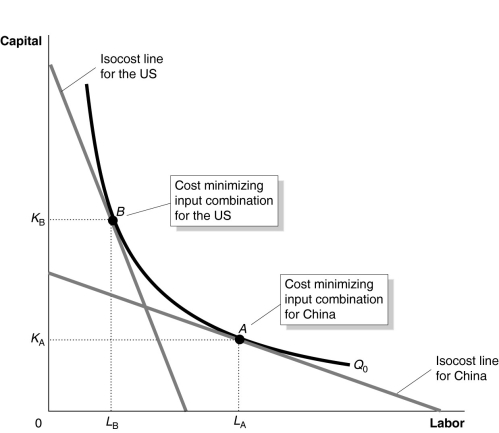 Figure 11-14 shows the optimal input combinations for the production of a given quantity of cotton in the United States and in China.
-Refer to Figure 11-14.Which of the following could explain why the United States and China use different input combinations to produce a given quantity of cotton and yet,each country produces that quantity at the lowest possible cost?
Figure 11-14 shows the optimal input combinations for the production of a given quantity of cotton in the United States and in China.
-Refer to Figure 11-14.Which of the following could explain why the United States and China use different input combinations to produce a given quantity of cotton and yet,each country produces that quantity at the lowest possible cost? (Multiple Choice)
4.8/5 (71)
(71) Economic costs of production differ from accounting costs in that
(Multiple Choice)
4.9/5 (74)
(74) If marginal cost is above the average variable cost,then average variable cost is decreasing.
(True/False)
4.9/5 (71)
(71) When UPS implemented changes which allowed it to deliver more packages with the same number of workers and planes,this represented a positive technological change.
(True/False)
4.8/5 (86)
(86) Jennifer Borts moves her office from the premises she rents at a local mall to her home.As a result of this move
(Multiple Choice)
4.8/5 (95)
(95) Figure 11-1  -Refer to Figure 11-1.The average product of the 4th worker
 (Multiple Choice)
4.7/5 (91)
(91) Number of Workers Apples per Day (bushels) 1 50 2 120 3 180 4 230 5 270 6 300 Table 11-2 summarizes production at the Crunchy Apple Orchard for the month of April.
-Refer to Table 11-2.What is the average product of labor when the orchard employs 5 workers?
(Multiple Choice)
4.8/5 (62)
(62) If a firm experiences positive technological change,it is able to produce more output using the same inputs.
(True/False)
4.9/5 (79)
(79) The processes a firm uses to turn inputs into outputs of goods and services is called
(Multiple Choice)
4.8/5 (78)
(78) Which of the following explains why the marginal cost curve has a U shape?
(Multiple Choice)
4.9/5 (71)
(71) Some colleges now offer massive open online courses (MOOCs),where students do not need to be in the same classroom as their instructors.The fixed cost of an online course is relatively ________,but after the courses are placed online,the marginal cost of providing instruction to an additional student is ________.
(Multiple Choice)
4.8/5 (85)
(85)  Figure 11-6 contains information about the short run cost structure of a firm.
-Refer to Figure 11-6.In the figure above which letter represents the marginal cost curve?
Figure 11-6 contains information about the short run cost structure of a firm.
-Refer to Figure 11-6.In the figure above which letter represents the marginal cost curve? (Multiple Choice)
4.9/5 (74)
(74) Vipsana's Gyros House sells gyros.The cost of ingredients (pita,meat,spices,etc. )to make a gyro is $2.00.Vipsana pays her employees $60 per day.She also incurs a fixed cost of $120 per day.Calculate Vipsana's total cost per day when she produces 50 gyros using two workers?
(Multiple Choice)
4.8/5 (78)
(78) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)