



 Chat with AI
Exam 11: Technology,production,and Costs

Exam 1: Economics: Foundations and Models447 Questions
Exam 2: Trade-Offs, comparative Advantage, and the Market System492 Questions
Exam 3: Where Prices Come From: the Interaction of Demand and Supply476 Questions
Exam 4: Economic Efficiency, government Price Setting, and Taxes420 Questions
Exam 5: Externalities, environmental Policy, and Public Goods263 Questions
Exam 6: Elasticity: the Responsiveness of Demand and Supply294 Questions
Exam 7: The Economics of Health Care338 Questions
Exam 8: Firms,the Stock Market,and Corporate Governance522 Questions
Exam 9: Comparative Advantage and the Gains From International Trade377 Questions
Exam 10: Consumer Choice and Behavioral Economics300 Questions
Exam 11: Technology,production,and Costs327 Questions
Exam 12: Firms in Perfectly Competitive Markets296 Questions
Exam 13: Monopolistic Competition: the Competitive Model in a More Realistic Setting272 Questions
Exam 14: Oligopoly: Firms in Less Competitive Markets258 Questions
Exam 15: Monopoly and Antitrust Policy279 Questions
Exam 16: Pricing Strategy261 Questions
Exam 17: The Markets for Labor and Other Factors of Production281 Questions
Exam 18: Public Choice, taxes, and the Distribution of Income258 Questions
Exam 19: Gdp: Measuring Total Production and Income261 Questions
Exam 20: Unemployment and Inflation291 Questions
Exam 21: Economic Growth, the Financial System, and Business Cycles253 Questions
Exam 22: Long-Run Economic Growth: Sources and Policies262 Questions
Exam 23: Aggregate Expenditure and Output in the Short Run301 Questions
Exam 24: Aggregate Demand and Aggregate Supply Analysis286 Questions
Exam 25: Money,banks,and the Federal Reserve System281 Questions
Exam 26: Monetary Policy275 Questions
Exam 27: Fiscal Policy306 Questions
Exam 28: Inflation, unemployment, and Federal Reserve Policy257 Questions
Exam 29: Macroeconomics in an Open Economy278 Questions
Exam 30: The International Financial System258 Questions
Select questions type


Explain whether each of the following is a fixed cost or a variable cost for Damian Dandridge's tattoo parlor.
a.The payment he makes to buy tattoo ink.
b.The wages he pays his employees.
c.The $500-per-month payment he makes to advertise his shop on highway billboards.
d.The lease payment he makes to the landlord who owns the building where his shop is located.
e.The payment he makes on his liability insurance policy.
(Essay)
4.7/5  (95)
(95) 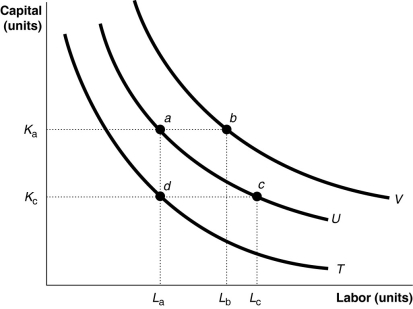 -Refer to Figure 11-12.Which of the following statements about the input combinations shown in the diagram is false?
 (Multiple Choice)
4.8/5 (67)
(67) If the long-run average total cost curve is downward-sloping,then the firm is experiencing decreasing returns to scale.
(True/False)
4.7/5 (75)
(75) The total output produced by a firm divided by the quantity of workers employed by the firm is the definition of
(Multiple Choice)
4.8/5 (79)
(79) Average total cost is equal to average variable cost minus average fixed cost.
(True/False)
5.0/5 (88)
(88) If 11 workers can produce a total of 54 units of a product and a 12th worker has a marginal product of 6 units,then the average product of 12 workers is
(Multiple Choice)
4.9/5 (83)
(83) Damian owns a tattoo parlor and has hired three tattoo artists to work for him.The marginal product of labor is 8 for the first artist,12 for the second artist,and 7 for the third artist.What is Damian's average product of labor for these three tattoo artists?
(Essay)
4.9/5 (85)
(85) What is the difference between explicit costs and implicit costs? List three examples each of explicit costs and implicit costs that may be experienced by a small business.
(Essay)
4.8/5 (83)
(83) Figure 11-13  -Refer to Figure 11-13.The lines shown in the diagram are isocost lines.Which of the following shows an increase in the price of labor while the price of capital remains unchanged?
 (Multiple Choice)
4.7/5 (84)
(84) Which of the following is a factor of production that generally is fixed in the short run?
(Multiple Choice)
4.7/5 (96)
(96)  Figure 11-6 contains information about the short run cost structure of a firm.
-Refer to Figure 11-6.In the figure above which letter represents the average total cost curve?
Figure 11-6 contains information about the short run cost structure of a firm.
-Refer to Figure 11-6.In the figure above which letter represents the average total cost curve? (Multiple Choice)
4.8/5 (81)
(81) The slope of a typical isoquant is negative because to produce a given output,a producer
(Multiple Choice)
5.0/5 (76)
(76) If average total cost is falling marginal cost must also be falling.
(True/False)
4.9/5 (76)
(76) The slope of an isocost line ________ and equals the negative of ________.
(Multiple Choice)
4.8/5 (77)
(77) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)