



 Chat with AI
Exam 11: Technology,production,and Costs

Exam 1: Economics: Foundations and Models447 Questions
Exam 2: Trade-Offs, comparative Advantage, and the Market System492 Questions
Exam 3: Where Prices Come From: the Interaction of Demand and Supply476 Questions
Exam 4: Economic Efficiency, government Price Setting, and Taxes420 Questions
Exam 5: Externalities, environmental Policy, and Public Goods263 Questions
Exam 6: Elasticity: the Responsiveness of Demand and Supply294 Questions
Exam 7: The Economics of Health Care338 Questions
Exam 8: Firms,the Stock Market,and Corporate Governance522 Questions
Exam 9: Comparative Advantage and the Gains From International Trade377 Questions
Exam 10: Consumer Choice and Behavioral Economics300 Questions
Exam 11: Technology,production,and Costs327 Questions
Exam 12: Firms in Perfectly Competitive Markets296 Questions
Exam 13: Monopolistic Competition: the Competitive Model in a More Realistic Setting272 Questions
Exam 14: Oligopoly: Firms in Less Competitive Markets258 Questions
Exam 15: Monopoly and Antitrust Policy279 Questions
Exam 16: Pricing Strategy261 Questions
Exam 17: The Markets for Labor and Other Factors of Production281 Questions
Exam 18: Public Choice, taxes, and the Distribution of Income258 Questions
Exam 19: Gdp: Measuring Total Production and Income261 Questions
Exam 20: Unemployment and Inflation291 Questions
Exam 21: Economic Growth, the Financial System, and Business Cycles253 Questions
Exam 22: Long-Run Economic Growth: Sources and Policies262 Questions
Exam 23: Aggregate Expenditure and Output in the Short Run301 Questions
Exam 24: Aggregate Demand and Aggregate Supply Analysis286 Questions
Exam 25: Money,banks,and the Federal Reserve System281 Questions
Exam 26: Monetary Policy275 Questions
Exam 27: Fiscal Policy306 Questions
Exam 28: Inflation, unemployment, and Federal Reserve Policy257 Questions
Exam 29: Macroeconomics in an Open Economy278 Questions
Exam 30: The International Financial System258 Questions
Select questions type


Which of the following can a firm do in the long run but not in the short run?
(Multiple Choice)
4.8/5  (75)
(75) When the average total cost is $16 and the total cost is $800,then the number of units the firm is producing is
(Multiple Choice)
4.8/5 (78)
(78) Table 11-6
Quantity of Quantity of foot Fixed Variable Total Average Marginal workers massages per day cost cost cost total cost cost 0 0 1 10 2 25 3 45 4 60 5 70
-Refer to Table 11-6.Alicia Gregory owns a foot massage business.She leases 4 computer-controlled massage booths,for which she pays $125 per day.She cannot increase the number machines she leases without giving the manufacturer 3 months notice.She can hire as many workers as she wants at a cost of $75 per day per worker.These are the only two inputs she uses in her business.Use this information to fill in the columns in the above table.
(Essay)
4.9/5 (70)
(70) A firm's cost of production is determined by all of the following except
(Multiple Choice)
4.8/5 (78)
(78) A firm increased its production and sales because the firm's manager rearranged the layout of his factory floor.This is an example of
(Multiple Choice)
4.7/5 (82)
(82) The level of output at which all economies of scale have been exhausted is known as
(Multiple Choice)
4.9/5 (87)
(87) As output increases,average fixed cost gets smaller and smaller.
(True/False)
4.9/5 (76)
(76) Figure 11-17 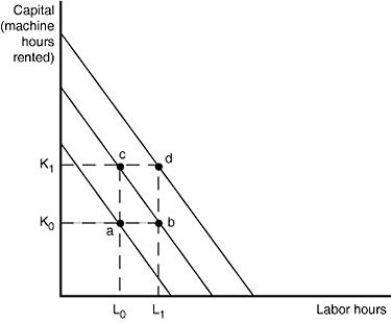 -Refer to Figure 11-17.Assume that production isoquants are convex.Total cost and output produced must increase for each of the following movements except one.Which movement is the exception?
 (Multiple Choice)
4.9/5 (79)
(79)  Figure 11-11 illustrates the long-run average cost curve for a firm that produces picture frames.The graph also includes short-run average cost curves for three firm sizes: ATCa,ATCb and ATCc.
-Refer to Figure 11-11.For output rates greater than 20,000 picture frames per month
Figure 11-11 illustrates the long-run average cost curve for a firm that produces picture frames.The graph also includes short-run average cost curves for three firm sizes: ATCa,ATCb and ATCc.
-Refer to Figure 11-11.For output rates greater than 20,000 picture frames per month (Multiple Choice)
4.9/5 (76)
(76) The rate at which a firm is able to substitute one input for another while keeping the level of output constant is called the
(Multiple Choice)
4.7/5 (59)
(59) The president of Toyota's Georgetown plant was quoted as saying,"Demand for high volumes saps your energy.Over a period of time,it eroded our focus [and] thinned out the expertise and knowledge we painstakingly built up over the years." This quote suggests that
(Multiple Choice)
4.8/5 (93)
(93) 1eaaa28_a9cb_7b34_9b29_2f66e61cebfd_TB3018_00_TB3018_00_TB3018_00 Table 11-1 shows the technology of production at the Matsuko's Mushroom Farm for the month of May.
-Refer to Table 11-1.Diminishing marginal returns sets in when the ________ worker is hired.
(Multiple Choice)
4.8/5 (84)
(84) The short run is the time period during which a firm has at least one input constraint.
(True/False)
5.0/5 (90)
(90) The shape of the average total cost curve is determined by the shape of
(Multiple Choice)
4.9/5 (81)
(81) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)