



 Chat with AI
Exam 1: Limits, Alternatives, and Choices

Exam 1: Limits, Alternatives, and Choices212 Questions
Exam 2: The Market System and the Circular Flow141 Questions
Exam 3: Demand, Supply, and Market Equilibrium202 Questions
Exam 4: Market Failures: Public Goods and Externalities155 Questions
Exam 5: Governments Role and Government Failure148 Questions
Exam 6: An Introduction to Macroeconomics123 Questions
Exam 7: Measuring Domestic Output and National Income157 Questions
Exam 8: Economic Growth114 Questions
Exam 9: Business Cycles, Unemployment, and Inflation143 Questions
Exam 10: Basic Macroeconomic Relationships142 Questions
Exam 11: The Aggregate Expenditures Model143 Questions
Exam 12: Aggregate Demand and Aggregate Supply152 Questions
Exam 13: Fiscal Policy, Deficits, and Debt164 Questions
Exam 14: Money, Banking, and Financial Institutions130 Questions
Exam 15: Money Creation127 Questions
Exam 16: Interest Rates and Monetary Policy174 Questions
Exam 17: Financial Economics136 Questions
Exam 18: Extending the Analysis of Aggregate Supply135 Questions
Exam 19: Current Issues in Macro Theory and Policy134 Questions
Exam 20: International Trade151 Questions
Exam 21: The Balance of Payments, Exchange Rates, and Trade Deficits152 Questions
Exam 22: The Economics of Developing Countries135 Questions
Select questions type


In a constructing the demand graph to show how the price of a good price affects how much of it the buyers will buy, the convention that economists follow is to measure price on the:
(Multiple Choice)
4.7/5  (74)
(74) If a nation is operating at a point inside the production possibilities curve, it indicates that the nation could:
(Multiple Choice)
4.9/5 (85)
(85) When studying human behavior, economists assume rational self-interest. This means that:
(Multiple Choice)
4.9/5 (72)
(72) Economic principles are value judgments about what the economy should be like or the way the economic world ought to be.
(True/False)
4.7/5 (82)
(82) What is the best economic explanation for why a person would drop out of college to take a job or start a business?
(Multiple Choice)
4.8/5 (90)
(90) The notion of "purposeful behavior" in the economic perspective suggests that:
(Multiple Choice)
5.0/5 (84)
(84) If an inverse relationship exists between two variables, then:
(Multiple Choice)
4.7/5 (81)
(81) 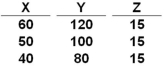 Variables X and Y in the above table are:
The quantity or supply of land resources available to a nation is pretty much fixed and cannot increase over time.
(True/False)
4.7/5 (87)
(87) The following graph is the production possibilities curve of a nation: 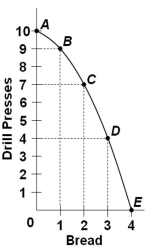 Refer to the above graph. The total opportunity cost of nine drill presses is:
 (Multiple Choice)
4.7/5 (79)
(79) 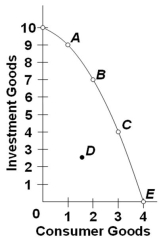 Refer to the above graph. The selection of which point on the production possibilities curve is most like to result in the largest increase in economic growth over time?
 (Multiple Choice)
4.9/5 (68)
(68) Lauren makes $150 a day as a bank clerk. She takes two days off work without pay, to fly to another city to attend the concert of her favorite band. The cost of transportation and lodging for the trip is $250. The cost of the concert ticket is $50. The opportunity cost of Lauren's decision to attend the concert is:
(Multiple Choice)
4.9/5 (79)
(79) Which of the following is the best synonym for "marginal" in economics?
(Multiple Choice)
4.8/5 (83)
(83) If economic resources were perfectly adaptable to alternative uses, then there would be constant opportunity costs along the production possibilities curve.
(True/False)
4.8/5 (69)
(69) Suppose that a consumer purchases just two goods, X and Y. The Y-intercept of the budget line in this case would indicate the:
(Multiple Choice)
5.0/5 (82)
(82) Which of the following indicates an inverse relationship between x and y?
(Multiple Choice)
4.8/5 (86)
(86) The opportunity cost of doing or getting something is best and fully defined as:
(Multiple Choice)
4.9/5 (78)
(78) One basic difference between "land" and "capital" resources is that land is:
(Multiple Choice)
4.8/5 (71)
(71) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)