



 Chat with AI
Exam 11: Costs and Profit Maximization Under Competition

Exam 1: The Big Ideas253 Questions
Exam 2: The Power of Trade and Comparative239 Questions
Exam 3: Supply and Demand249 Questions
Exam 4: Equilibrium256 Questions
Exam 5: Elasticity and Its Applications271 Questions
Exam 6: Taxes and Subsidies225 Questions
Exam 7: The Price System275 Questions
Exam 8: Price Ceilings and Floors327 Questions
Exam 9: International Trade195 Questions
Exam 10: Externalities- When the Price Is Not Right273 Questions
Exam 11: Costs and Profit Maximization Under Competition217 Questions
Exam 12: Competition and the Invisible Hand144 Questions
Exam 13: Monopoly233 Questions
Exam 14: Price Discrimination262 Questions
Exam 15: Oligopoly and Game Theory218 Questions
Exam 16: Competing for Monopoly160 Questions
Exam 17: Monopolistic Competition and Advertising113 Questions
Exam 18: Labor Markets262 Questions
Exam 19: Public Goods and the Tragedy of the Commons244 Questions
Exam 20: Political Economy and Public Choice306 Questions
Exam 21: Economics, Ethics, and Public Policy241 Questions
Exam 22: Managing Incentives263 Questions
Exam 23: Stock Markets and Personal Finance271 Questions
Exam 24: Price Discrimination151 Questions
Exam 25: Consumer Choice145 Questions
Select questions type


Decreasing cost industries have supply curves that slope downward forever.
(True/False)
4.7/5  (92)
(92) In a constant cost industry, many firms can expand or contract without a change in costs.
(True/False)
4.8/5 (72)
(72) A firm should enter an industry if total revenue is equal to total cost.
(True/False)
4.9/5 (79)
(79) The change in total revenue from selling an additional unit is called:
(Multiple Choice)
4.8/5 (82)
(82) If marginal revenue is less than marginal cost, a firm should:
(Multiple Choice)
4.8/5 (94)
(94) A strawberry farmer has 5,000 pounds of strawberries ready to harvest. The cost of picking and transporting the strawberries to the market is $3,500. If the market pays $0.60 per pound of strawberries, what should the strawberry farmer do?
(Multiple Choice)
5.0/5 (79)
(79) Marginal cost is the change in total cost from producing an additional unit of output.
(True/False)
4.9/5 (91)
(91) Which of the following is NOT a key decision that a firm must make?
(Multiple Choice)
4.9/5 (74)
(74) According to the text, the demand curve for oil from a particular stripper well is:
(Multiple Choice)
4.8/5 (79)
(79) Programs such as Steam distribute more and more video games. Purchasers buy the game and download it immediately to their computer. If the entire system is automated, estimate the marginal cost of producing and selling video games this way (ignore electricity costs).
(Multiple Choice)
4.9/5 (89)
(89) Figure: Profit Maximizing Output 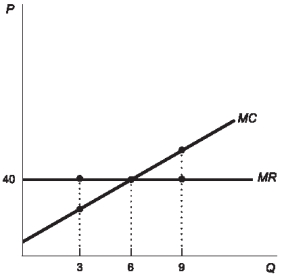 Use the figure. The profit-maximizing output for this firm is:
 (Multiple Choice)
4.8/5 (76)
(76) If the market price in a competitive market is $10, and a firm's marginal cost (MC) is given by MC = 0.50Q, where Q is units of output, this firm should produce 20 units of output to maximize profit.
(True/False)
4.8/5 (74)
(74) Which kind of industry would have a downward-sloping long-run supply curve?
(Multiple Choice)
4.7/5 (78)
(78) In competitive markets, the demand curve faced by the individual firm is:
(Multiple Choice)
4.8/5 (76)
(76) The difference between the long run and the short run is that in the long run, marginal cost equals marginal revenue for all firms in the economy.
(True/False)
4.9/5 (79)
(79) Use the following to answer questions:
Figure: Costs of Oil Production 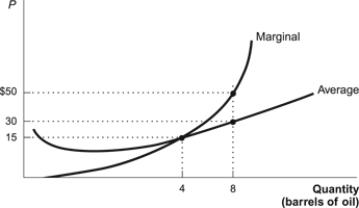 -(Figure: Costs of Oil Production) Refer to the figure. Assuming that price equals marginal cost, the profit of producing eight barrels of oil is:
 (Multiple Choice)
4.9/5 (94)
(94) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)