



 Chat with AI
Exam 11: Costs and Profit Maximization Under Competition

Exam 1: The Big Ideas253 Questions
Exam 2: The Power of Trade and Comparative239 Questions
Exam 3: Supply and Demand249 Questions
Exam 4: Equilibrium256 Questions
Exam 5: Elasticity and Its Applications271 Questions
Exam 6: Taxes and Subsidies225 Questions
Exam 7: The Price System275 Questions
Exam 8: Price Ceilings and Floors327 Questions
Exam 9: International Trade195 Questions
Exam 10: Externalities- When the Price Is Not Right273 Questions
Exam 11: Costs and Profit Maximization Under Competition217 Questions
Exam 12: Competition and the Invisible Hand144 Questions
Exam 13: Monopoly233 Questions
Exam 14: Price Discrimination262 Questions
Exam 15: Oligopoly and Game Theory218 Questions
Exam 16: Competing for Monopoly160 Questions
Exam 17: Monopolistic Competition and Advertising113 Questions
Exam 18: Labor Markets262 Questions
Exam 19: Public Goods and the Tragedy of the Commons244 Questions
Exam 20: Political Economy and Public Choice306 Questions
Exam 21: Economics, Ethics, and Public Policy241 Questions
Exam 22: Managing Incentives263 Questions
Exam 23: Stock Markets and Personal Finance271 Questions
Exam 24: Price Discrimination151 Questions
Exam 25: Consumer Choice145 Questions
Select questions type


In a constant cost industry, P = AC = $20. Which sequence of events follows an increase in demand?

Free
(Multiple Choice)
4.9/5  (72)
(72) Correct Answer: Verified
A
Because only greater quantities of oil can be produced by using more expensive production methods, the industry is:
Free
(Multiple Choice)
4.8/5 (81)
(81) Correct Answer:Verified
VerifiedA
If a single supplier produces such a small portion of the total market output that changes in its production have no impact on the overall market price,:
Free
(Multiple Choice)
4.7/5 (74)
(74) Correct Answer:Verified
VerifiedB
A market is considered perfectly competitive if:
I. there is a lot of product differentiation among sellers.
II. there are many sellers, each small relative to the total market.
III. the product sold is similar across sellers.
IV. there are only a few buyers.
(Multiple Choice)
4.9/5 (90)
(90) Use the following to answer questions :
Figure: Profits and Competitive Firms 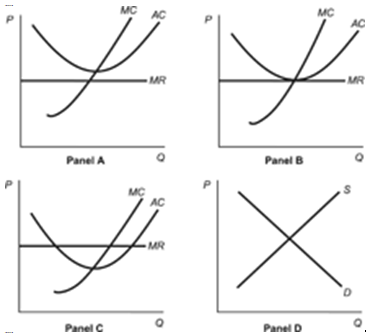 -(Figure: Profits and Competitive Firms) Refer to the four panels in the figure. Which panel shows a competitive firm making zero economic profits?
 (Multiple Choice)
4.9/5 (74)
(74) At the profit-maximizing output level P = MC, if P > AC then firms can earn above-normal profit, causing entry into the industry.
(True/False)
4.7/5 (87)
(87) In a constant cost industry, the market price and average cost are equal to $23. Therefore, which of the following is correct?
(Multiple Choice)
4.8/5 (69)
(69) Table: Oil Production Costs
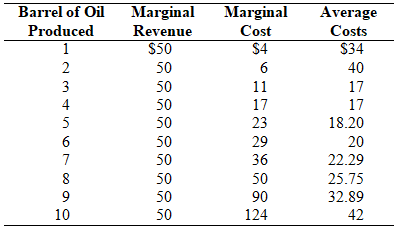 Refer to the table. If seven barrels of oil are produced, this firm is making:
 (Multiple Choice)
4.8/5 (71)
(71) Figure: AC 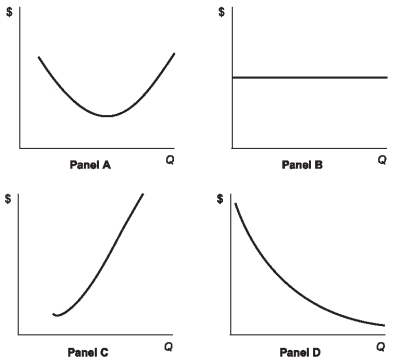 Refer to the set of four panels in the figure. Which panel shows the typical shape of the average cost curve in a competitive market?
 (Multiple Choice)
4.7/5 (78)
(78) To maximize profits, firms produce the level of output that:
(Multiple Choice)
4.9/5 (76)
(76) Use the following to answer questions:
Figure: Maximizing Profit 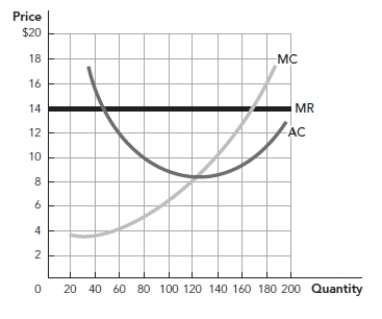 -(Figure: Maximizing Profit) What is the firm's profit-maximizing level of output?
 (Multiple Choice)
4.9/5 (96)
(96) Damien produces 400 gallons of milk a day in a very competitive industry. The market price for a gallon of milk is $2. Damien's marginal revenue per gallon of milk is:
(Multiple Choice)
4.9/5 (80)
(80) Marginal revenue is always equal to the price of the product for a competitive firm.
(True/False)
4.8/5 (92)
(92) A firm should exit an industry if price is less than average cost.
(True/False)
4.9/5 (70)
(70) The amount of money that the firm pays for its inputs is called:
(Multiple Choice)
4.9/5 (78)
(78) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)