



 Chat with AI
Exam 11: Costs and Profit Maximization Under Competition

Exam 1: The Big Ideas253 Questions
Exam 2: The Power of Trade and Comparative239 Questions
Exam 3: Supply and Demand249 Questions
Exam 4: Equilibrium256 Questions
Exam 5: Elasticity and Its Applications271 Questions
Exam 6: Taxes and Subsidies225 Questions
Exam 7: The Price System275 Questions
Exam 8: Price Ceilings and Floors327 Questions
Exam 9: International Trade195 Questions
Exam 10: Externalities- When the Price Is Not Right273 Questions
Exam 11: Costs and Profit Maximization Under Competition217 Questions
Exam 12: Competition and the Invisible Hand144 Questions
Exam 13: Monopoly233 Questions
Exam 14: Price Discrimination262 Questions
Exam 15: Oligopoly and Game Theory218 Questions
Exam 16: Competing for Monopoly160 Questions
Exam 17: Monopolistic Competition and Advertising113 Questions
Exam 18: Labor Markets262 Questions
Exam 19: Public Goods and the Tragedy of the Commons244 Questions
Exam 20: Political Economy and Public Choice306 Questions
Exam 21: Economics, Ethics, and Public Policy241 Questions
Exam 22: Managing Incentives263 Questions
Exam 23: Stock Markets and Personal Finance271 Questions
Exam 24: Price Discrimination151 Questions
Exam 25: Consumer Choice145 Questions
Select questions type


Use the following to answer questions:
Figure: Costs of Oil Production 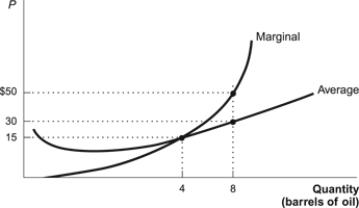 -(Figure: Costs of Oil Production) Refer to the figure. Assuming that price equals marginal cost, the total cost of producing eight barrels of oil is:
 (Multiple Choice)
4.9/5  (82)
(82) When a firm expands output from 10 to 11 units and total revenue increases from $100 to $110, marginal revenue of the eleventh unit is:
(Multiple Choice)
4.8/5 (73)
(73) In a perfectly competitive market, sellers who set their price above the market price will sell nothing.
(True/False)
4.9/5 (84)
(84) Use the following to answer questions :
Figure: Profits and Competitive Firms 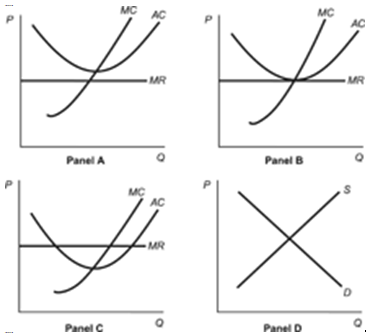 -(Figure: Profits and Competitive Firms) Refer to the four panels in the figure. Which panel shows a competitive firm making an economic loss?
 (Multiple Choice)
4.9/5 (96)
(96) Use the following to answer questions:
Figure: Industry Firms 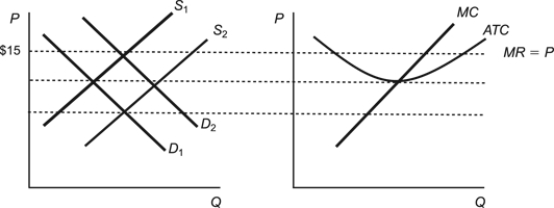 -(Figure: Industry Firms) Refer to the figures. The market is characterized by demand curve D2 and supply curve S1. The firms in the industry are earning ________, which will cause the______________.
 (Multiple Choice)
4.8/5 (76)
(76) The total amount of money that a firm receives from sales of its output is called:
(Multiple Choice)
4.7/5 (88)
(88) A firm will continue to produce additional output, as long as marginal revenue is greater than marginal cost.
(True/False)
4.9/5 (71)
(71) Restaurants in tourists areas will close during the off-season if their:
(Multiple Choice)
4.7/5 (69)
(69) Perfectly competitive firms produce at the quantity where marginal revenue ______ marginal cost.
(Multiple Choice)
4.8/5 (83)
(83) Economists study decreasing cost industries in order to explain:
(Multiple Choice)
4.9/5 (74)
(74) Figure: Pineapples 2 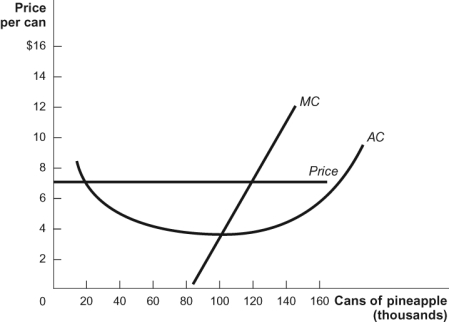 Refer to the figure. In the long run, what do you expect this firm's economic profit or loss to be?
 (Multiple Choice)
4.8/5 (91)
(91) When the level of production is relatively low, the average cost per unit of output would ________ if output increased.
(Multiple Choice)
4.9/5 (83)
(83) If firms in a competitive market are earning above-normal profits, the elimination principle states that new firms will enter the market and drive profits to normal.
(True/False)
4.9/5 (82)
(82) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)