



 Chat with AI
Exam 11: Costs and Profit Maximization Under Competition

Exam 1: The Big Ideas253 Questions
Exam 2: The Power of Trade and Comparative239 Questions
Exam 3: Supply and Demand249 Questions
Exam 4: Equilibrium256 Questions
Exam 5: Elasticity and Its Applications271 Questions
Exam 6: Taxes and Subsidies225 Questions
Exam 7: The Price System275 Questions
Exam 8: Price Ceilings and Floors327 Questions
Exam 9: International Trade195 Questions
Exam 10: Externalities- When the Price Is Not Right273 Questions
Exam 11: Costs and Profit Maximization Under Competition217 Questions
Exam 12: Competition and the Invisible Hand144 Questions
Exam 13: Monopoly233 Questions
Exam 14: Price Discrimination262 Questions
Exam 15: Oligopoly and Game Theory218 Questions
Exam 16: Competing for Monopoly160 Questions
Exam 17: Monopolistic Competition and Advertising113 Questions
Exam 18: Labor Markets262 Questions
Exam 19: Public Goods and the Tragedy of the Commons244 Questions
Exam 20: Political Economy and Public Choice306 Questions
Exam 21: Economics, Ethics, and Public Policy241 Questions
Exam 22: Managing Incentives263 Questions
Exam 23: Stock Markets and Personal Finance271 Questions
Exam 24: Price Discrimination151 Questions
Exam 25: Consumer Choice145 Questions
Select questions type


Fewer potential sellers make a firm-level demand curve ______ in the ______.
(Multiple Choice)
4.9/5  (86)
(86) Economic profit differs from accounting profits because of its inclusion of:
(Multiple Choice)
4.9/5 (79)
(79) A firm pays a monthly lease of $10,000 and generates $8,000 of revenue a month. Which of the following is TRUE?
(Multiple Choice)
4.8/5 (83)
(83) Figure: Profits 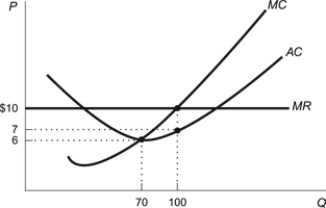 How much profit is the firm making at the profit-maximizing quantity?
 (Multiple Choice)
4.9/5 (74)
(74) Whenever marginal cost is greater than the average total cost:
(Multiple Choice)
4.9/5 (82)
(82) To maximize profit, a firm in a competitive market increases output until:
(Multiple Choice)
4.9/5 (91)
(91) Give two reasons why an industry might be an increasing cost industry and use examples to demonstrate your reasons.
(Essay)
4.8/5 (65)
(65) Use the following to answer questions:
Figure: Two-Firm Industry 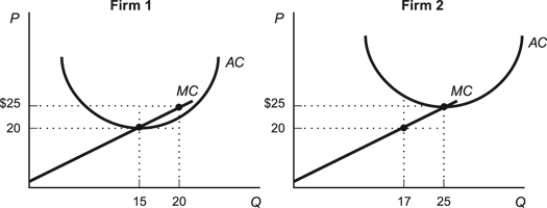 -(Figure: Two-Firm Industry) Refer to the figures. At a market price of $25, the total quantity supplied in the industry is:
 (Multiple Choice)
4.8/5 (77)
(77) Economic profit is equal to total revenue minus explicit costs.
(True/False)
4.9/5 (67)
(67) Graphically illustrate the maximum profit of a firm in a competitive market, and on the same graph depict how the profit-maximizing quantity would change as the price changes.
(Essay)
4.9/5 (67)
(67) Use the following to answer questions:
Figure: Industry Firms 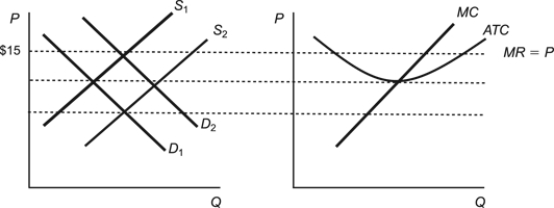 -(Figure: Industry Firms) Refer to the figures. This industry is a(n):
 (Multiple Choice)
4.9/5 (76)
(76) Use the following to answer questions:
Figure: Costs 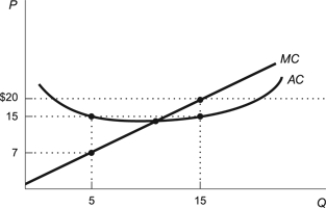 -(Figure: Costs) Use the figure. At a price of $20, which statement is FALSE?
 (Multiple Choice)
4.8/5 (82)
(82) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)