



 Chat with AI
Exam 11: Costs and Profit Maximization Under Competition

Exam 1: The Big Ideas253 Questions
Exam 2: The Power of Trade and Comparative239 Questions
Exam 3: Supply and Demand249 Questions
Exam 4: Equilibrium256 Questions
Exam 5: Elasticity and Its Applications271 Questions
Exam 6: Taxes and Subsidies225 Questions
Exam 7: The Price System275 Questions
Exam 8: Price Ceilings and Floors327 Questions
Exam 9: International Trade195 Questions
Exam 10: Externalities- When the Price Is Not Right273 Questions
Exam 11: Costs and Profit Maximization Under Competition217 Questions
Exam 12: Competition and the Invisible Hand144 Questions
Exam 13: Monopoly233 Questions
Exam 14: Price Discrimination262 Questions
Exam 15: Oligopoly and Game Theory218 Questions
Exam 16: Competing for Monopoly160 Questions
Exam 17: Monopolistic Competition and Advertising113 Questions
Exam 18: Labor Markets262 Questions
Exam 19: Public Goods and the Tragedy of the Commons244 Questions
Exam 20: Political Economy and Public Choice306 Questions
Exam 21: Economics, Ethics, and Public Policy241 Questions
Exam 22: Managing Incentives263 Questions
Exam 23: Stock Markets and Personal Finance271 Questions
Exam 24: Price Discrimination151 Questions
Exam 25: Consumer Choice145 Questions
Select questions type


Figure: Entry Exit 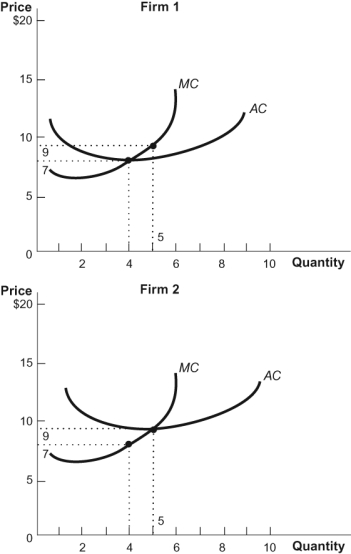 Refer to the figure. This competitive firm operates in a constant cost industry. The current market price is $15. What is the long-run market price?
 (Multiple Choice)
4.8/5  (85)
(85) Figure: Profit Maximization 6 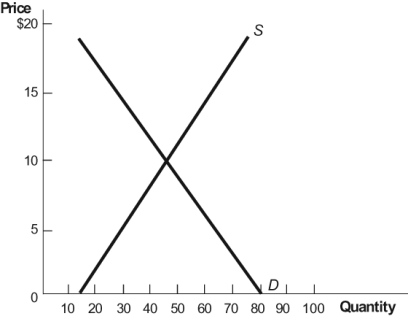 At any price above $60 in this diagram, firms already in this market will be making an economic:
 (Multiple Choice)
4.9/5 (91)
(91) Use the following to answer questions:
Figure: Two-Firm Industry 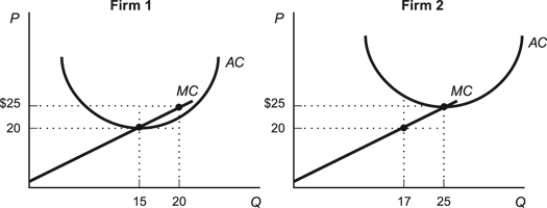 -(Figure: Two-Firm Industry) Refer to the figures. At a market price of $20, the total quantity supplied in the industry is:
 (Multiple Choice)
4.9/5 (60)
(60) Which of the following statements is TRUE?
I. If a competitive firm sells its product at a price of $80, the firm should increase production from 100 to 101 units if the total cost rises from $2,000 to $2,066.
II. If the marginal cost of the tenth unit is $14 and the marginal revenue is $10, the firm should produce the tenth unit to increase profits by $4.
III. For competitive firms, profits are maximized at MR = MC or P = MC, since P = MR.
(Multiple Choice)
4.7/5 (85)
(85) Which of the following best illustrates a product sold in a perfectly competitive market?
(Multiple Choice)
4.9/5 (87)
(87) If marginal cost is less than average cost, average cost is rising.
(True/False)
4.9/5 (91)
(91) For a small firm in an extremely competitive industry, marginal revenue is always equal to price because:
(Multiple Choice)
4.9/5 (78)
(78) If Tom sells 500 sandwiches for $7 and has an average cost of $5, what is his total revenue?
(Multiple Choice)
4.9/5 (79)
(79) In the short run, if price is less than average cost, a firm:
(Multiple Choice)
4.7/5 (79)
(79) Price equals marginal revenue for a competitive firm because:
(Multiple Choice)
4.8/5 (63)
(63) Figure: World Market for Maple Syrup 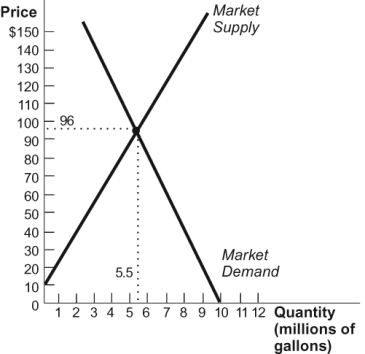 Refer to the figure. If you are one of literally thousands of maple syrup producers and you wanted to increase your maple syrup production from 100 gallons to 110 gallons, what price would you charge?
 (Multiple Choice)
4.7/5 (73)
(73) Firms have less pricing power if their firm-level product is more unique.
(True/False)
4.8/5 (73)
(73) To maximize profits, a firm in a highly competitive industry should set its price:
(Multiple Choice)
4.9/5 (72)
(72) The more and better substitutes a good has, the more elastic the demand for that good will be.
(True/False)
4.9/5 (82)
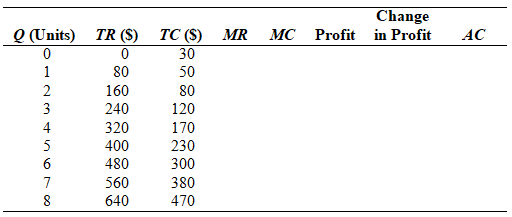
(82) The table shows the TR and TC schedules for a competitive firm. Using your knowledge of cost and profit structures, fill in all the missing blanks.
Table: Cost Schedules
(Essay)
4.9/5 (91)
(91) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)