



 Chat with AI
Exam 11: Costs and Profit Maximization Under Competition

Exam 1: The Big Ideas253 Questions
Exam 2: The Power of Trade and Comparative239 Questions
Exam 3: Supply and Demand249 Questions
Exam 4: Equilibrium256 Questions
Exam 5: Elasticity and Its Applications271 Questions
Exam 6: Taxes and Subsidies225 Questions
Exam 7: The Price System275 Questions
Exam 8: Price Ceilings and Floors327 Questions
Exam 9: International Trade195 Questions
Exam 10: Externalities- When the Price Is Not Right273 Questions
Exam 11: Costs and Profit Maximization Under Competition217 Questions
Exam 12: Competition and the Invisible Hand144 Questions
Exam 13: Monopoly233 Questions
Exam 14: Price Discrimination262 Questions
Exam 15: Oligopoly and Game Theory218 Questions
Exam 16: Competing for Monopoly160 Questions
Exam 17: Monopolistic Competition and Advertising113 Questions
Exam 18: Labor Markets262 Questions
Exam 19: Public Goods and the Tragedy of the Commons244 Questions
Exam 20: Political Economy and Public Choice306 Questions
Exam 21: Economics, Ethics, and Public Policy241 Questions
Exam 22: Managing Incentives263 Questions
Exam 23: Stock Markets and Personal Finance271 Questions
Exam 24: Price Discrimination151 Questions
Exam 25: Consumer Choice145 Questions
Select questions type


Marcie quit her job as a preschool teacher, which paid an annual salary of $28,000, and became a street food vendor. She used $8,000 out of her savings account that paid a 4% annual interest rate to buy a street cart to sell food. In her first year of operations, she spent $10,000 on food and supplies (napkins, cups, plates, etc.) and earned total revenue of $45,000. Marcie's accounting profit is ______ and economic profit is ______.
(Multiple Choice)
4.8/5  (83)
(83) If Tom sells 500 sandwiches for $7 and has an average cost of $5, what is his profit?
(Multiple Choice)
4.9/5 (79)
(79) Firms in a perfectly competitive industry maximize profits by:
(Multiple Choice)
4.8/5 (82)
(82) In the small town of Wellsville, there is only one grocery store. Given that everyone needs food, we would expect that this grocery store:
(Multiple Choice)
4.8/5 (85)
(85) Which of the following statements is TRUE? Economists normally assume that the goal of the firm is to:
I. sell as much of their product as possible.
II. set the price of their product as high as possible.
III. maximize profit.
(Multiple Choice)
4.8/5 (82)
(82) Profit can be shown graphically by depicting a firm's costs and revenues, and it is determined mathematically by calculating the:
(Multiple Choice)
4.8/5 (81)
(81) Explain why a profit-maximizing firm in a competitive market would increase output until price is equal to marginal cost?
(Essay)
4.9/5 (86)
(86) Which of the following best describes a competitive industry?
(Multiple Choice)
4.8/5 (59)
(59) Which of the following statements are TRUE? A firm's entry/exit decision is about:
I. whether profits are positive or negative now.
II. whether the stream of future profits is positive or negative.
III. government regulations.
(Multiple Choice)
5.0/5 (87)
(87) More potential sellers ______ the elasticity of ______ firm-level demand.
(Multiple Choice)
4.8/5 (82)
(82) A market becomes more competitive as the product becomes ______ homogeneous and there are ______ potential sellers.
(Multiple Choice)
4.8/5 (61)
(61) A firm's profit-maximizing quantity does not depend on its fixed costs.
(True/False)
5.0/5 (74)
(74) When competitive firms do not have influence over the price of their product, all of the following are true EXCEPT which condition?
(Multiple Choice)
4.9/5 (79)
(79) To maximize profit, firms should keep producing as long as marginal revenue is:
(Multiple Choice)
4.9/5 (81)
(81) A competitive firm maximizes profits at the point where P = MC = AC.
(True/False)
4.9/5 (87)
(87) With fluctuating prices in an industry, firms are likely to:
(Multiple Choice)
4.8/5 (75)
(75) Use the following to answer questions:
Figure: Maximizing Profit 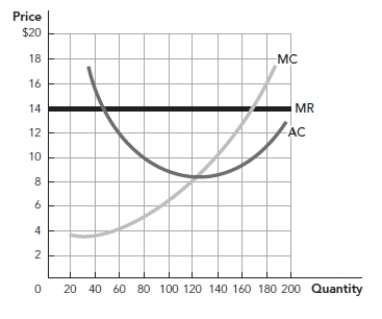 -The change in total cost from producing the eighth unit of output is ______, and the change in total revenue from producing the seventh unit of output is ______.
 (Multiple Choice)
4.8/5 (70)
(70) A baker wants to establish a pie factory. The cost of leasing the factory is $1,000 per day. The profit maximizing quantity of pies is 1,000 pies a day. Each pie sells for $3 and costs only $2.10 to make. Which of the following is a correct conclusion based on this data?
(Multiple Choice)
4.9/5 (87)
(87) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)