



 Chat with AI
Exam 15: Monopoly and Antitrust Policy

Exam 1: Economics: Foundations and Models142 Questions
Exam 2: Trade-Offs, comparative Advantage, and the Market System152 Questions
Exam 3: Where Prices Come From: the Interaction of Demand and Supply149 Questions
Exam 4: Economic Efficiency, government Price Setting, and Taxes137 Questions
Exam 5: Externalities, environmental Policy, and Public Goods139 Questions
Exam 6: Elasticity: The Responsiveness of Demand and Supply149 Questions
Exam 7: The Economics of Health Care117 Questions
Exam 8: Firms, the Stock Market, and Corporate Governance140 Questions
Exam 9: Comparative Advantage and the Gains From International Trade124 Questions
Exam 10: Consumer Choice and Behavioral Economics154 Questions
Exam 11: Technology, production, and Costs174 Questions
Exam 12: Firms in Perfectly Competitive Markets153 Questions
Exam 13: Monopolistic Competition: The Competitive Model in a More Realistic Setting137 Questions
Exam 14: Oligopoly: Firms in Less Competitive Markets129 Questions
Exam 15: Monopoly and Antitrust Policy148 Questions
Exam 16: Pricing Strategy134 Questions
Exam 17: The Markets for Labor and Other Factors of Production149 Questions
Exam 18: Public Choice, taxes, and the Distribution of Income134 Questions
Exam 19: GDP: Measuring Total Production and Income135 Questions
Exam 20: Unemployment and Inflation148 Questions
Exam 21: Economic Growth, the Financial System, and Business Cycles130 Questions
Exam 22: Long-Run Economic Growth: Sources and Policies134 Questions
Exam 23: Aggregate Expenditure and Output in the Short Run157 Questions
Exam 24: Aggregate Demand and Aggregate Supply Analysis145 Questions
Exam 25: Money, banks, and the Federal Reserve System144 Questions
Exam 26: Monetary Policy145 Questions
Exam 27: Fiscal Policy155 Questions
Exam 28: Inflation, unemployment, and Federal Reserve Policy135 Questions
Exam 29: Macroeconomics in an Open Economy145 Questions
Exam 30: The International Financial System139 Questions
Select questions type


Figure 15-9  Figure 15-9 shows the cost and demand curves for the Erickson Power Company.
-Refer to Figure 15-9.The firm would maximize profit by producing
Figure 15-9 shows the cost and demand curves for the Erickson Power Company.
-Refer to Figure 15-9.The firm would maximize profit by producing (Multiple Choice)
4.8/5  (82)
(82) Which of the following statements applies to a monopolist but not to a perfectly competitive firm at their profit maximizing outputs?
(Multiple Choice)
5.0/5 (82)
(82) What is the difference between a public franchise and a public enterprise?
(Multiple Choice)
4.8/5 (85)
(85) If a monopolist's marginal revenue is $25 a unit and its marginal cost is $25,then
(Multiple Choice)
4.7/5 (73)
(73) What is a monopoly? Can a firm be a monopoly if close substitutes for its product exists?
(Essay)
4.9/5 (73)
(73) Consider an industry that is made up of nine firms each with a market share (percent of sales)as follows: a.Firm A: 30%
B)Firm B: 20%
C)Firms C,D and E: 10% each
D)Firms F,G,H and J: 5% each
What is the value of the Herfindahl-Hirschman Index and how is the industry categorized?
A) 1700; moderately concentrated
B) 1425; moderately concentrated
C) 1600; moderately concentrated
D) 2600; highly concentrated
(Not Answered)
This question doesn't have any answer yet
Economic efficiency requires that a natural monopoly's price be
(Multiple Choice)
4.9/5 (73)
(73) Natural monopolies in the United States are generally regulated by
(Multiple Choice)
4.9/5 (74)
(74) If a firm's average total cost is less than price where MR=MC,
(Multiple Choice)
4.8/5 (85)
(85) Figure 15-4 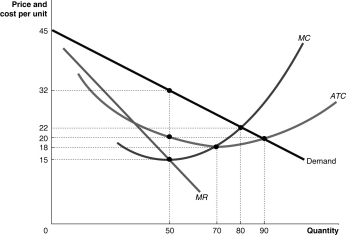 -Refer to Figure 15-4.Use the figure above to answer the following questions.
a.What is the profit-maximizing quantity and what price will the monopolist charge?
b.What is the total revenue at the profit-maximizing output level?
c.What is the total cost at the profit-maximizing output level?
d.What is the profit?
e.What is the profit per unit (average profit)at the profit-maximizing output level?
f.If this industry was organized as a perfectly competitive industry,what would be the profit-maximizing price and quantity?
-Refer to Figure 15-4.Use the figure above to answer the following questions.
a.What is the profit-maximizing quantity and what price will the monopolist charge?
b.What is the total revenue at the profit-maximizing output level?
c.What is the total cost at the profit-maximizing output level?
d.What is the profit?
e.What is the profit per unit (average profit)at the profit-maximizing output level?
f.If this industry was organized as a perfectly competitive industry,what would be the profit-maximizing price and quantity? (Essay)
4.9/5 (82)
(82) A local electricity-generating company has a monopoly that is protected by an entry barrier that takes the form of
(Multiple Choice)
4.8/5 (91)
(91) Figure 15-1  Figure 15-1 above shows the demand and cost curves facing a monopolist.
-Refer to Figure 15-1.If the firm's average total cost curve is ATC3,the firm will
Figure 15-1 above shows the demand and cost curves facing a monopolist.
-Refer to Figure 15-1.If the firm's average total cost curve is ATC3,the firm will (Multiple Choice)
4.9/5 (85)
(85) If a natural monopoly regulatory commission sets a price where marginal cost is equal to demand
(Multiple Choice)
4.9/5 (78)
(78) A product's price approaches its marginal cost as market concentration increases.
(True/False)
4.9/5 (98)
(98) The first important federal law passed to regulate monopolies in the United States was the
(Multiple Choice)
4.9/5 (85)
(85) If a per-unit tax on output sold is imposed on a monopoly's product,the monopolist will increase its market price by the full amount of the tax.
(True/False)
4.8/5 (87)
(87) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)