



 Chat with AI
Exam 7: Consumers, Producers, and the Efficiency of Markets

Exam 1: Ten Principles of Economics439 Questions
Exam 2: Thinking Like an Economist617 Questions
Exam 3: Interdependence and the Gains From Trade527 Questions
Exam 4: The Market Forces of Supply and Demand698 Questions
Exam 5: Elasticity and Its Application595 Questions
Exam 6: Supply, Demand, and Government Policies644 Questions
Exam 7: Consumers, Producers, and the Efficiency of Markets549 Questions
Exam 8: Application: The Costs of Taxation511 Questions
Exam 9: Application: International Trade493 Questions
Exam 10: Externalities524 Questions
Exam 11: Public Goods and Common Resources433 Questions
Exam 12: The Design of the Tax System551 Questions
Exam 13: The Costs of Production420 Questions
Exam 14: Firms in Competitive Markets543 Questions
Exam 15: Monopoly637 Questions
Exam 16: Monopolistic Competition587 Questions
Exam 17: Oligopoly496 Questions
Exam 18: The Markets for the Factors of Production564 Questions
Exam 19: Earnings and Discrimination490 Questions
Exam 20: Income Inequality and Poverty457 Questions
Exam 21: The Theory of Consumer Choice440 Questions
Exam 22: Frontiers of Microeconomics441 Questions
Select questions type


 -Refer to Figure 7-28. At the quantity Q3,

Table 7-10
The only four consumers in a market have the following willingness to pay for a good:
Buyer Willingness to Pay
 -Refer to Table 7-10. If there is only one unit of the good available for purchase, and if the buyers bid against each other for the right to purchase it, then the good will sell for
 (Multiple Choice)
5.0/5  (93)
(93) We can say that the allocation of resources is efficient if
(Multiple Choice)
4.9/5 (83)
(83) Figure 7-19  -Refer to Figure 7-19. At the equilibrium price, consumer surplus is
 (Multiple Choice)
4.9/5 (69)
(69) Figure 7-16  -Refer to Figure 7-16. Producer surplus amounts to $300 if the price of the good is
 (Multiple Choice)
4.9/5 (78)
(78) Given the following two equations:
1) Total Surplus = Consumer Surplus + Producer Surplus
2) Total Surplus = Value to Buyers - Cost to Sellers
Show how equation (1) can be used to derive equation (2).
(Essay)
4.8/5 (75)
(75) Table 7-11
The following table represents the costs of five possible sellers.
 -Refer to Table 7-11. Who is a marginal seller when the price is $1,100?
 (Multiple Choice)
4.8/5 (82)
(82) One of the basic principles of economics is that markets are usually a good way to organize economic activity. This principle is explained by the study of
(Multiple Choice)
4.8/5 (94)
(94) Kristi and Rebecca sell lemonade on the corner. It costs them 7 cents to make each cup. On a certain day, they sell 40 cups. Their producer surplus for that day amounts to $19.20. Kristi & Rebecca sold each cup for
(Multiple Choice)
4.8/5 (92)
(92) Table 7-11
The following table represents the costs of five possible sellers.
-Refer to Table 7-11. If the market price is $1,100, the combined total cost of all participating sellers is
-Refer to Table 7-11. If the market price is $1,100, the combined total cost of all participating sellers is (Multiple Choice)
4.7/5 (88)
(88) Five hundred units of good x are currently bought and sold. The marginal buyer is willing to pay $40 for the 500th unit, and the cost to the marginal seller is $35 for the 500th unit . We know that
(Multiple Choice)
4.9/5 (85)
(85) Tom tunes pianos in his spare time for extra income. Buyers of his service are willing to pay $155 per tuning. One particular week, Tom is willing to tune the first piano for $120, the second piano for $125, the third piano for $140, and the fourth piano for $160. Assume Tom is rational in deciding how many pianos to tune. His producer surplus is
(Multiple Choice)
4.9/5 (73)
(73) Scenario 7-1
Suppose market demand is given by the equation  -Refer to Scenario 7-1. If the market equilibrium price falls from $10 to $5, how much additional consumer surplus do consumers initially in the market at the $10 price receive?
 (Essay)
4.9/5 (67)
(67) Figure 7-7 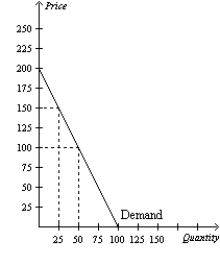 -Refer to Figure 7-7. What happens to the consumer surplus if the price rises from $100 to $150?
 (Multiple Choice)
4.9/5 (79)
(79) Pat bought a new car for $15,500 but was willing to pay $24,000. The consumer surplus is
(Multiple Choice)
4.8/5 (80)
(80) In which of the following circumstances would a buyer be indifferent about buying a good?
(Multiple Choice)
4.8/5 (79)
(79) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)